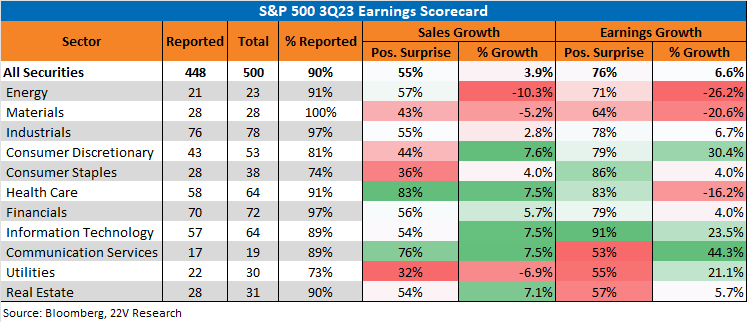
4Q reporting is winding down with only ~10% of companies left to report. Another strong earnings season has left FY23 EPS estimating at $216.8 and NTM EPS have increased to $242. Among major market groups, Early Cyclicals had the best y/y earnings and sales growth. Their margins have been strong as well with Tech and Comms responsible for ~30% of the total index profitability.
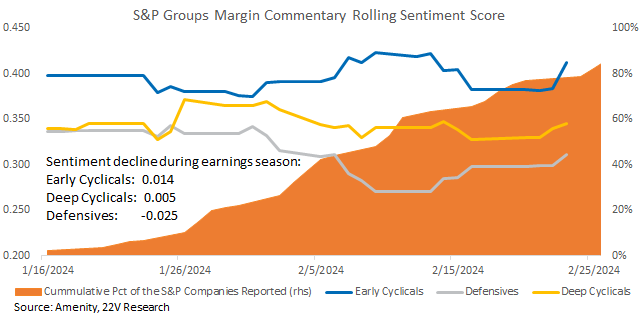
Margin expectations for the S&P have been mixed. Early Cyclicals’ forward looking margin sentiment is higher than beginning of the season, while Defensives margin sentiment dropped sharply. Rising margin sentiment should continue to support Early Cyclical and the profitability of the market as a whole.

Factor Focus: There was an interesting divergence between factor returns in 4Q. First, stocks that ranked highly according to fundamental factors, especially Value and Growth, tended to have the highest earnings surprise AND the best post-earnings price reactions. Stocks with high risk factor exposure had weaker surprises and mixed price reactions. The point being, historically and during this latest reporting season, focusing on beats misses within style factors has generated better returns around releases.
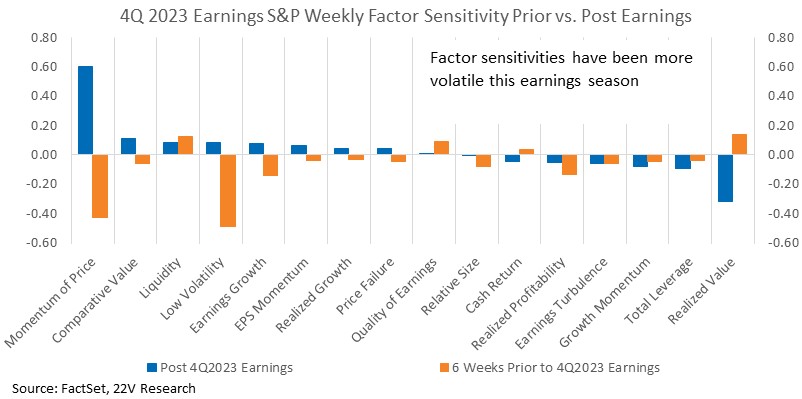
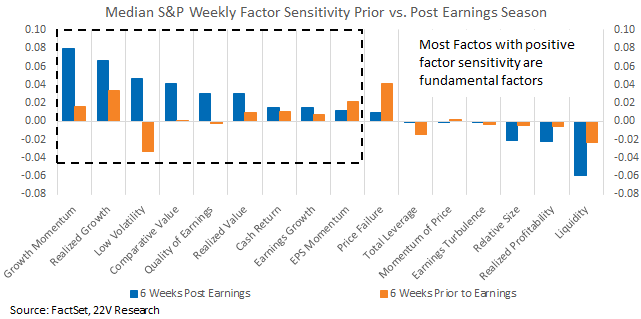
What was unusual were factor sensitivities around earnings. Historically, fundamental factors have positive sensitivities heading into earnings and in the weeks after reporting. In other words, fundamental factors contribute to return into report and that influence increases after earnings are released. Factor sensitivities have been more volatile during 4Q reporting. Increased policy uncertainty caused by the FOMC meeting and very strong Payrolls hampered contributed to swings in risk factors, which hampered the performance of fundamentals. Easing of that uncertainty is part of the reason we expect to see some catchup in those factors.
Week Ahead: At the end of this report we also update the list of names in our earnings season swaps (MS22BEAT Index and MS22INEX Index, details HERE) that will be reporting next week.
Early Cyclicals Supporting Profitability: 4Q earnings are winding down with ~90% of names reported. Earnings remained strong consistent with strong economic data in the back half of 2023. FY23 S&P EPS are now estimates to be $216.8 and NTM EPS are running at $242. Early Cyclicals including Tech, Communications and Discretionary all reported strong y/y earnings and sales growth and most Mega 7 beat estimates (ex TSLA).
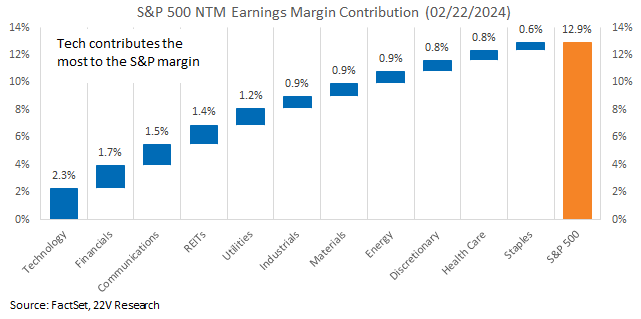
Margins for the S&P again beat expectations. Technology, Financials and Communications were the biggest contributors to S&P profitability. All sectors were positive, but the margin contribution from Early Cyclical sectors all increased in 2023 at the expense of Deep Cyclicals (with the exception of Industrials) and Defensives.
Margin expectation sentiment changes were mixed with Early Cyclicals margin sentiment increasing over the course of 4Q reporting while Defensives declined. Positive earnings sentiment should continue to support Early Cyclicals profitability. Margin sentiment has weakened some, which is consistent with some moderation in margins in 1Q. Importantly, the level of margins coming out of 4Q will be higher than expected, providing room for some moderation in margins without a negative pass-through to expected earnings levels.
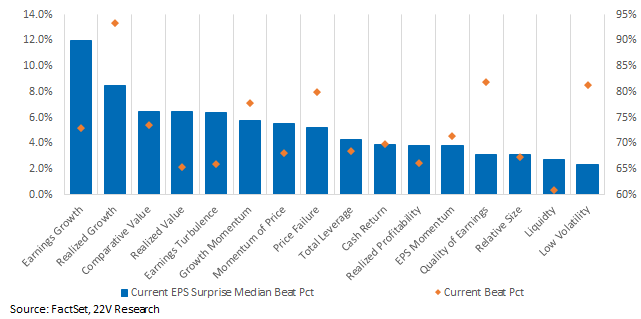
Factor Focus – Beat Rates & Returns: Factor earnings surprises, measured as the surprise rate of S&P stocks falling into the top decile of each factor basket before earnings release, was highest for Growth and Value factors. The beat percent for Realized Growth is the highest of all factors in 4Q, reaching 93.3%. Earnings surprise for Value is a bit mixed especially for Realized Value as its beat percent is lower than the index.
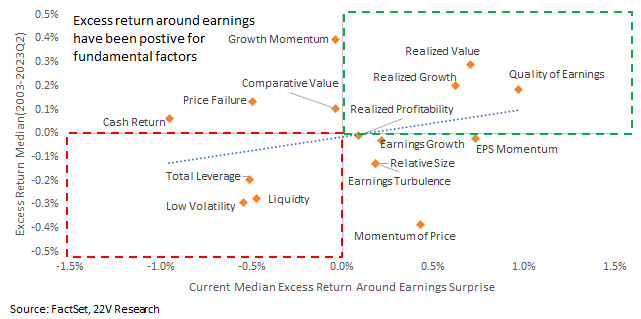
Excess returns around 4Q earnings release have been positively correlated with historical patterns. Most fundamental factors saw a positive relationship between earnings beats and returns – a high Quality names that beat EPS estimates outperformed while ones that missed underperformed. Returns to Risk factors were less consistent, which is normally the case. Historically and during this latest reporting season, focusing on beats misses within style factors has generated better returns around releases.
Factor Focus – Sensitivities: 4Q reporting season overlapped with the Jan FOMC meeting and the Payroll number that added to macro and policy uncertainty. The result was an unusual pattern of factor sensitivities. More than half of the factor sensitivities reversed during reporting season, which is atypical. Price Momentum and Comparative Value saw the biggest shifts and were positive contributors. Realized Value went from a positive contributor leading into reporting to a negative one since.
Historically, factor sensitivities for fundamental factors are usually positive during the earnings season. With macro uncertainty easing some and earnings results strong within fundamental factors, we expect to see some catch up in these names to bring them closer in line with historical trends.
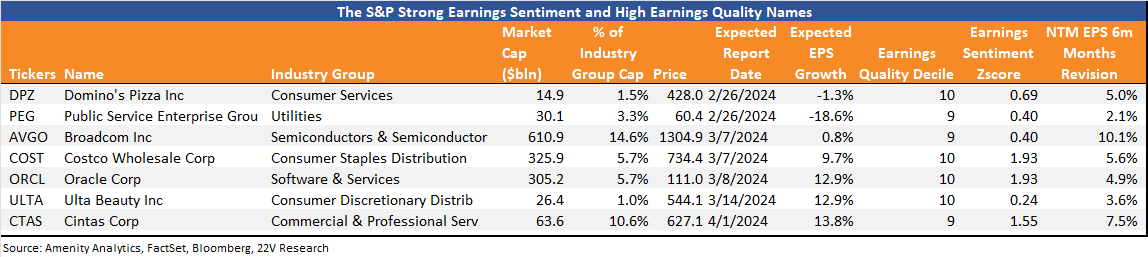
Week Ahead: We launched two Swaps during the earnings season (MS22BEAT Index and MS22INEX Index, details HERE). Below we list the S&P names unreported that have strong Earnings Quality and positive earnings sentiment.
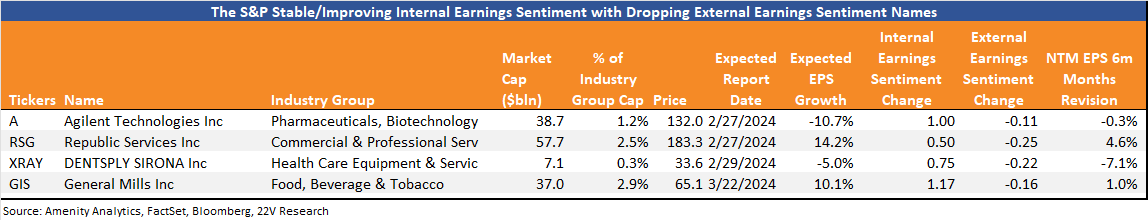
The unreported S&P names with increasing/stable internal earnings sentiment while dropping external sentiment is listed below as well.