Quick summary of our client survey this week on China:
- Investors either think that Chinese/Hong Kong equities are cheap or that they are “uninvestible” at any price. In other words, there aren’t many investors waiting for equities to get cheaper.
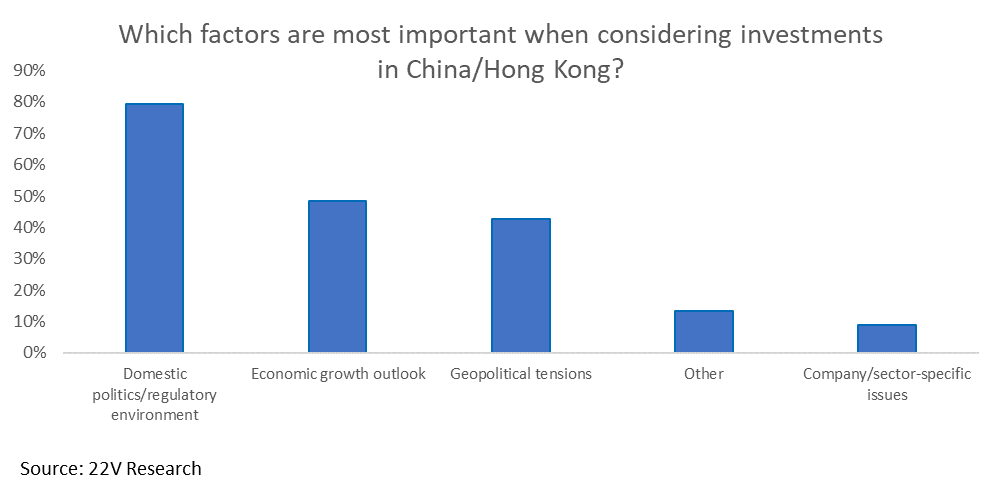
- Investors cite China’s domestic politics and regulatory environment as the most important factor when considering investments, followed by China’s growth outlook and geopolitics.
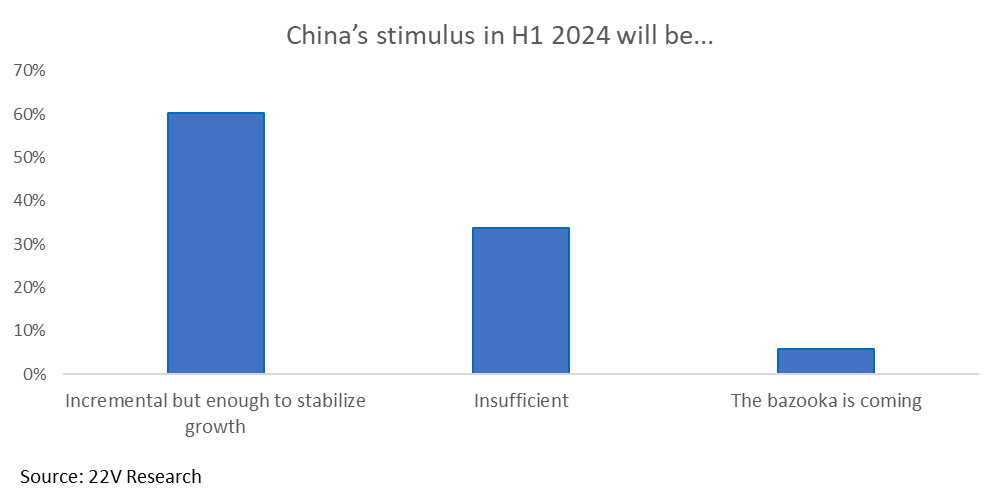
- Most investors expect incremental stimulus from Beijing that is enough to stabilize growth, but with a sizable group that believes stimulus will be insufficient.
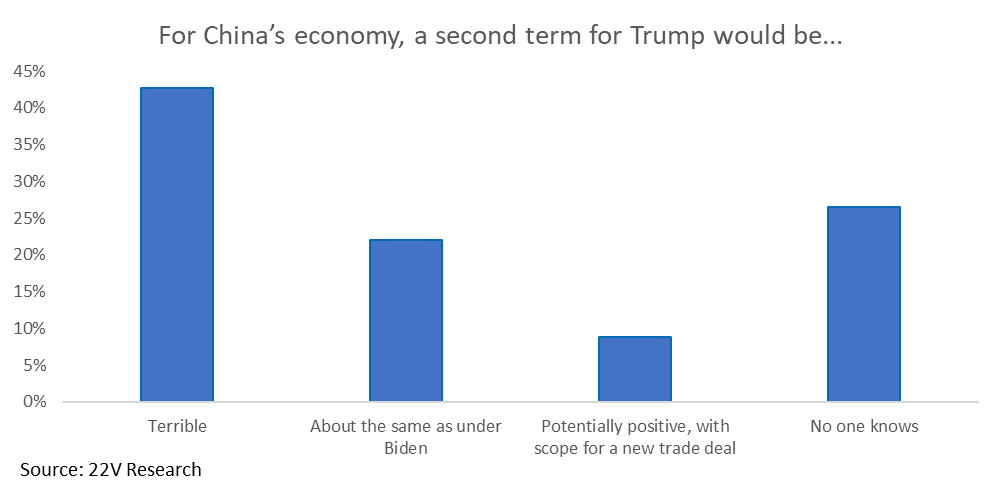
- Around 40% of investors think that a second term in office for Donald Trump would be “terrible” for China. The rest think that “no one knows” or that Trump’s impact would be about the same as under a Biden administration.
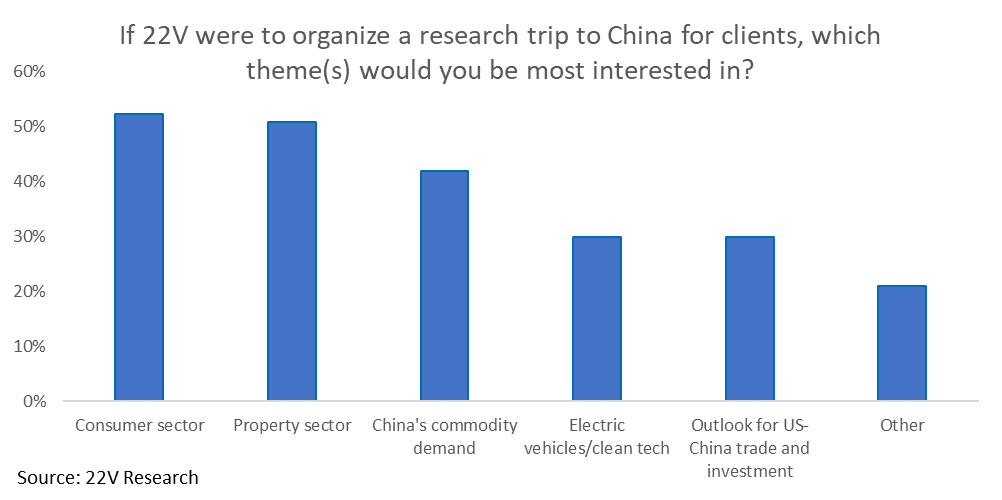
- Asked about a 22V client trip to China, investors cite a wide range of topics of interest, including China’s consumer sector, the outlook for property and commodities, tech and clean energy sectors, and debt risks.
Outlook for equities: Views on Chinese/Hong Kong equity markets are polarized. Investors either think equities are cheap or that they are “uninvestible” due to a lack of confidence in Beijing’s policies. There don’t seem to be many investors waiting for Chinese stocks to get cheaper…

What matters most for China investments: China’s political/regulatory environment is the most important factor for clients considering investments, followed by the growth outlook and geopolitical tensions. Our take on domestic policy is that the probability of major new regulatory crackdowns is low, as Xi Jinping’s new economic team tries to revive private sector and investor confidence. But Xi’s fundamental governance approach – with a focus on party control, national security, and active intervention – will stay in place and continue to be a source of risk for investors and the long-term outlook.
Stimulus expectations are modest: Most clients expect only incremental stimulus this year, but enough to stabilize growth. A solid minority think stimulus will be insufficient. Our take leans towards the former: incremental stimulus will put a floor under growth of around 4.5% this year – we are not worried about a “hard landing” – but it won’t be of the necessary scale or type to revive private sector confidence or decisively put an end to deflationary pressures. Very few investors think Beijing will bring out the “bazooka” and we agree that it is extremely unlikely.
The Trump factor. 40% of clients think that a second term for Trump would be “terrible” for China, while around 20% think it would be about the same as under Biden. We will lay out our views in a forthcoming note. Suffice to say that while Trump would be net negative for China’s economy, it is not a cop-out to side with the 25% of clients who think “no one knows.” It won’t be clear how aggressively Trump would push China, and in which areas, without seeing his cabinet selections and other early moves.
Topics of interest for a China trip: Asked about themes of interest for a 22V client trip to China this year, the two most popular responses were China’s consumer sector and the outlook for property. Popular write-in responses included debt risks and China’s tech sector. (We will be back in touch regarding plans for a trip later this year, but please feel free to reach out to your sales rep in the meantime if you are interested.)