Bottom Line: Last week Risk-On underperformance started to turn. Deep Cyclicals (Energy, Industrials, Materials) significantly outperformed Defensives (Utilities, Staples, Healthcare), SMID bounced and Low Volatility names underperformed. Stronger economic growth has reduced the expected number of Fed rate cuts, but financial conditions have not tightened. That is consistent with our view that the economic data so far in 1Q24 has been consistent with a positive growth shock, vs an inflation shock. Last week’s benign CPI revisions and the decline in the Atlanta Fed’s wage tracker helped reduce the risk of inflation remaining at too high of a level. It reinforced the positive growth shock, not inflation shock, theme.
Relevant News: NY Fed Consumer inflation expectations measure came in at 3% vs 3.01% prior. At the same time, median one year ahead earnings growth and median household income growth increased. That is a positive combo. The market started to move up before the number hit and accelerated after the number hit.
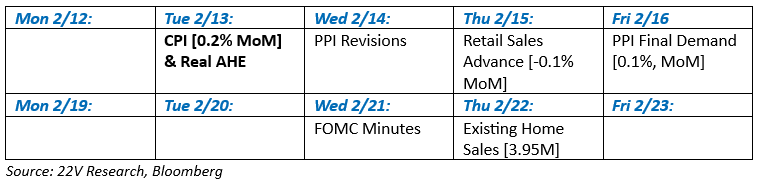
Things to Watch [Consensus]:
Portfolio Strategy: Earnings & Margins Ex the Mag 7
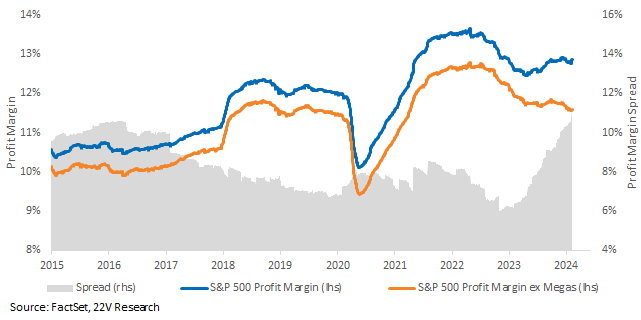
Sales expectations for the S&P 500 ex Mag 7 are climbing. Without attempting false precision, they are moving up with nominal GDP. Nominal GDP growth has been firm, and we expect it to stay that way.

EPS expectations are NOT moving up though. Margin expectations ex the Mag 7 have been paltry. The bid to the mega cap names makes sense in this context.
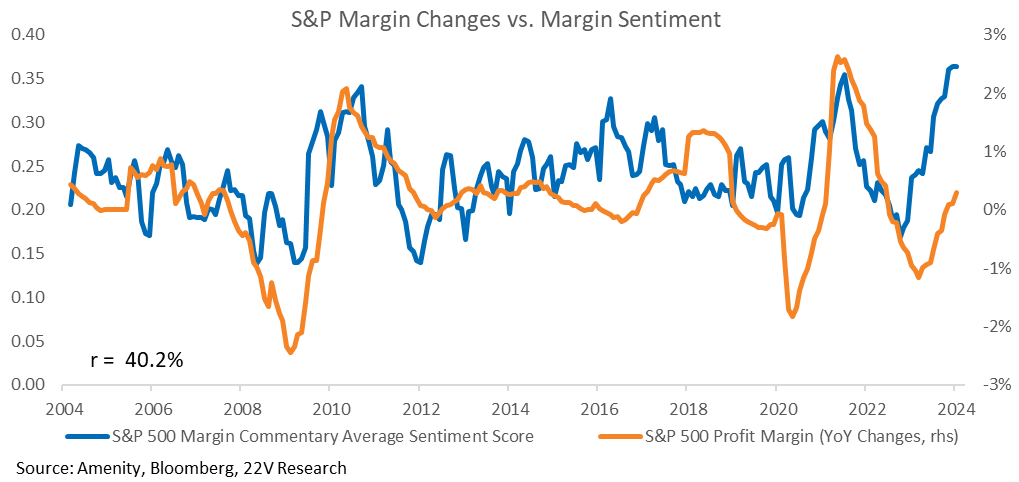
Margin sentiment, which we show on an equally weighted basis below (So ex Mag 7 it would look about the same), has improved materially. With margins likely to improve for the other 493 and sales tracking nominal GDP estimates, there seems like decent earnings upside to the other 493 companies. FYI – Margin sentiment is correlated with actual margin results one quarter out, so the sentiment readings are another sign, along with strong growth data, that profitability is not at risk near-term.
Quant: Value Divergence from Macro Trends
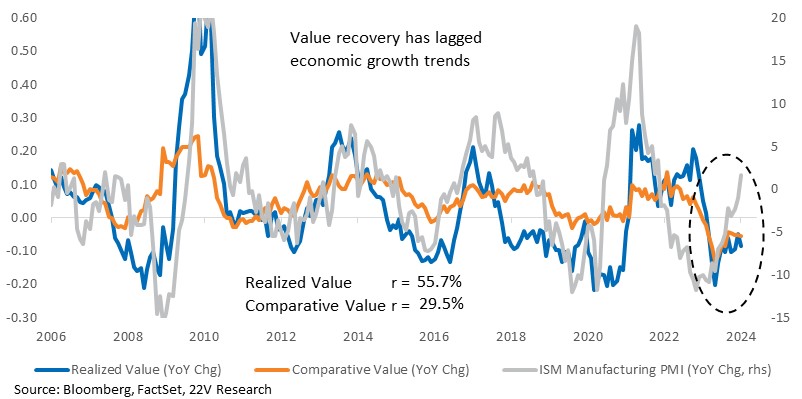
Historically, Value factor performance has been positively correlated with various leading indicators. PMIs and Value factor returns tend to be positively correlated for instance. PMIs bottomed out and moved higher over the past several months, contributing to the firming of the overall macro backdrop. Near-term, the MUCH stronger than expected earnings reporting season has boosted Growth, and policy uncertainty has stood in the way of a strong Value rotation. Value factors become more attractive after reporting season winds down, assuming no new policy shocks.
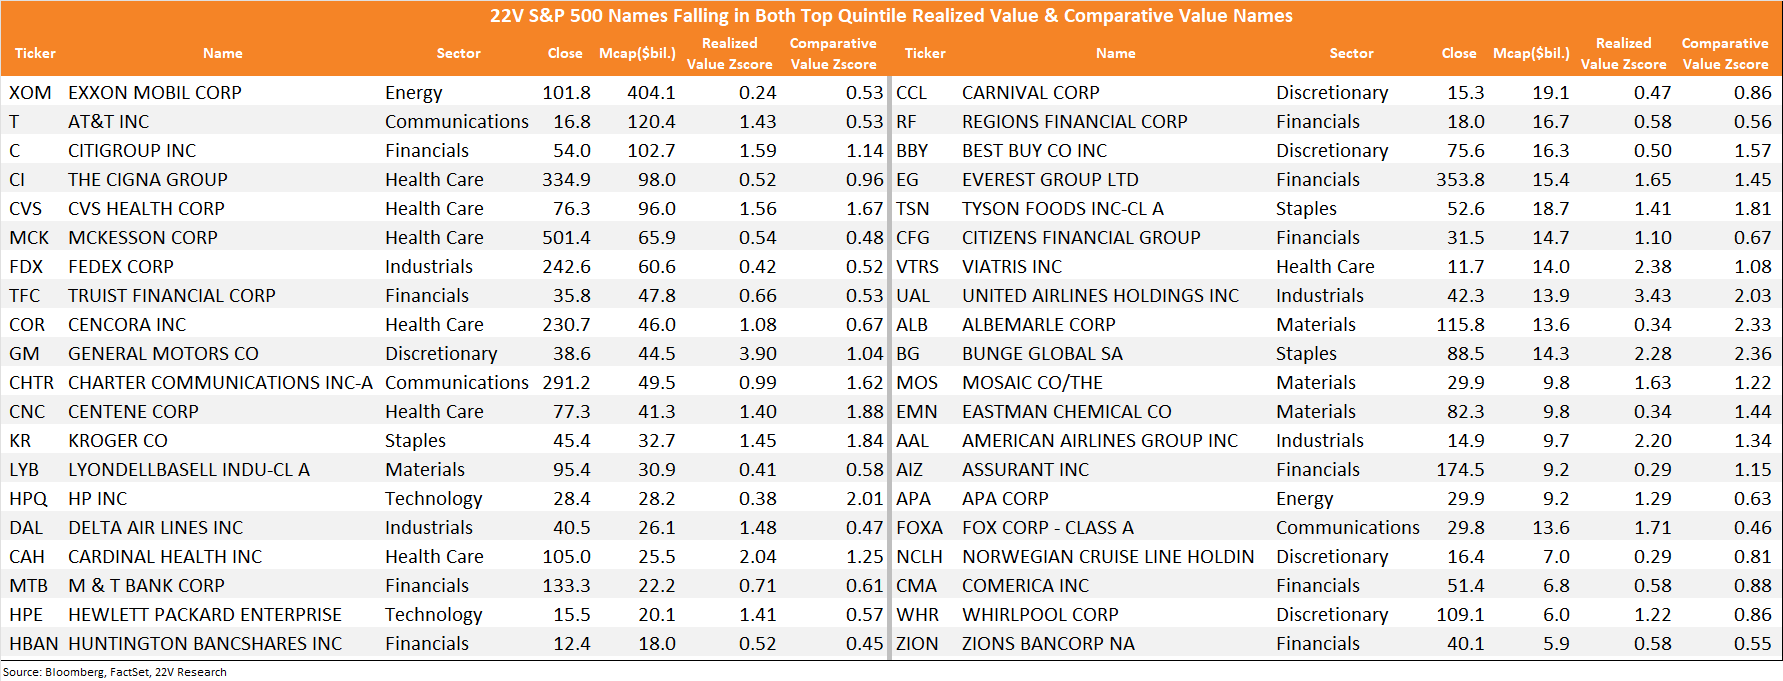
Below, we list the S&P names most exposed to both Realized Value and Comparative Value. An expected rebound from Value factors should benefit the names below. A similar ranking approach can be applied across custom universes or portfolios.
Commodities: Early Innings of Long Solar
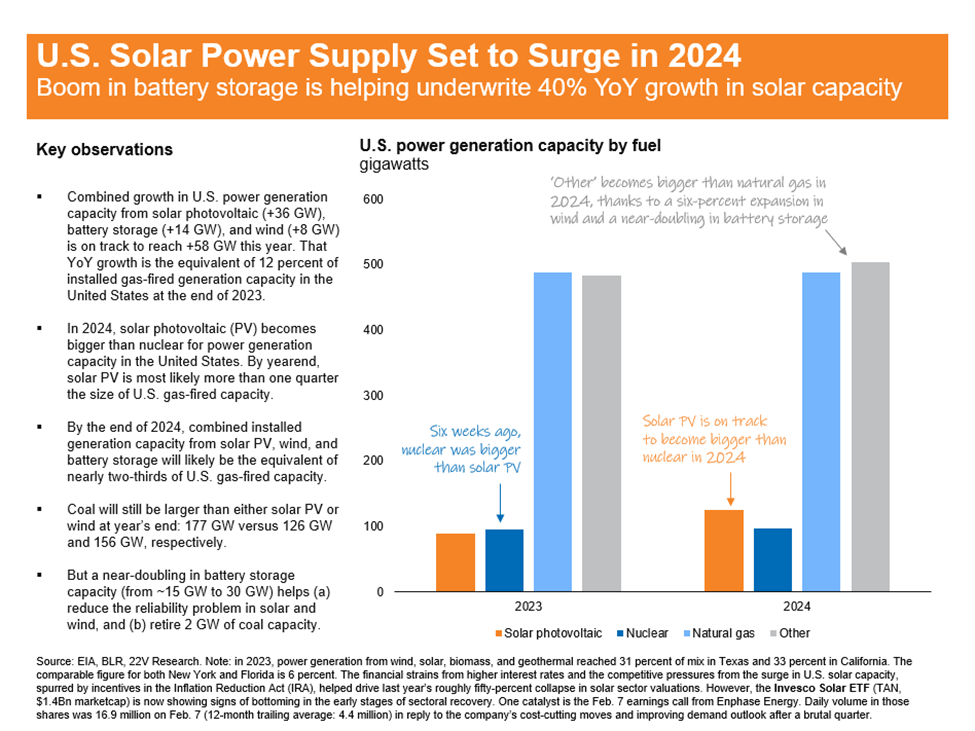
We are in the early innings but are starting to work on getting LONG solar. Some points from 22V’s commodities analyst below (see chart bullets for further commentary):
1. A near doubling of battery storage capacity helps
a. Reduces the reliability problem in solar and wind.
b. Retire 2 GW of coal capacity.
2. Sunworks (SUNW) filed for Chapter 7 on Feb. 5. SunPower (SPWR) breached covenants two months ago, issued a going-concern warning, and has an upcoming Feb. 16 bogey for a debt repayment. Shakeout of losers and winners is most definitely underway after surging costs (materials, interest) and collapse in revenues and valuations.
3. Feb. 7 earnings call from Enphase Energy was a positive catalyst, which led to a share price boost on huge volume. But sentiment remains traumatized, esp because belief was so fervent and uncritical before the price collapse.