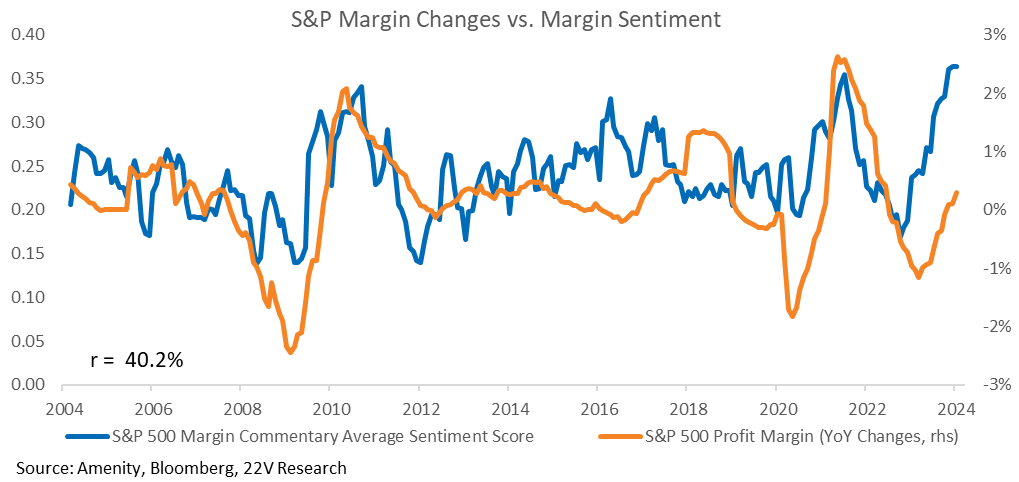
Nearly half of S&P companies have reported, and earnings have remained robust. Y/Y earnings growth for reported names is ~4% and estimate revisions are being revised higher as well. Importantly, both earnings sentiment and margin sentiment expressed by the management remain strong too. Forward looking margin sentiment has climbed to the high end of its range and is correlated with actual margin results one quarter out.
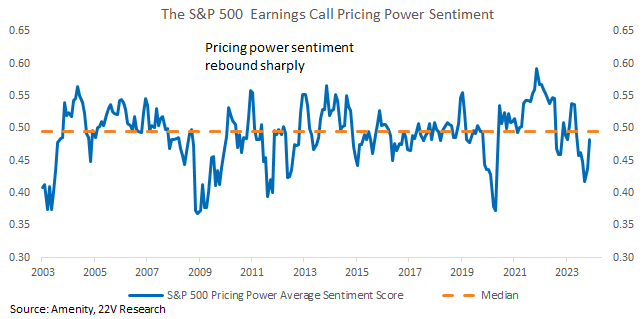
In addition, sentiment toward pricing power – views related to the pricing of products or services – has rebounded sharply over the past two weeks along with an increase in price sentiment. Both are supports for margins. The risk comes from increasing concerns toward costs. The bottom line is that sentiment readings are another sign, along with strong growth data, that profitability is not at risk near-term.
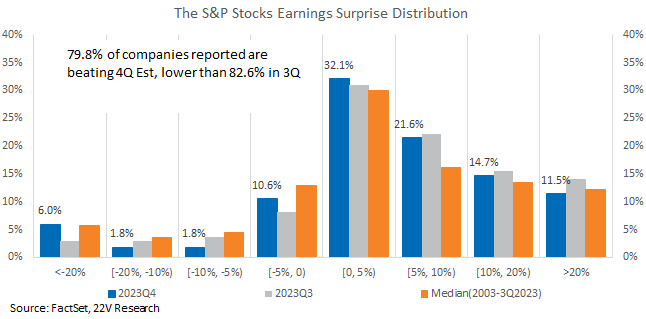
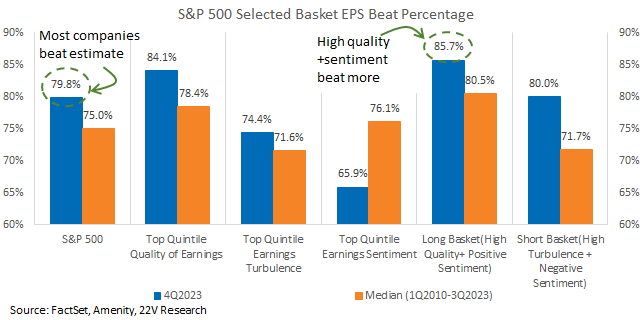
For the half S&P companies reported, ~80% of the names beat estimates, which is stronger than normal but down a touch from 3Q’s results. Beats have been concentrated in the low (0-5%) range where excess returns tend to be slightly negative. Excess returns around earnings remain mixed and less related to beat percent than normal, making it harder to profit from earnings surprises.
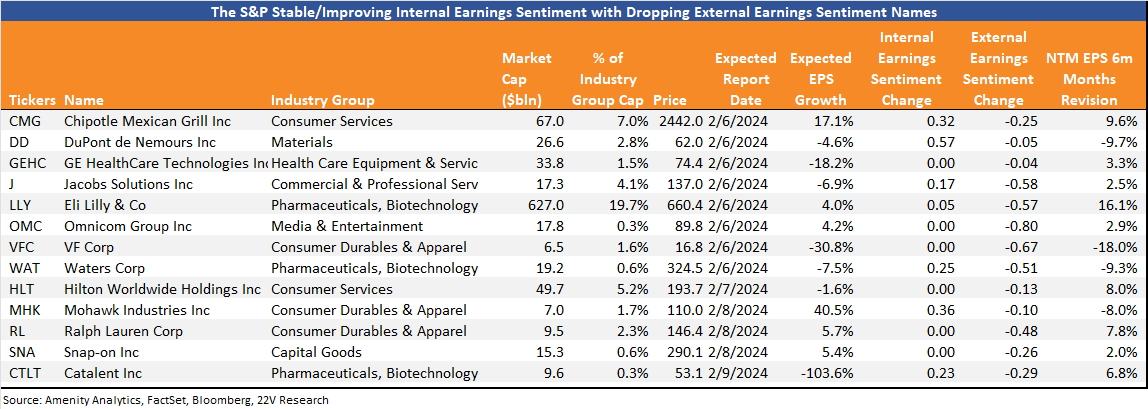
We continue to favor the names of strong Earnings Quality and positive earnings sentiment and list the names falling into that basket near the end of this report. The whole basket is tradable as a swap with ticker MS22BEAT Index. The S&P names reporting next week in our earnings sentiment reversal basket are at the end of the report (Swap ticker: MS22INEX Index). These are names with stable or increasing internal earnings sentiment and dropping external earnings sentiment. This quarter external earnings sentiment has rebound as earnings reporting has increased. The macro growth concerns expressed during 3Q have failed to materialize, which is supporting the improvement in external sentiment.
In the full report, we also update beat rates and revisions and look at the factor drivers of sectors leading into and during reporting.
Price & Pricing Power Sentiment Supported Margins: Nearly half of S&P companies have reported, and earnings have remained robust. Y/Y earnings growth for reported names is ~4% and estimate revisions are being revised higher as well. Importantly, both earnings sentiment and margin sentiment expressed by the management remain strong. Margin sentiment has climbed to the high end of its range for both forward looking commentary and current results. Margin sentiment is correlated with actual margin results one quarter out, so the sentiment readings are another sign, along with strong growth data, that profitability is not at risk near-term.

In addition, sentiment toward pricing power – views related to product or service prices – has rebounded and climbed sharply over the past two weeks along with rebounding price sentiment. Both are support for margins. The risk comes from increasing concerns about costs, which led to dropping cost sentiment.
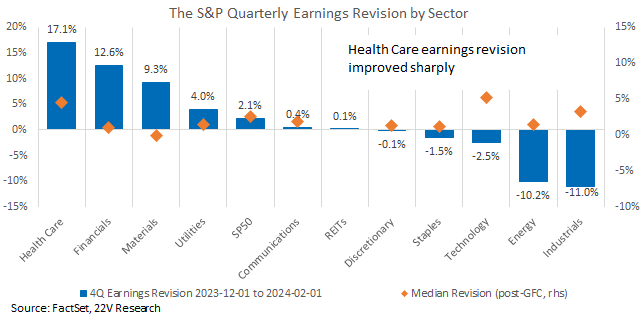
This week, earnings revision for the S&P climbed to 2.1%, with Defensives seeing an outlier move higher. Overall S&P revisions are catching up to their long-term median and have accelerated alongside reporting. Deep Cyclicals revision rebounded slightly this week but remains a drag on the overall index level.
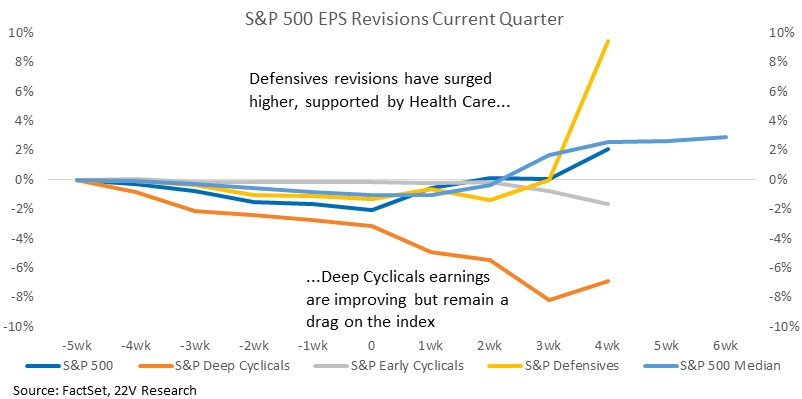
Health Care is the sector with the strongest revision this past week and the growth estimates for the group have increased 17% relative to early December last year. Health Care is also one of the best performing sectors this week, with a 1.6% excess return.
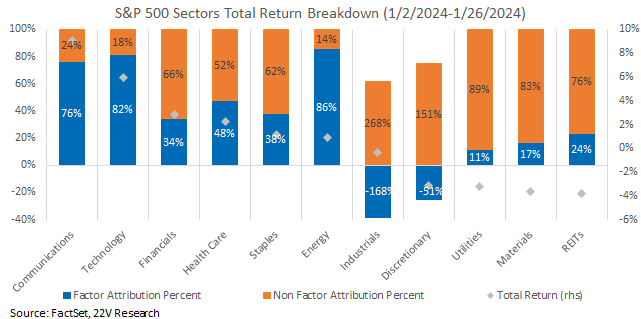
A breakdown of S&P sector total returns shows that so far this year, Early Cyclicals have been the biggest support, led by Communications and Technology. A large proportion of those gains can be explained by factors exposures.
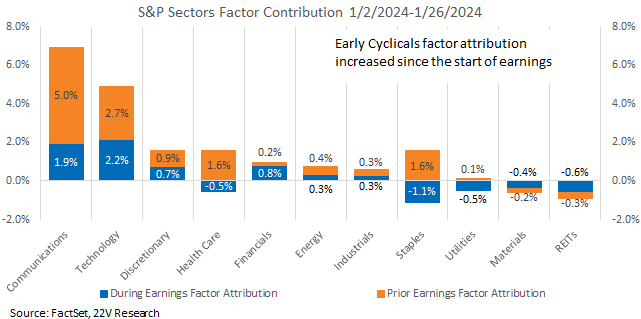
Price Mo has been the largest driver for both Communications and Technology, with more than 1.8% of the total return contributed from the factor over the past two weeks. Low Volatility and Relative Size also contributed to them before earnings, but that contribution has fallen off during earnings and the more risk-on market phase.
For the half S&P companies reported, ~80% of the names beat estimates, which is stronger than normal but down a touch from 3Q’s results. Beats have been concentrated at the low (0-5%) range where excess returns tend to be slightly negative. Excess returns around earnings remain mixed and less related to beat percent than normal, making it harder to profit from earnings surprises.
Our selected beat basket continues to work in the current earnings season as 85.7% of the reported names with strong earnings quality and positive earnings sentiment beat estimates, higher than the S&P index as well as all other groups.
We continue to favor the names of strong Earnings Quality and positive earnings sentiment, and the names falling in the basket reporting next week are below. The whole basket is tradable as a swap with the ticker MS22BEAT Index.
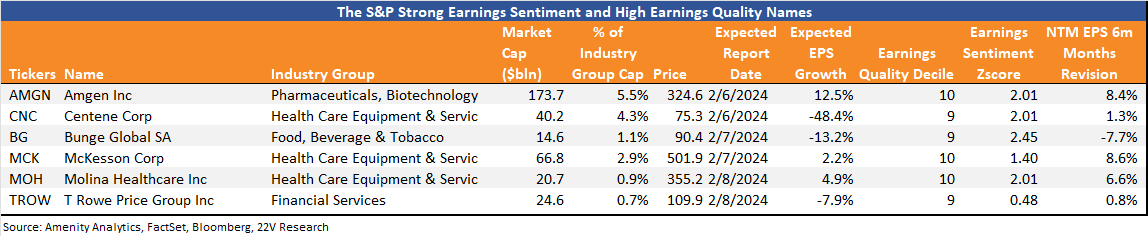
The S&P names reporting next week in our earnings sentiment reversal basket are below (Swap ticker: MS22INEX Index). These are names with stable or increasing internal earnings sentiment and dropping external earnings sentiment. This quarter external earnings sentiment has rebounded as earnings reporting has increased. The macro growth concerns expressed during 3Q have failed to materialize, which is supporting the improvement in external sentiment.