Back Quantitative

Quant Market Diagnostics: Deep Cyclicals Earnings Outlook Lagging Other Groups

Published on January 26, 2024

∙ Download the PDF Report

By

Dennis DeBusschere

Brian Herlihy

Sophia Wang

Kevin Brocks

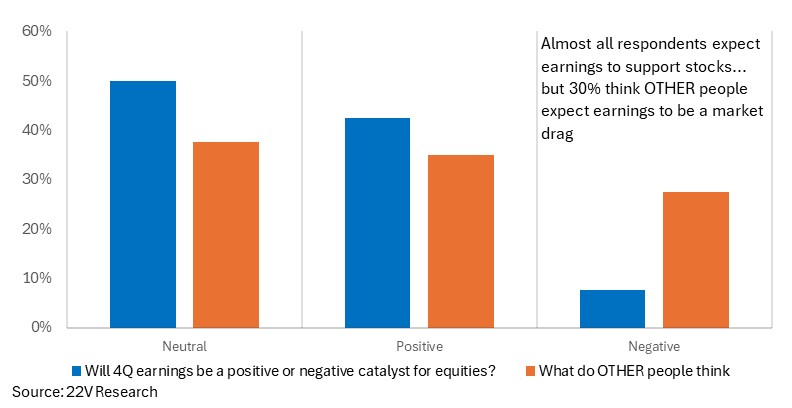
4Q earnings releases are starting to ramp up (~25% of S&P names have reported so far) and there is an interesting divergence in expectations. According to our survey work (HERE), almost all (92.5%) of the investors expect a neutral or positive market impact from 4Q earnings. BUT ~30% of respondents think other people are looking for a negative market reaction. The conclusion is that we should expect a neutral/positive reporting season market return.

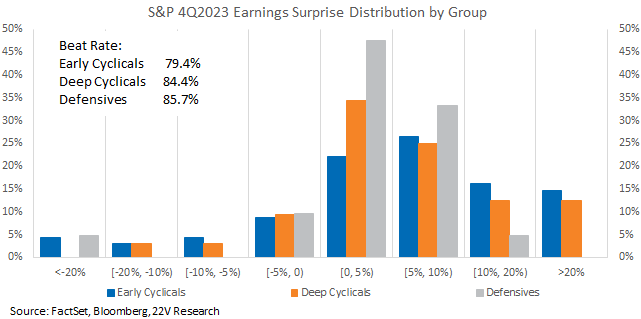
Defensives have had highest beat percent with an 86% beat rate, but the n is small (21). Also, most of the Defensive beats are in the 0-5% range, which isn’t typically enough to generate excess performance. Early Cyclicals have a lower bear rate (79%), with ~3x the number of names reported. There have also been a larger number of large beats within Early Cyclicals. The takeaways are 1) beat rates are high across groups, and 2) Cyclicals in general have had more of the large beats that tend to lead to outperformance.
A graph of numbers and numbers

Description automatically generated with medium confidence

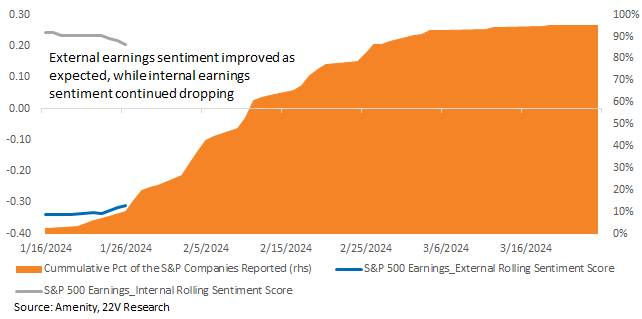
EPS sentiment has been moving higher, recovering from its 3Q decline. We break earnings sentiment into two groups, external earnings sentiment (macro influenced) and internal earnings sentiment (company specific, long-term charts HERE). That distinction is useful during periods of macro recoveries like we are in today. Firm macro trends should reduce management negativity over time, resulting in an upward bias to sentiment and estimates. The headwind we need to track is the weakening of internal sentiment. If internal sentiment falls too sharply, it would offset the easing of macro concerns.

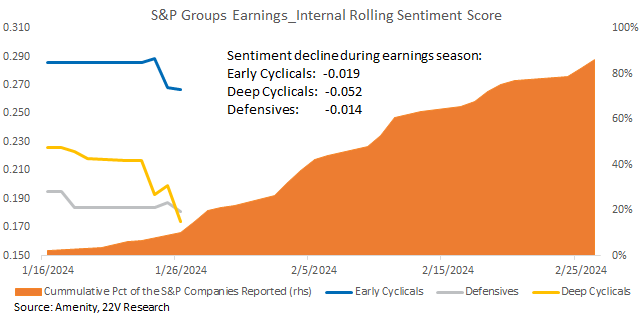
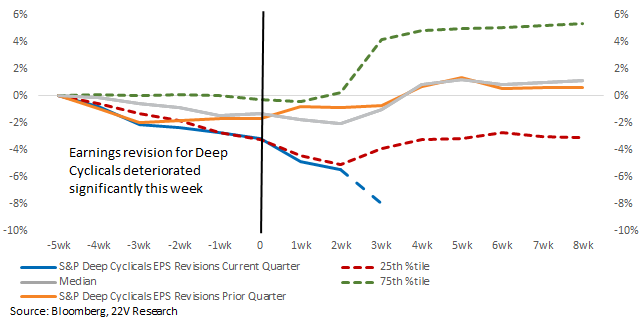
Though internal earnings sentiment for all sector groups dropped, Deep Cyclicals have seen the greatest deterioration, especially sentiment around supply chains and capacity production. Earnings revision for the S&P have been positive over the past few weeks, but Deep Cyclical revisions were weak heading into reporting and have deteriorated since. That suggests embedded fundamental headwind for Deep Cyclical names even as the overall macro backdrop has rebounded.

Deep Cyclicals Earnings Outlook Lagging Other Groups: 4Q earnings releases are starting to ramp up (~25% of S&P names have reported so far) and there is an interest divergence in expectations. According to our survey work (HERE), almost all (92.5%) of the investors expect a neutral or positive market impact from 4Q earnings. The median estimate for 4Q EPS growth is for a better than consensus estimate. BUT ~30% of respondents think other people are looking for a negative market reaction. The bottom line, applying the surprisingly popular method described in the abstract HERE, the conclusion remains tilting towards a neutral/positive reporting season return.
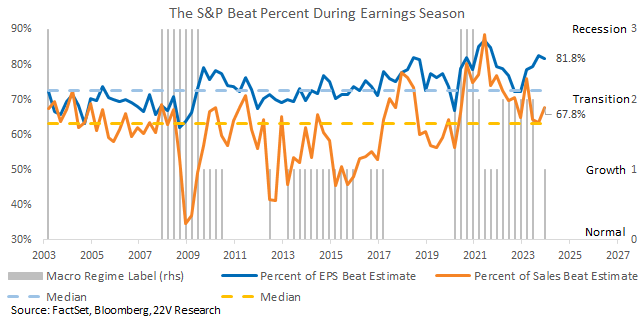
So far, early reporters have been in line with the survey expectations. ~82% of reporters beat EPS estimates, and 68% beat on revenue. Both readings are higher than normal, and growth estimates have been revised higher. So far, beats have been rewarded less than usual, while miss returns have been mixed. We expect beats will have a better than normal beat miss skew as macro concerns that restrained some stocks coming out of 3Q reporting fade.
A graph of a graph showing the amount of the amount of the amount of the amount of the amount of the amount of the amount of the amount of the amount of the amount of the amount of

Description automatically generated

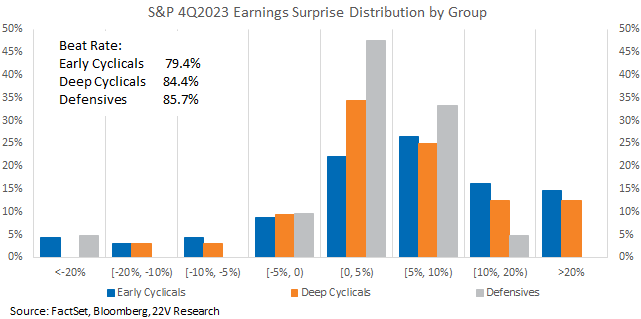
Defensives have the highest beat percent with an 86% beat rate, but the n is small (21). Also, most of the Defensive beats are in the 0-5% range, which isn’t typically enough to generate excess performance. Early Cyclicals have a lower bear rate (79%), with ~3x the number of names reported. There have also been a larger number of large beats within Early Cyclicals. The takeaways are 1) beat rates are high across groups, and 2) Cyclicals in general have had more of the large beats that tend to lead to outperformance.
A graph of numbers and numbers

Description automatically generated with medium confidence

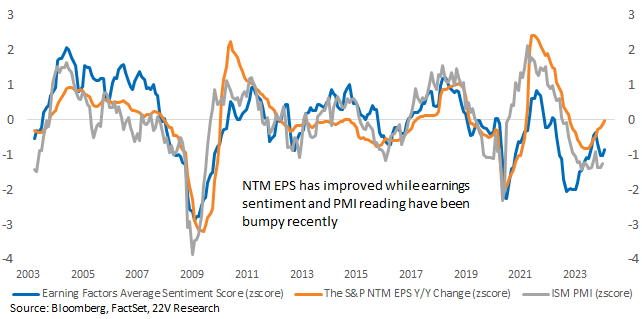
EPS sentiment has been moving higher, recovering from its 3Q decline. The biggest headwind in 3Q were macro concerns, so the improvement in sentiment is consistent with the generally better than expected macro data released over the past couple of months. In addition, NTM EPS estimates have been trending higher, which is strongly correlated with earnings sentiment trends.
A graph of a graph showing the growth of stocks

Description automatically generated with medium confidence

We break earnings sentiment into two groups, external earnings sentiment (macro influenced) and internal earnings sentiment (company specific, long-term charts HERE). That distinction is useful during periods of macro recoveries like we are in today. Firm macro trends should reduce management negativity overtime, resulting in an upward bias to sentiment and estimates. The headwind we need to track is the weakening of internal sentiment. If internal sentiment falls too sharply, it would offset the easing of macro concerns.
A graph of a growing graph

Description automatically generated with medium confidence

Though internal earnings sentiments for all sector groups dropped, Deep Cyclicals have seen the greatest deterioration, especially sentiment around supply chains and capacity production. The increase for Deep Cyclicals external earnings sentiment was also the lowest among all three groups. That suggests embedded fundamental headwind for Deep Cyclical names even as the overall macro backdrop has rebounded.
A graph of a graph showing the fall of the company's earnings

Description automatically generated with medium confidence

Earnings revision for the S&P have been positive over the past few weeks, rebounding from an unusually low level at the start of reporting (more HERE). Again, Deep Cyclicals is a source of weakness though. 4Q Deep Cyclical revisions were weak heading into reporting and have deteriorated since, which is aligned with sentiment deterioration. Deep Cyclicals have performed better as growth data has beat, but the fundamental underpinnings for the group are a concern.
A graph of different colored lines

Description automatically generated

More than 20% of the S&P names will report next week, including 5 mega cap Tech names. Below we list the names meeting strong earnings Quality and earnings sentiment criteria reporting next week. Our earnings beat Swap (bbg MS22BEAT Index) is currently tradable based on the idea.
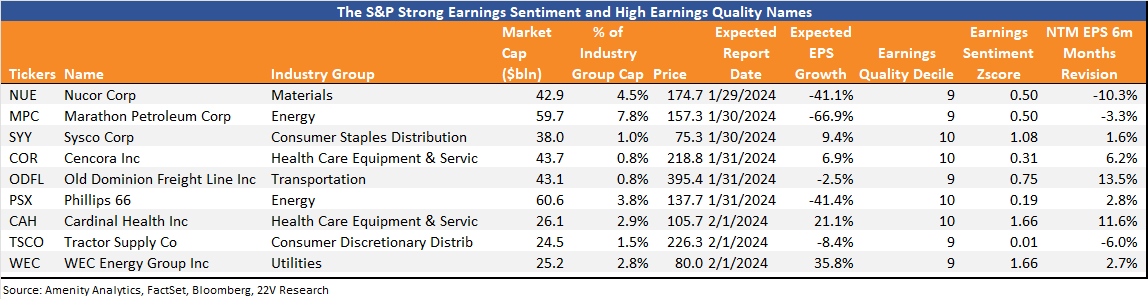
A screen shot of a table

Description automatically generated

The names with increased/stable internal earnings sentiment and low external earnings sentiment in 3Q that are reporting next week are listed below. The external earnings sentiment rebound Swap (bbg MS22INEX Index) is filtered for same criteria to benefit from macro rebound.
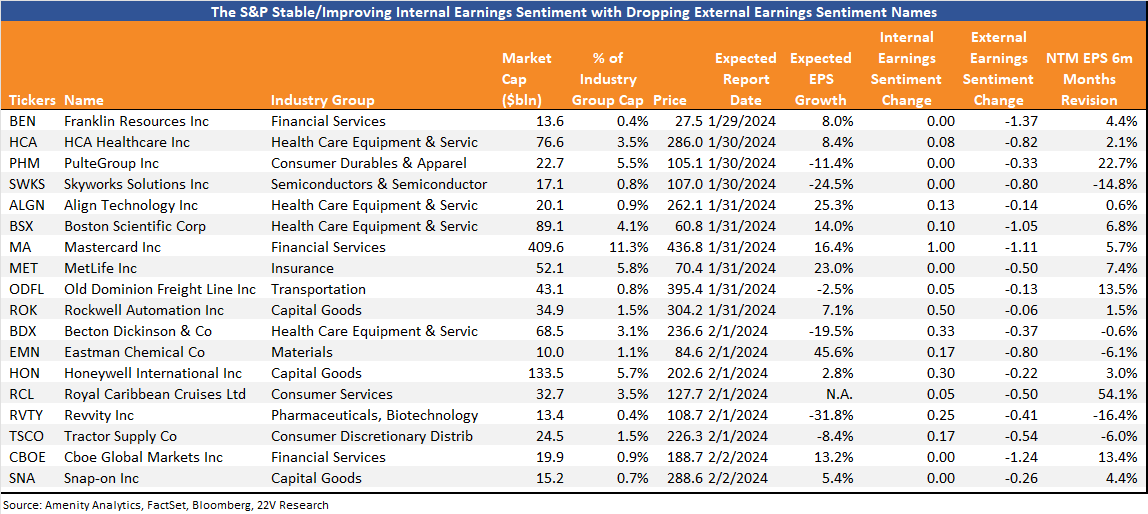
A screenshot of a screen

Description automatically generated

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.