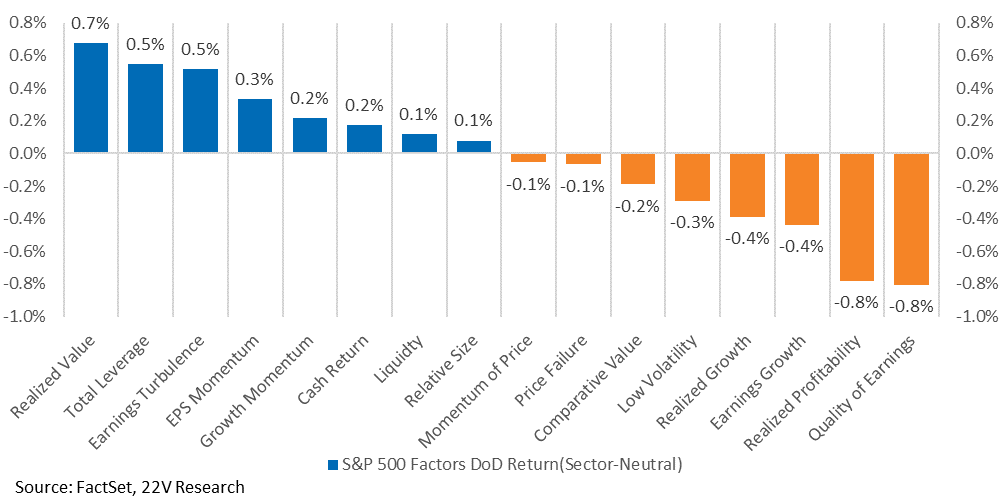
SUMMARY: 4Q23 GDP beat expectations yesterday, coming in at +3.3% (ar) vs estimates of 2%. Net exports and gov’t inflate the beat, but the underlying domestic demand conditions (the most important bits for the economic outlook) look solid. Personal spending grew 2.8% vs 2.5% expected. The bottom line is that growth is stronger than expected and considerably better than feared. That is an important support for a rebound in market laggards. Small caps outperformed large yesterday. Value and risk-on factors, segments that have most lagged the firming economic backdrop, were yesterday’s best performers.
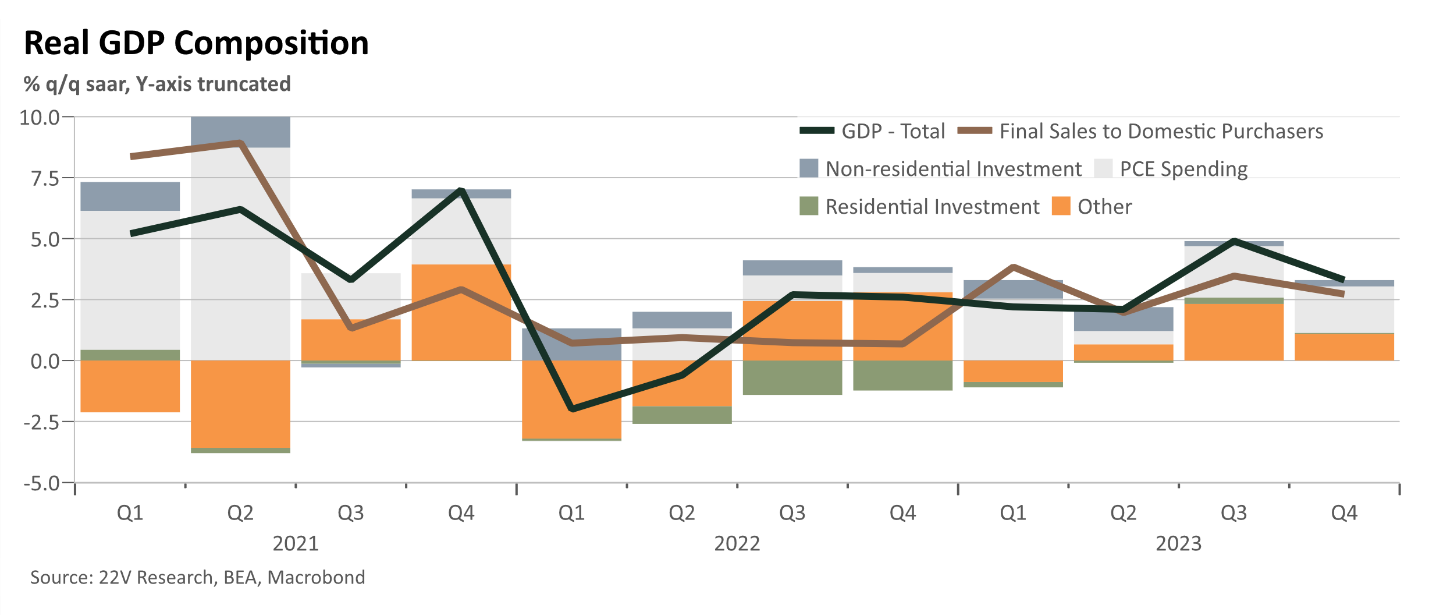
PETER’S GDP BREAKDOWN: Peter’s longer-term take on the data is that recession risk is declining. We pull from his report (HERE), but the money line is “Having the same causal story running for strongly recession calls, or very elevated odds, seems a stretch; at some point the mechanism just isn’t working.” This is an important point when thinking about the direction of travel over the next several months. Focus is shifting to how stronger growth influences internals.
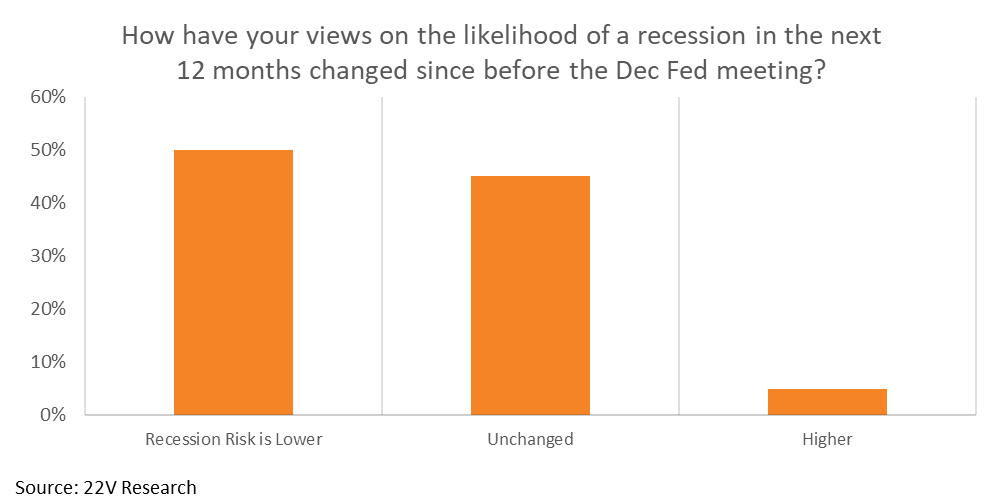
EQUITY IMPLICATIONS: The investors we polled this week are getting more optimistic about the economy too. Only 5% of respondents have raised their recession expectations relative to their baseline from before the December Fed meeting. Nearly 70% think real GDP growth will be in-line or beat expectations this year too. Our view is a turn in sentiment will help contribute to an internal rotation (along with data), bringing laggards more in-line with the economic Growth regime, like we saw yesterday.

Beyond catchups, lower recession risk will continue to benefit Cyclicals relative to Defensives longer-term. Within Cyclicals, Early Cyclicals (Tech, Comm Svcs, and Discretionary) that are less exposed to Size and Momentum, and Deep Cyclicals. And after a Value catchup, our favorite factor play is GARP. More details in the full report.
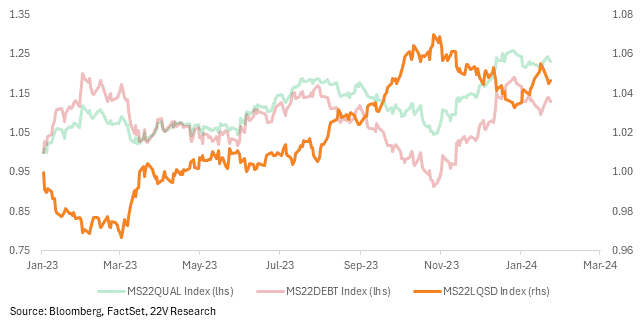
TWO MICRO THEMES: Lower recession risk and tighter spreads are a tailwind to lower debt rated names, which have gapped higher this week. Our swap that goes long companies with debt problems (MS22DEBT Index on bbg) relative to Quality (MS22QUAL Index on bbg) is a good rebound trade too. Longer-term, higher rates are a headwind to companies with deteriorating debt ratios, but tighter spreads and better data setup is supportive shorter-term.
Full report below…
MARKET VIEWS: 4Q23 GDP beat expectations yesterday, coming in at +3.3% ar vs 2% expected. Net exports and gov’t inflate the beat, but the underlying domestic demand conditions (the most important bits for the economic outlook) look solid. Final Sales to Private Domestic Purchasers grew +2.6% ar vs 2.5% expected, and personal spending grew 2.8% vs 2.5% expected. The bottom line is that growth is stronger than expected and considerably better than feared. Yields fell. Small caps outperformed large. Value and risk-on factors, two segments of the market that have lagged the economic backdrop the most, were yesterday’s best performers.
GDP BREAKDOWN: Peter has a longer-term take on the data, which is that recession risk is declining. “The economy keeps beating expectations, inflation has fallen, and the rate-sensitive and cyclical sectors did suffer serious drags. But the overall strength of the consumer, a general reluctance of firms to lay off workers after having such difficulty in re-staffing post-pandemic, robust nominal topline growth, and the asynchronized nature of many of the hits to activity means that the long-expected recession has not yet materialized… Having the same causal story running for strongly recession calls, or very elevated odds, seems a stretch; at some point the mechanism just isn’t working.”
EQUITY IMPLICATIONS: The investors we polled this week are getting more optimistic about the economy too. 50% of our survey respondents have lowered their recession expectations since pre-December Fed meeting. 45% of respondents’ views were unchanged. Only 5% of respondents believe the likelihood of a recession is higher. Nearly 70% think real GDP growth will be in-line or beat expectations this year too. Our view is a turn in sentiment will help contribute to an internal rotation (along with data), bringing laggards more in-line with the economic Growth regime, just like yesterday’s internals.
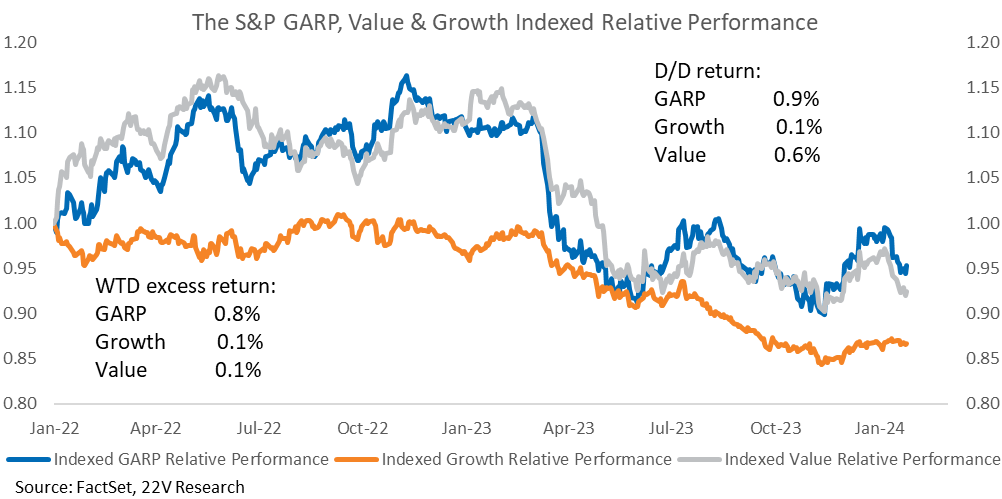
Beyond catchups, lower recession risk will continue to benefit Cyclicals relative to Defensives longer-term. Within Cyclicals, Early Cyclicals (Tech, Comm Svcs, Discretionary) that are less exposed to Size and Momentum, and Deep Cyclicals. And after a Value catchup, our favorite factor play is GARP. The Fed won’t let economic growth runaway, so some exposure to Growth along with Value makes sense. FYI, our formulation of GARP outperformed Growth ex-GARP and Value ex-GARP yesterday.
TWO MICRO THEMES: The spec and junk parts of the market have reversed some of the YTD trend this week. Lower recession risk and tighter spreads are a tailwind to lower rated names.
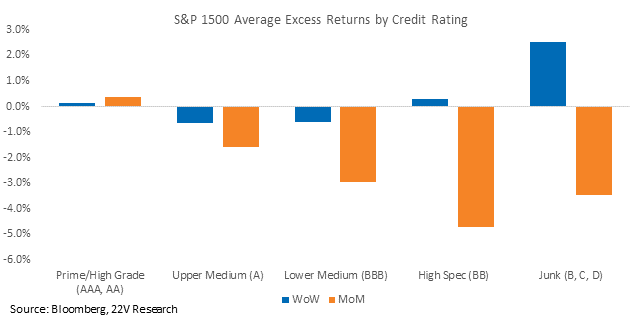
Our swap that goes long Quality and short Companies with Debt Problems (MS22LQSD Index on bbg) significantly outperformed in 2023. Companies with deteriorating debt ratios were a popular short as interest rates were climbing and recession risk was still elevated. These companies look ripe for a rebound if data continues to support our soft-landing base case. Longer-term, higher rates are a headwind, but tighter spreads and better data setup is supportive. Long companies with debt problems relative to Quality is a trade here.