Back Shoot Around

22V Afternoon Shoot Around: Stronger Economic Growth and Investor Expectations

Published on January 26, 2024

∙ Download the PDF Report

By

Dennis DeBusschere

Bottom Line: Economic growth is stronger than expected and considerably better than feared. That is an important support for a rebound in market laggards. Small caps outperformed large yesterday. Value and risk-on factors, segments that have most lagged the firming economic backdrop, were yesterday’s best performers.

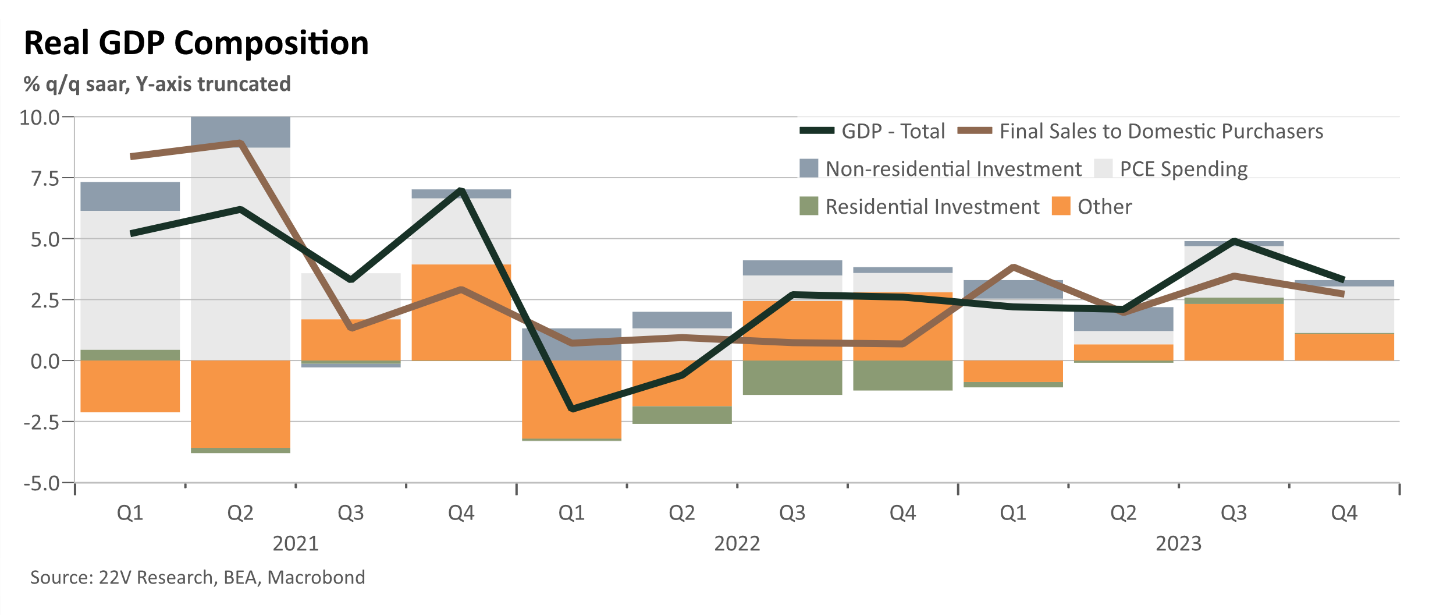
Relevant News: The GDP and December PCE were generally favorable. 4Q23 GDP beat expectations yesterday, coming in at +3.3% (ar) vs estimates of 2%. Core PCE came in right in line with target m/m and the y/y pace, at 2.9%, now has a 2-handle. Nominal wages and salaries growth has remained steady near-5% for much of the year, and spending growth continues to look healthy.

Things to Watch [consensus]: (1/30) JOLTs [8700K] (1/31) ECI [1.0% QoQ] & FOMC, (2/2) Payroll w/ revisions & AHE [180k, 0.3% MoM], (2/9) CPI Revisions, (2/13) CPI [3.4% YoY].

Economics: Post GDP and PCE Update

 22V’s economist longer-term take on the GDP release is that recession risk is declining. In his view the economy keeps beating expectations while inflation has fallen and the rate-sensitive/cyclical sectors have suffered serious drags. The overall strength of the consumer, reluctance of firms to lay off workers, robust nominal topline growth, and the asynchronized nature of many of the hits to economic activity means that the long-expected recession has not yet materialized.
A graph with different colored lines

Description automatically generated with medium confidence

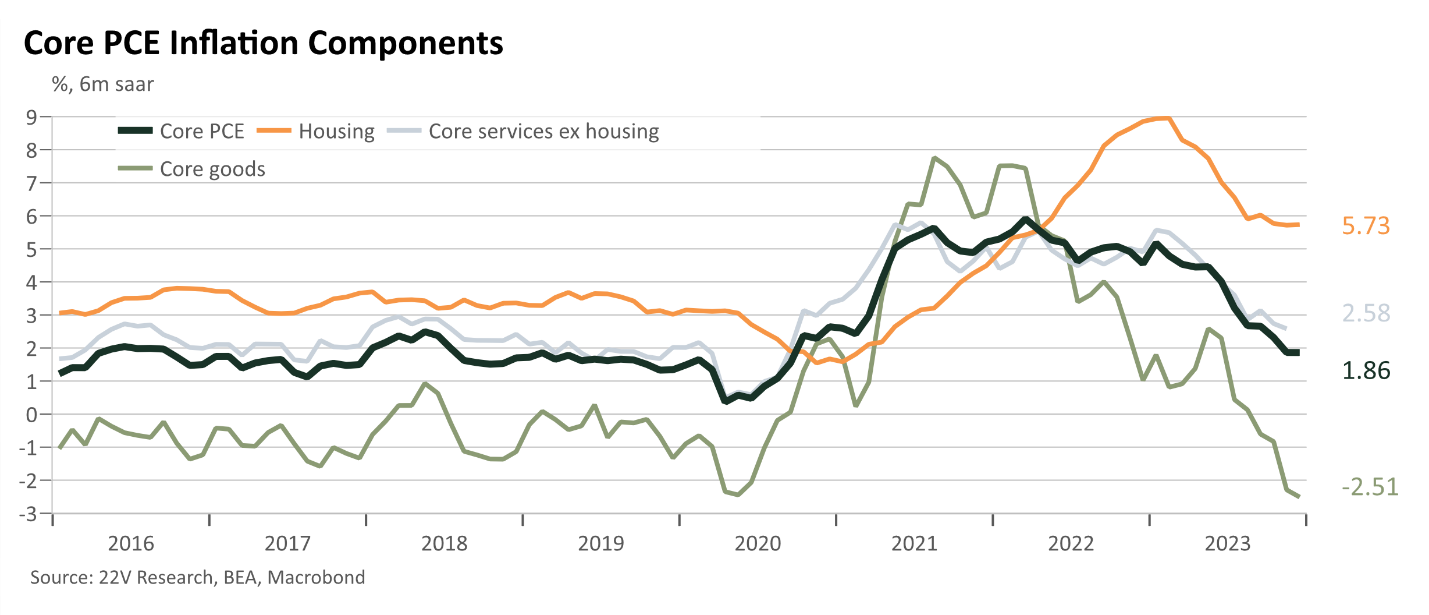
On PCE, core inflation has been around the target since June, with a 6-month annualized pace of 1.9%. in 22V’s economists view, the threshold for rate cuts has become somewhat lower. Core inflation stands at 2.3% over 9 months but remains high at 2.9% over 12 months.
A graph of a graph showing the growth of a company

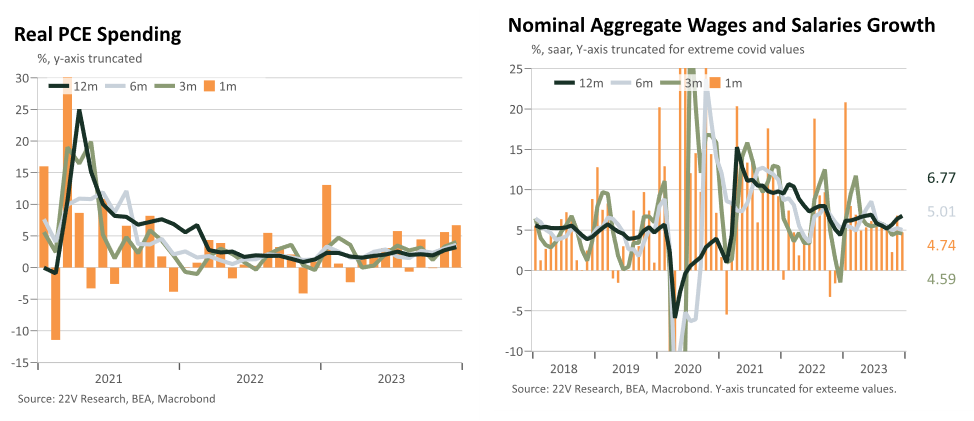
Description automatically generated with medium confidence For example, Food away from home, an indicator reflecting labor cost impact and discretionary spending, continues to exceed pre-COVID trends, signaling inflationary pressures. But nominal wages have held steady, similar to 2018-19 levels, suggesting compatibility with stable inflation. Real personal spending appears solid, with improvements in November and December, although seasonal factors post-COVID may affect monthly patterns.
A close-up of a graph

Description automatically generated

Portfolio Strategy: Economic Growth Survey Results

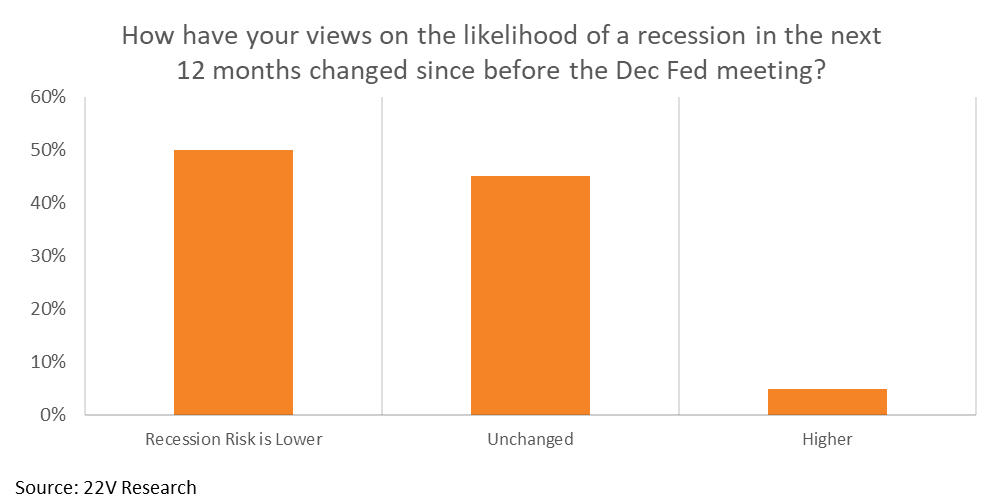
The investors we polled this week are getting more optimistic about the economy too. Only 5% of respondents have raised their recession expectations relative to their baseline from before the December Fed meeting. Nearly 70% think real GDP growth will be in-line or beat expectations this year too. Our view is a turn in sentiment will help contribute to an internal rotation (along with data), bringing laggards more in-line with the economic Growth regime, like we saw yesterday.A graph of a graph
Description automatically generated with medium confidence

Beyond catchups, lower recession risk will continue to benefit Cyclicals relative to Defensives longer-term. Within Cyclicals, Early Cyclicals (Tech, Comm Svcs, Discretionary) that are less exposed to Size and Momentum, and Deep Cyclicals stand to outperform. After a Value catchup, our favorite factor play is GARP. The Fed won’t let economic growth runaway, so some exposure to Growth along with Value makes sense. FYI, our formulation of GARP outperformed Growth ex-GARP and Value ex-GARP yesterday.

A graph of growth and value

Description automatically generated

Washington Policy: Considering How a Trump Victory Would Affect Markets

Considering how a re-elected President Trump would affect markets likely is only partly informed by his record in office and idiosyncratic statements. 22V’s Washinton policy team starts with a look at what can easily be erased of President Biden’s record. The balance of power in Congress is another determinative factor in imagining how a change at 1600 Pennsylvania Avenue might influence trading or investing narratives. Without unified government and a governing majority in the Senate, broad policy changes outside executive orders will be limited. With those thoughts in mind, we offer our first effort at a 2024 Trump basket for your consideration and possible denigration.
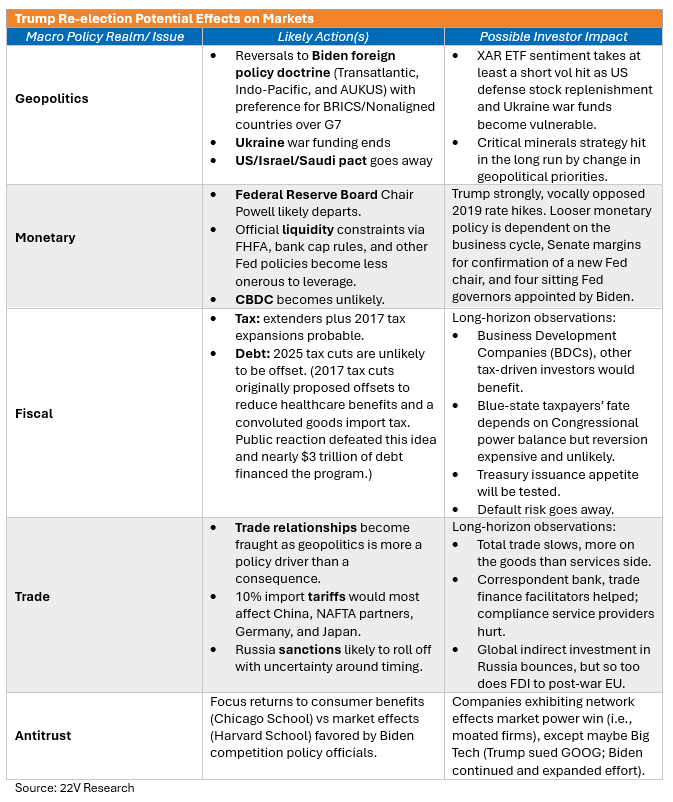
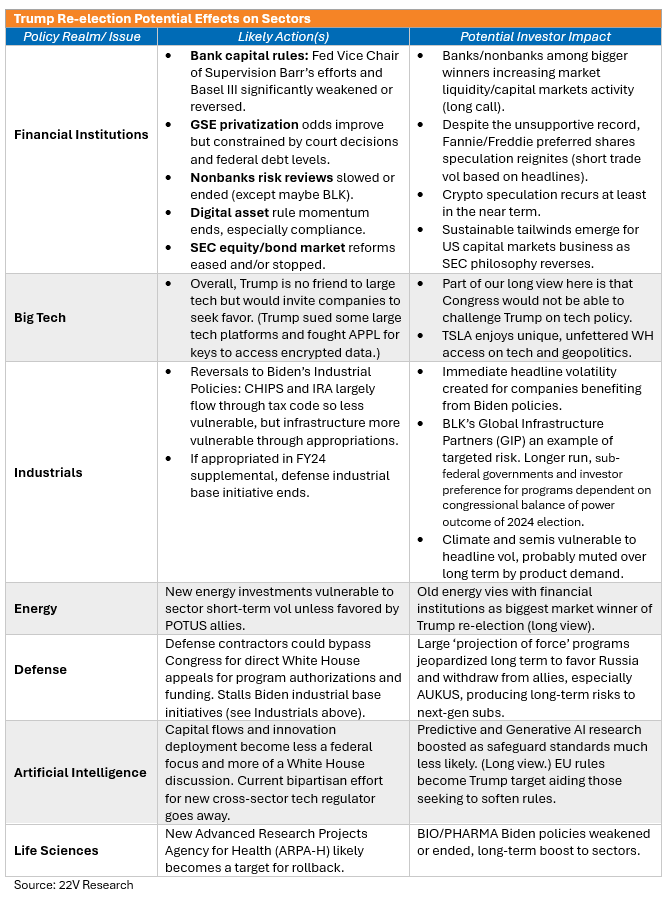
A white sheet with black text

Description automatically generated
A white and black document with text

Description automatically generated

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.