Equity markets started the year with a risk-off, large cap, Defensive rotation that was largely the reverse of trends coming out of 2Q23. At the same time, macro readings were firming, pointing to improved growth. And non-equity market conditions, credit in particular, were supportive of a continued risk-on rotation. The bottom line is market internals and macro trends have diverged broadly, macro conditions remain firm, and that creates a good setup for rebound in small cap/risk-on trades. Recently we have seen some reversal in the market internals narrowing the gap with macro series.
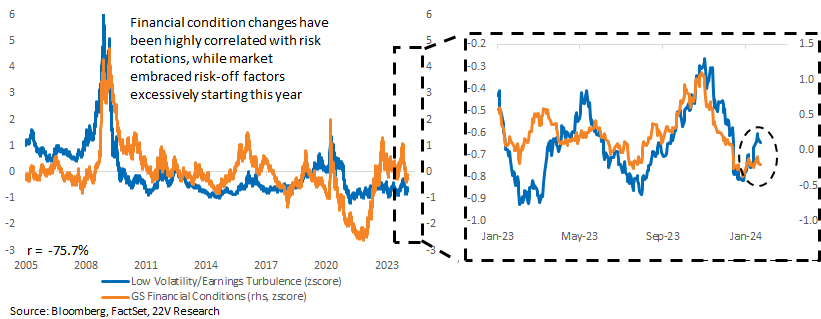
For factors, risk-on vs. risk-off performance has been highly correlated with financial conditions. Financial conditions have been roughly flat this year, while risk-off significantly outperformed. The outperformance of large relative to small caps have also diverged from their relationship with changes in high yield spreads.

At the same time, sector returns have diverged from yield curve trends. Curve re-steepening is a tailwind for Early Cyclicals and Financials, but defensives have led YTD. Timing a rotation is always difficult, but since late last week, Early Cyclicals outperformed, suggesting easing of the policy/growth fears that seem to have led to the early 2024 defensive rotation.
If near-term economic risks increased meaningfully, we would expect to see it show up in a broader set of macro data. What we have seen instead was a meaningful risk-off rotation without macro confirmation. 22V economists actually expect US GDP growth estimates will be revised higher to around 2% for this year. The divergence between market internals and the macro backdrop looks more likely to narrow in favor of market laggards.
Market Internal Starting to Narrow Their Divergence with Macro: Equity markets started the year with a risk-off, large cap, Defensives rotation even as the macro readings including inflation, payroll and retail sales were all stronger than expected. That led to a broad divergence between market internals and macro trends across factors, sectors, and stocks. For risk-on vs. risk-off performance, financial conditions this year have been roughly flat, while the relative performance of risk-off vs. risk-on (Low Volatility vs. Earnings Turbulence) has climbed sharply, leading to enlarged spread.
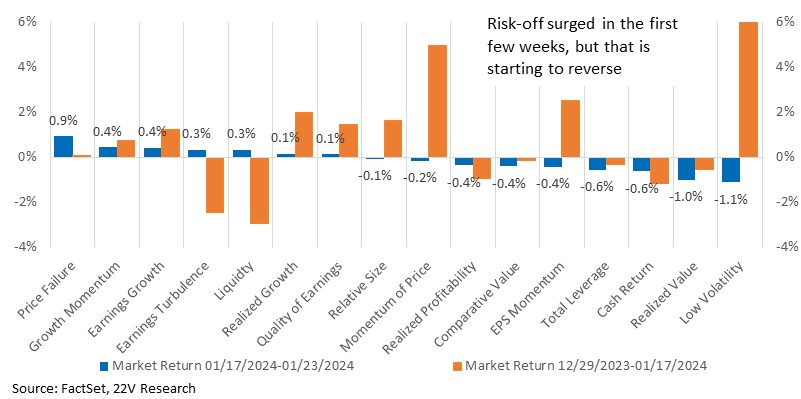
Over the past few days, we have seen sharp rotation internally between risk-on and risk-off factors with risk-on factors such as Liquidity and Earnings Turbulence rebounding from their earlier losses. Unless the Fed shifts its stance to favoring more tightening, a view that is not consistent with 22V’s economic outlook, the reversal of risk-on factors should be expected to continue.
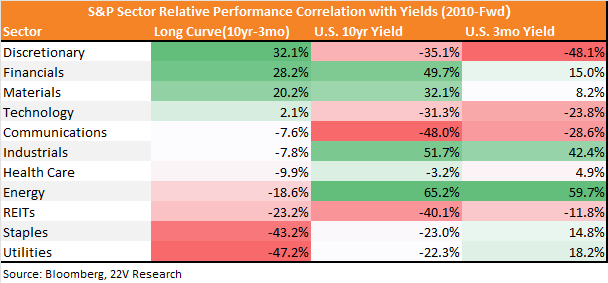
Sector return trends also diverged from their correlation with yields. The improved economic growth outlook has pushed 10yr yield higher this year and the curve has re-steepened. Early Cyclicals and Financials are most positively correlated/have the strongest betas to yields and the curve, but Defensive have led.
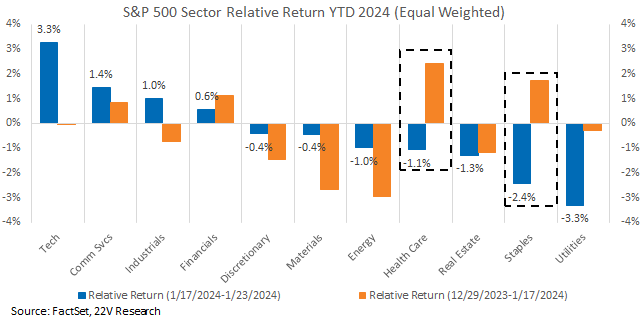
Health Care and Staples have been the best performing sectors YTD while Deep Cyclicals struggled. Some of that is tied to RoW concerns, which has eased some. A reversal of Defensive leadership started late last week with Early Cyclicals and Financials rebounding. Continued yield curve re-steepening along with risk-on reversal should support Early Cyclicals catching up.
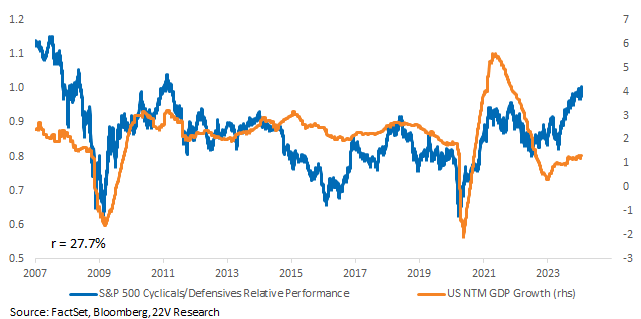
In addition to yield curve reversal, relative performance of S&P Cyclicals and Defensives have been positively correlated with economic growth. Consensus estimation for US GDP growth (NTM) have firmed recently, and we expect it to ~2% this year. That will also be a support for Cyclicals recovery relative to Defensives.
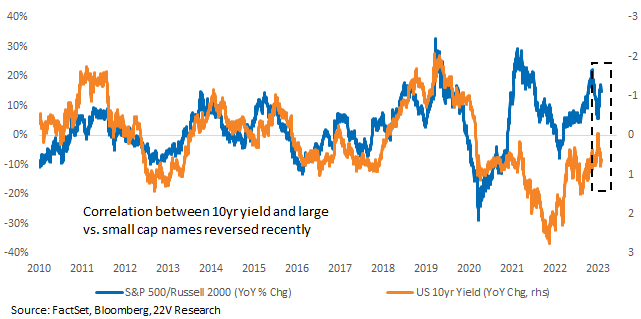
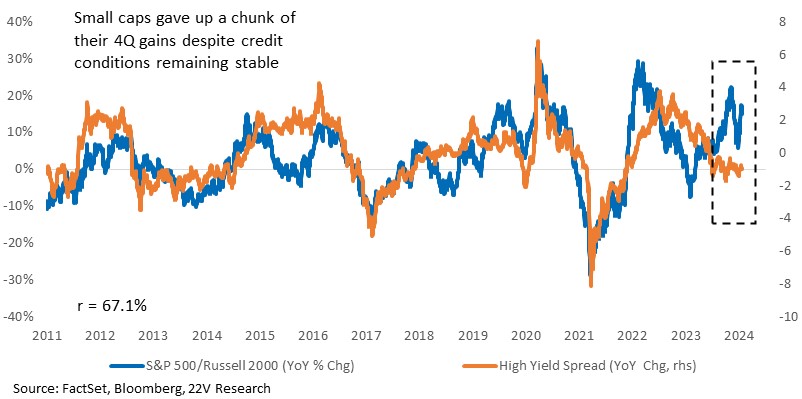
As we mentioned Monday, the divergence between mega cap Tech vs. Unprofitable Tech and high yield spread (HERE), large vs. small cap indices relative performance has also diverged from high yield spreads. Historically, S&P vs. Russell 2000 y/y change are strongly correlated with high yield spread changes. The latter is flat since 2H23, while large caps have largely continued to led. Along with factor and sector rotations, we expect to see the Russell 2000 Index rebound.
The indices relative performance with 10yr yield also diverged from their historical pattern, leading to higher spread between them. Some rebound from small cap names should be expected to narrow the spread between them.