Back Shoot Around

22V Afternoon Shoot Around: China Policy Move Easing RoW Concerns and Supporting Laggards

Published on January 24, 2024

∙ Download the PDF Report

By

Dennis DeBusschere

Bottom Line: Equity markets started the year with a risk-off, large cap, Defensive rotation that was largely the reverse of trends coming out of 4Q23. As a reminder coming out of 4Q23 macro readings were firming, pointing to improved growth. And non-equity market conditions, credit in particular, were supportive of a continued risk-on rotation. Fast forward to today, market internals and macro trends have diverged broadly, macro conditions remain firm, and that creates a good setup for rebound in small cap/risk-on trades. Recently we have seen some reversal in the market internals narrowing the gap with macro series.

Relevant News: The S&P US Composite PMI came in better than expected on the back of a beat by both the manufacturing and service components. 22V’s economist notes that the print seems consistent with the idea that we’re getting some better visibility for firms into 2024 amid a gradual troughing and potential bounce in firm sentiment.

Things to Watch: (1/25) GDP, (1/26) PCE, (1/31) ECI & FOMC, (2/2) Payroll, (2/9) CPI Revisions, (2/13) CPI.

China Strategy: Reserve Requirement Rate Cut Provides Short-Term Support for Markets

The People’s Bank of China (PBOC) announced a 0.5 percentage point cut in the reserve ratio for banks, with the largest banks now at 10%. Additionally, PBOC will reduce interest rates on targeted lending programs for small businesses, aiming to boost confidence after a weak start to the 2024 equity market. These moves are incremental support for growth, but they do not represent a shift in China’s stimulus strategy. The timing was expected, but the size of the cut was notable as the PBOC’s goal is to show active support for the economy and address the recent market sell-off. Beijing’s strategy focuses on supporting GDP growth but may not address underlying demand issues, potentially constraining Chinese equities amid deflation concerns.

Quant: Market Internal Starting to Narrow Their Divergence with Macro

Financial conditions have been roughly flat this year, while risk-off significantly outperformed. The outperformance of large caps relative to small caps have also diverged from their relationship with changes in high yield spreads.

A graph of a graph showing the growth of a stock market

Description automatically generated with medium confidence
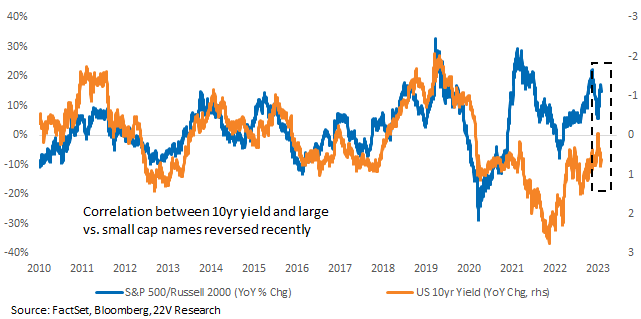
The indices’ relative performance with 10yr yield also diverged from their historical pattern, leading to higher spread between them. Some rebound from small cap names should be expected to narrow the spread between them.
A graph with blue and orange lines

Description automatically generated

Technical Analysis: Upside Gaps in the R2K/IWM

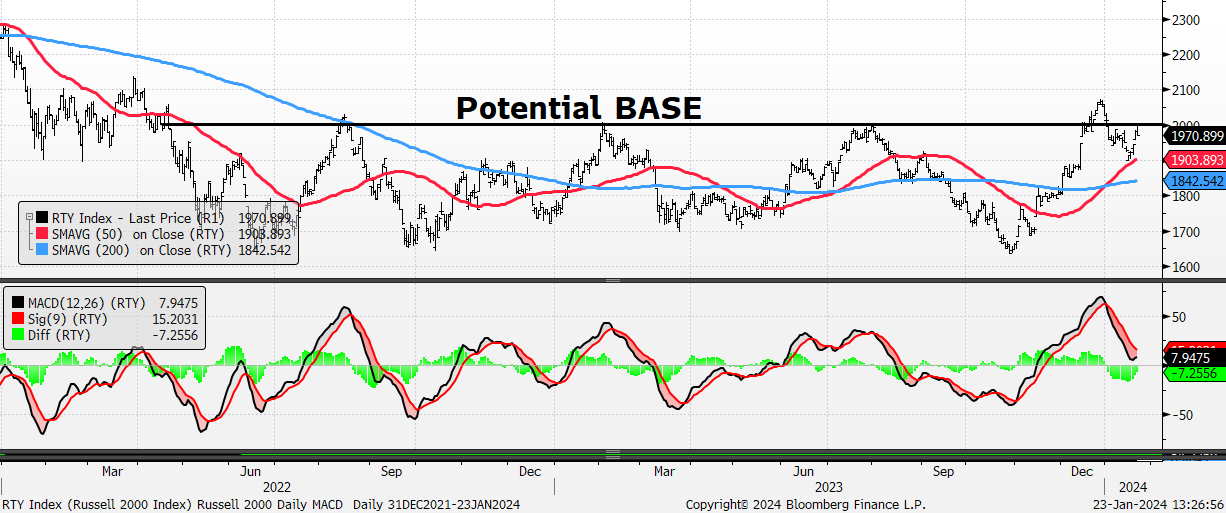
Since the 10/27/23 low the R2000 is up 21% with nearly all the gains occurring on 6 trading days that included 5 upside gaps. Check your daily charts to see the gaps on Nov 2 (+2.7%), Nov 3 (+2.7%), Nov 14 (5.4%), Dec 14 (2.7%), and Jan 22 (2%). Dec 13 was a non-gap day where the index added 3.5%. Upside gaps may be the way things are going to be for this index – 22V’s Technical analyst wants to own the IWM and wait for the next upside gap.

Russell 2000 – Daily w/ 50- and 200-Day MAs and MACD
A graph of a stock market

Description automatically generated with medium confidence

DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.