SUMMARY: There was a broad internal reversal yesterday. Small caps outperformed the S&P by +1.8%, a 99th percentile move. Momentum, Low Vol, EPS Momentum, and Realized Growth, the four best factors YTD, all fell yesterday. Earnings Turbulence and Liquidity, the two worst factors YTD, rallied. There was no clear macro catalyst for the reversal. But our survey work last week showed most of investors thought the market weakness in early January was a result of the overbought conditions coming out of 4Qs, which have been worked off some.
UPCOMING MACRO DATA: Peter Williams gave us bullet points ahead of GDP and inflation data this week. GDP is likely to be firm, and the bad news within inflation (that the market-based core is running above core), is a bit hawkish but not crucially so. Firm growth, net benign inflation, and a Fed more symmetric in its risk taking, is a good backdrop for small caps, risk-on, Value, etc.
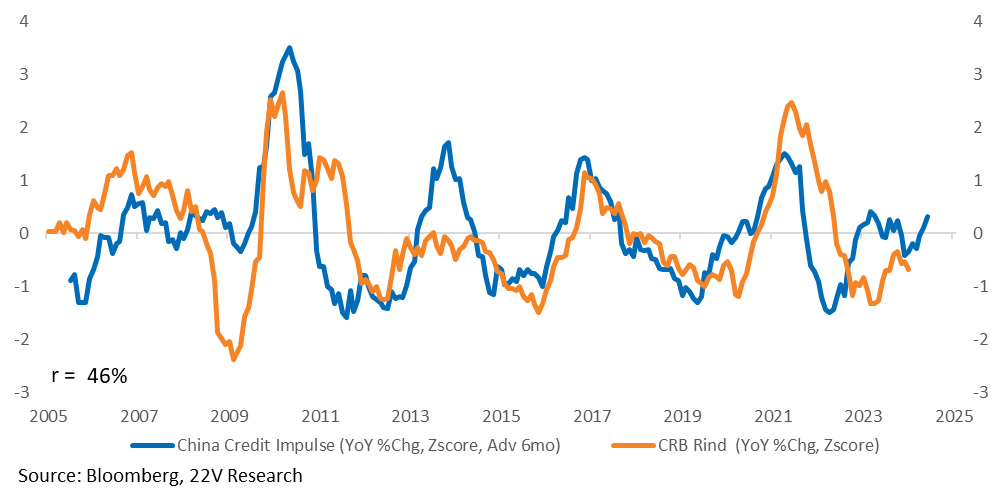
CHINA UPDATE: There is a lot of news about China reportedly considering a 2 trillion yuan ($278B USD) package to support equity markets (HERE). Michael Hirson, 22V China analyst, doesn’t view equity support as the same as broader macro stimulus. And he’s not convinced that the equity sell-off is enough of a financial stability concern to really shake up stimulus policies.
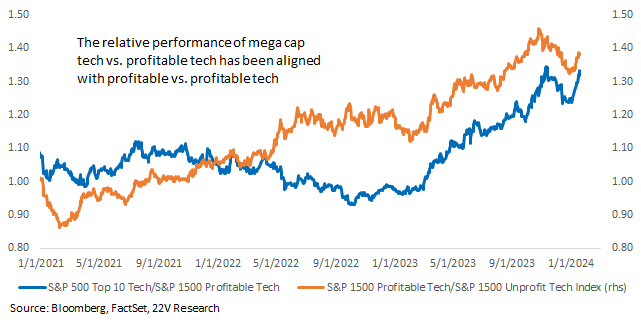
PROFITABLE TECH VS MEGAS: Yesterday, the quant team showed mega cap Tech has worked alongside risk-off factors (HERE). The group’s characteristics are not Defensive, but Mega caps rally when risk-off gains. The relative performances of the top 10 market cap Tech names vs. profitable tech surged this year as Low Vol/risk-off gained. An easing of growth and rate cut concerns would benefit profitable non-Mega cap Tech. Unprofitable Tech should benefit as well, but there is plenty of lower risk opportunity within profitable Tech during a risk-on reversal and Early Cyclicals can work broadly.

More details in the full report below…
MARKET VIEWS: Peter Williams gave us some bullets ahead of the GDP and inflation data this week. GDP is likely to be fairly strong, and the bad news within inflation (that the market-based core prices is running above core, potentially signaling inflationary pressure under the surface) is a bit hawkish but not crucially so. That data would be constructive for market laggards. Strong growth but net benign inflation, with a Fed that’s more symmetric in its risk taking, is a good backdrop for small caps, risk-on factors, Value, etc. FYI, the Russell outperformed the S&P by +1.8% yesterday. Still down on the year, but that’s a 99th percentile move.
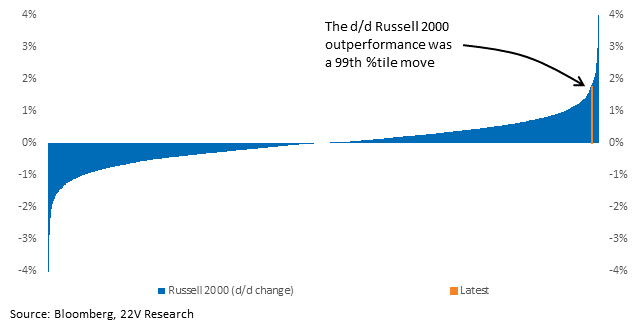
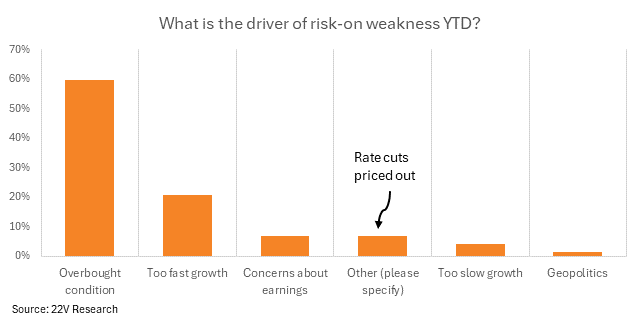
Momentum, Low Vol, EPS Momentum, and Realized Growth, the four best factors YTD, all fell yesterday, while Earnings Turbulence and Liquidity, the two worst factors, rose. There was no macro catalyst for a reversal. But our survey work last week indicated the majority of investors think the weakness to start the year was due to overbought conditions, which have been worked down over the past few weeks.
PROFITABLE TECH VS MEGAS: Yesterday we talked about Deep Cyclicals as a possible trade, with the catalyst being better-than-expected economic growth. The group is also levered to China’s disappointing growth prospects though, so a good GDP print Thursday may not be enough to set a new trend for the group. Today we focus on how Early Cyclicals (Tech, Comms Svcs in particular) can participate in a risk-on rally. The quant team highlighted how Size and Low Vol were correlated last year, driving mega cap performance. In other words, mega cap Tech worked in risk-off environments.
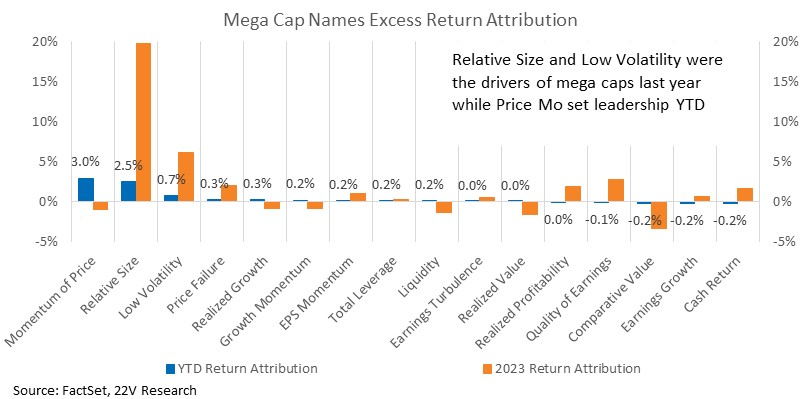
Early Cyclicals can still work in a risk-on trade on an equally-weighted basis. The relative performances of top 10 market cap Tech names vs. profitable tech surged this year. If concerns about growth and rate cuts ease profitable non-Mega cap Tech should benefit. Mega caps have great fundamental tailwinds. But the realized earnings growth exposure of megas has fallen. In other words, growth trends of other parts of the market are catching up. Right now, you don’t have to bet on unprofitable tech to take advantage of a risk-on trend. Early Cyclicals can work broadly.
CHINA UPDATE: China is reportedly considering a 2 trillion yuan ($278B USD) package to support equity markets (HERE). Michael Hirson, 22V China analyst, doesn’t view equity support as the same as broader macro stimulus. And he’s not convinced that the equity sell-off is enough of a financial stability concern to really shake up stimulus policies. This doesn’t look like a scene changer for the Deep Cyclicals levered to China.