Back Portfolio Strategy

Internal Rotations + Interesting Management Sentiment Setup into 2024

Published on November 30, 2023

∙ Download the PDF Report

By

Dennis DeBusschere

Brian Herlihy

Kevin Brocks

Sophia Wang

SUMMARY: We are wrapping up our Fed/EPS outlook survey today. You can take it HERE and results will be out this afternoon.

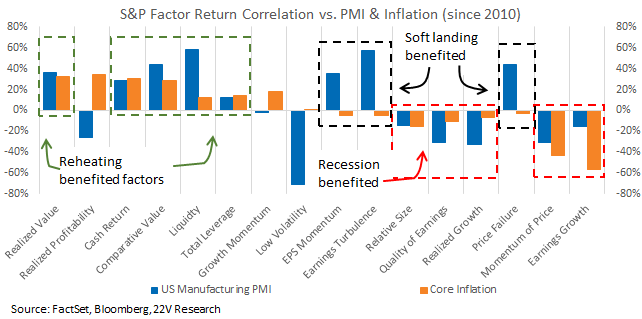
Fed officials have signaled a general level of comfort with the easing of financial conditions, and inflation appears to be slowing. All else equal, on a soft-landing path, inflation moves lower while PMI readings stabilize. That is good for Early Cyclicals and factors like Earnings Turbulence, EPS Momentum, and Price Failure that are negatively correlated with inflation readings and positively correlated with PMIs. That stance has generally worked, but internals have become more complicated.

Over the past few months, market internals have become less binary and risk-on/off rotations more nuanced. Increased return dispersion within sectors, industry groups, and factors should be expected given the high odds that we are back to a normal macro backdrop (more on how we define that HERE). It is important to keep micro forces specific to today’s backdrop in mind. The S&P has been flat over the past week, while higher debt risk names are up 80bps, IWM is up 1%, Destocking Reversal names are up 2.4%. Themes tied into broad macro trends remain our focus.

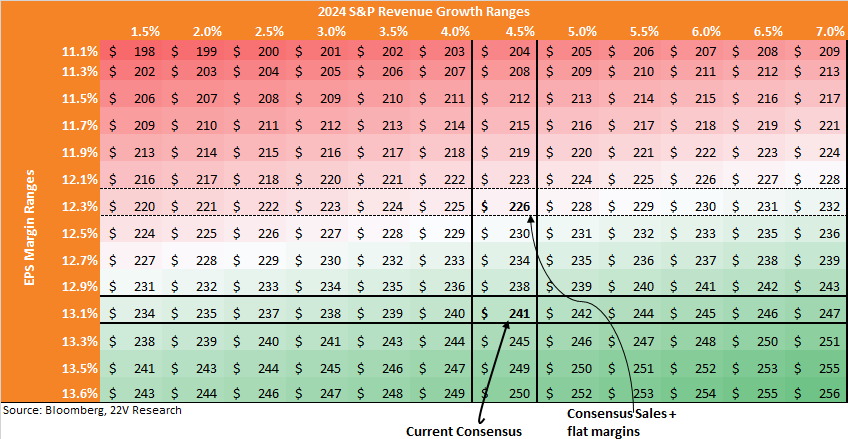
Pretty Good Fundamental Outlook for 2024: S&P sales are expected to rise 4.5% next year, which is a pretty low bar in a backdrop of +6% nominal GDP growth. If consensus margins and sales are correct, EPS would be +11% in 2024. As long as the Normal macro backdrop holds, the skew on revenue and EPS growth estimates is likely higher not lower.

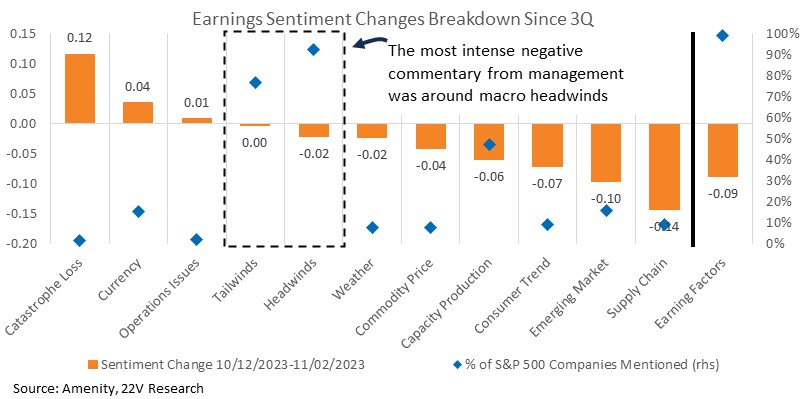
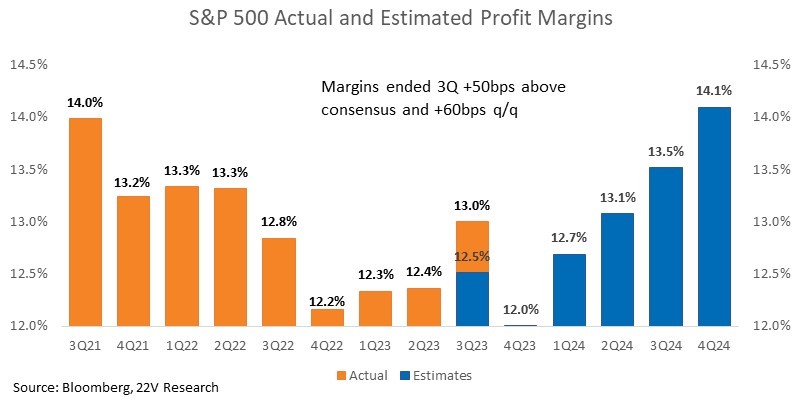
Earnings sentiment coming out of 3Q reporting season deteriorated. The most mentioned topic was macro headwinds/tailwinds, and both were mildly negative. That is an important point. The largest concerns about earnings were not around company data. Management was concerned about macro forces that might negatively impact performance. Sentiment toward margins INCREASED in 3Q, consistent with the 60bps increase in margins q/q.

A graph with blue and orange squares

Description automatically generated

We get it. Slowing growth and higher yields are a headwind for profit levels in 2024. But as go through in the report, even with flat margins and modest single digit revenue growth, S&P EPS would be up ~$10 (+4%) in 2024.

Full report below…

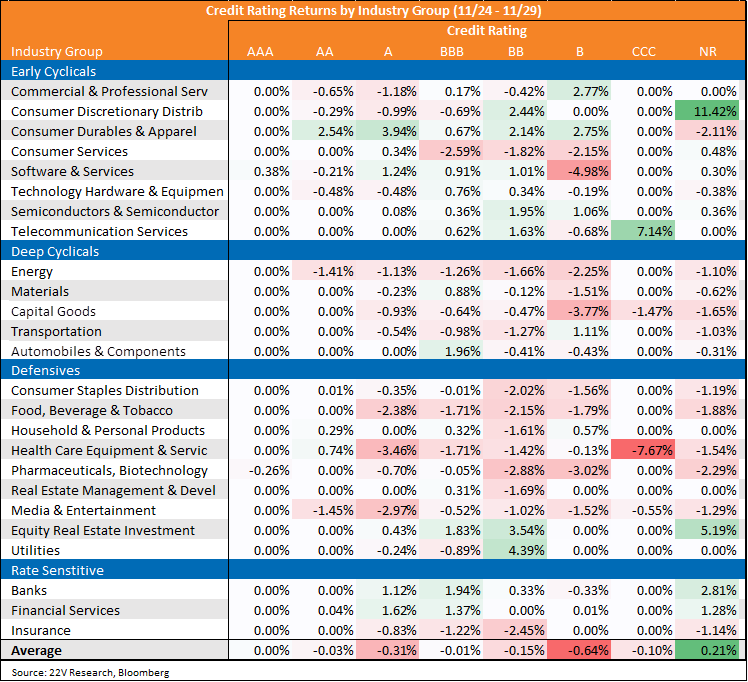
MARKET VIEWS: Market internals have become less binary over the past few months. Risk-on/off rotations have been more nuanced. Our high Debt Risk basket (MS22DEBT Index on bbg) lagged on Tuesday (-55bps relative) but rallied yesterday (+73bps relative). In general, companies with poorer credit ratings led internals during the early phases of the rally. More recently, returns to credit ratings have been more mixed. In general, Early Cyclicals with lower credit ratings have outperformed while poor credit Defensives have lagged.
A screenshot of a computer screen

Description automatically generated

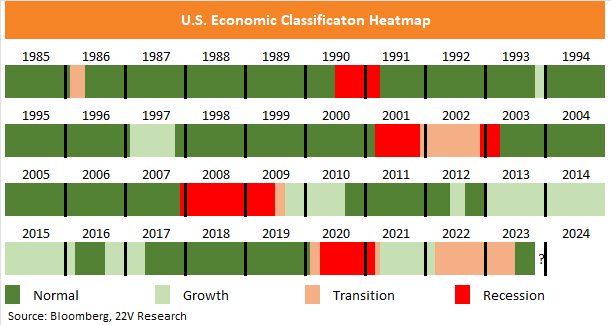
Increased return dispersion within sectors, industry groups, and factors should be expected given the high odds that we are back to a normal macro backdrop. The yield curve is inverted and rates are 525bps higher, but the level and vol of yields, inflation, payrolls, and PMIs are all more consistent with a Normal backdrop than a Transition or Recession backdrop.
A chart of heatmap

Description automatically generated

If we remain on a soft-landing path, inflation will move lower while PMI readings stabilize. Factors negatively correlated with inflation readings and more positively correlated with PMI changes would benefit, such as Earnings Turbulence, EPS Momentum, and Price Failure. Reheating of inflation would bring higher recession risk and would be a tailwind for Growth, Price Momentum, and Quality names.
A graph of different colored bars

Description automatically generated with medium confidence

Pretty Good Fundamental Outlook for 2024: S&P sales are expected to rise 4.5% next year, which is a pretty low bar in a backdrop of +6% nominal GDP growth. Revenue and EPS expectations imply profitability will expand almost a percentage point next year. If margins were flat y/y in 2024, 4.5% sales growth would still put S&P EPS up about 4% y/y. If consensus margins and sales are correct, EPS would be +11%. As long as the Normal macro backdrop holds, the skew on revenue and EPS growth estimates is likely higher not lower.
A chart with numbers and a graph

Description automatically generated

There has been a lot of concern about the weakening of earnings sentiment coming out of 3Q reporting. Weaker sentiment is a headwind for revisions and trends to lead actual changes in actual earnings. It is important to keep in mind WHY sentiment deteriorated. The most mentioned topics were macro headwinds/tailwinds, and both were mildly negative (change in level LHS, % of companies making comments RHS). That is an important point. The largest concerns about earnings were not around company data. Management was concerned about macro forces that might negatively impact performance.
A graph with blue and orange squares

Description automatically generated

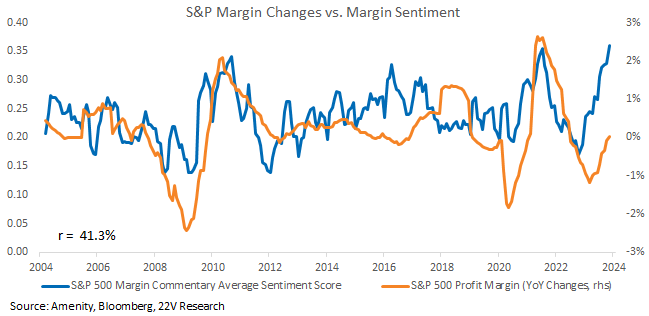
There was also an odd divergence between earnings sentiment and view on profitability. Management sentiment toward margins INCREASED in 3Q, continuing the upward trend it has been in for the past year. Margin sentiment gains were broad-based, rising across most sectors and industry groups, even as overall earnings sentiment deteriorated in 3Q. Historically, margin sentiment trends have been a good directional indicator for actual margins.
A graph of a graph showing the difference between the price and the price of the stock market

Description automatically generated with medium confidence

The improvement in margin sentiment lined up well with the inflection point in actual S&P margins over the past two years. Falling margin sentiment in late-’21 to ’22 predicted the decline in profitability. The improvement in margin sentiment in late-’22 lined up with the rebound in profitability seen over the past three quarters. We get it. Slowing growth and higher yields are a headwind for profit levels in 2024. But as we showed earlier, even flat margins next year would put S&P EPS up ~$10 in 2024.
DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.