On Thursday evening at 10pm ET, China will release the monthly activity data for August. This includes industrial production, retail sales, property data, and fixed asset investment. Below are some thoughts as to how I am approaching the data release.
In a note on Monday [link HERE], I observed that credit data, imports, and PMIs point to a tentative stabilization in manufacturing activity after a truly awful July [link HERE]. While service sector activity is decelerating from its torrid pace after the post-Covid reopening, signs of life in manufacturing would be important not only for global commodities but also for China’s struggling recovery to gain a broader base. The recovery this year has thus far been driven by services activity and infrastructure investment, leaving a large “missing middle” of private investment (particularly in property) and household consumption of goods. For economic growth, corporate earnings and sentiment to improve, that missing middle of private sector demand needs to start filling in.
On the household side, it will be important to see whether retail sales of goods (only 2.5% y/y growth in July) show consumers willing to make big ticket purchases of items such as appliances and autos. On the industrial side, infrastructure investment (6.8% y/y in July) may show signs of re-acceleration as local governments use up their quota of special bonds to finance projects by end-September. But property investment is likely to remain steeply contractionary, weighing down overall fixed asset investment (3.4% y/y in July).
The property sector is hugely important for China’s outlook, given its size and its influence on other areas such as fiscal spending (local governments depend on land sales revenue) and consumption. August data will provide only a partial barometer: the central and local governments have rolled out a slew of easing measures since late August which won’t show up in the monthly data. High frequency data from September thus far suggest that easing measures have spurred an initial increase in buying interest in the tier 1 cities (Beijing, Shanghai, Shenzhen, Guangzhou) but it isn’t clear if this will last. The outlook for the national market remains dim. Most tier 2, tier 3 and tier 4 cities have already loosened policy since 2022 and have worse fundamentals (slowing/falling population growth and high housing inventory) than the largest markets.
Heading into this data release, my views on the economic outlook are as follows:
- As incremental stimulus takes effect and China gains further distance from the zero-Covid era, growth is likely to stabilize but potentially at a low level. This should at least ease some of the extreme pessimism towards China, particularly the notion that the economy is at high risk of crisis or hard landing – which it is not.
- Until evidence suggests otherwise, I continue to be skeptical about a strong recovery – and to worry about the danger of anemic growth continuing into an extended period of malaise (weak demand and confidence, weak recovery in corporate profits). The main reason is that the prolonged property downturn and fragile expectations continue to exert a powerful drag on the economy, and macro policy may still be too restrained to deliver the strong countercyclical punch necessary to overcome these dynamics.
- The most direct path to an improvement in China sentiment would be signals from the leadership that it will do “whatever it takes” to boost growth. The main measures that would constitute a “whatever it takes” policy would be stronger financial support for private property developers and/or expansion of the fiscal deficit, along with a clear commitment from the leadership, which would likely need come from Xi Jinping to be fully credible. I doubt that such a “Draghi moment” is coming, which means that a boost in sentiment will have to come more gradually and organically, with evidence that incremental stimulus and the slow recovery from zero-Covid are enough to stabilize growth and earnings. August data will not be conclusive in this regard, but a signpost along the way.
With that backdrop, I am inclined to view the potential market implications of August data as follows:
- Relatively good data – signs that demand is stabilizing after a dreadful summer – should be at least modestly reassuring for markets. To be clear, I’m not expecting euphoria or an all-clear signal that the recovery is on solid footing, but it would at least suggest that the risk of further deterioration is falling and that incremental stimulus is having some effect. Given the moderate degree of stimulus coming from Beijing, I doubt that the data will be good enough to be “bad” – that is, to convince Beijing to dial back the targeted stimulus measures in the pipeline.
- Relatively bad data – few signs of improvement, but no further slide in momentum – will be negative for investors, though price action could be limited given how much pessimism is already priced in. At the same time, it should be regarded as an incomplete signal given that August data will not reflect the impact (if it materializes) of recent property measures. Further, the acceleration in infrastructure investment, as local government use up their annual bond quota, may show up more in September and October data than August. I think it would take a very bad set of data to become “good” in the sense of triggering more forceful stimulus policies and a “Draghi moment.”
EU investigation in China EVs unlikely to lead to tariff war but tells a broader macro story
On Wednesday, European Commission President Ursula von der Leyen announced an investigation into China’s subsidies for electric vehicles. This comes with China likely to finish 2023 as the world’s largest auto exporting country, a remarkable performance over the last few years. China’s EV market share in Europe remains low but is growing quickly and looks to be only gaining steam.

The EU move is potentially risky given that a decision to impose tariffs or other restrictions could lead China to retaliate and limit access in a key market for European, especially German, auto makers. China’s Ministry of Commerce called the investigation “a naked protectionist act that will seriously disrupt and distort the global automotive industry and supply chain, including the EU, and will have a negative impact on China-EU economic and trade relations.”
However, there are reasons to be skeptical about the prospect of a tariff war. Beyond the risk of retaliation, 22V’s head of Europe research, Jacob Kirkegaard, notes the political context: von der Leyen’s move was likely intended in part to secure support from France (which cheered the investigation) for her pursuit of a second term in office. He adds that it may be difficult for the EU’s investigation to show direct harm to EU auto makers, as required for anti-dumping actions, given that many of China’s subsidies to its EV industry are indirect and come from local governments.
There are options beyond tariffs, notes Jacob. The EU will for instance introduce new EV battery recycling legislation that takes into consideration whether the battery is produced with clean or coal-based power. In China it is often the latter, which could make recycling rules much harder for Chinese EVs and incentivize Chinese producers to move production to the EU. The EU could try to convince Beijing to adopt some form of voluntary export restrictions, and/or could opt for more state support to its own firms.
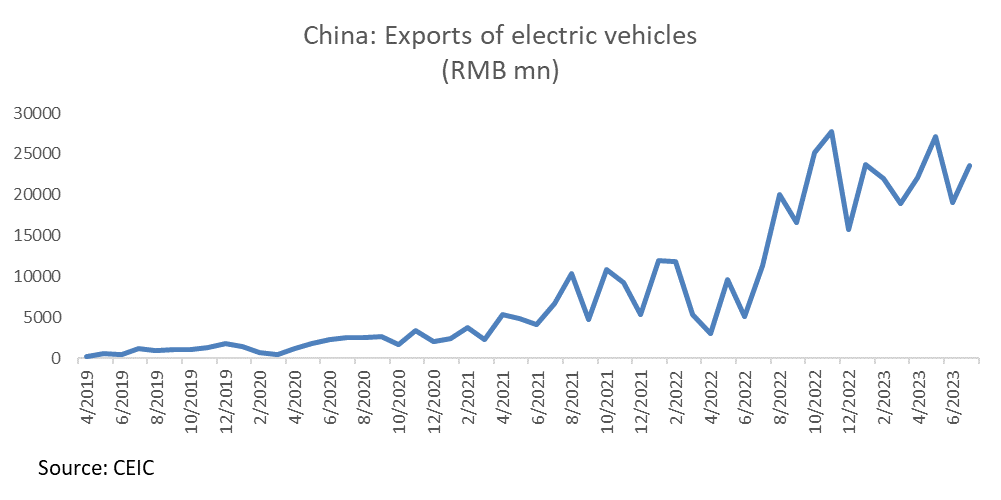
There is a broader macro story involved here that relates to China’s growth strategy and its impact on global growth and trade frictions. Xi Jinping has set China on a course to move past “old growth drivers”, particularly property, to new growth drivers, which center on strategically important areas of advanced manufacturing and in particular all aspects of clean tech. China has seen a continued surge of state and private capital into EVs, batteries, and solar (among other fields), such that all three sectors are at risk of at least temporary overcapacity. The fact that China’s domestic demand remains subdued – since these new growth drivers are not large enough to offset the lost demand from property, and Beijing is keeping stimulus restrained – further heightens the inclination of Chinese firms to use exports as an outlet.
This pattern could well extend into the medium term and create major headaches for China’s advanced economy trading partners – particularly Germany, Japan, and South Korea, for whom manufactured exports to China are economically important. They face the combination of subdued demand in China, growing import substitution as China expands into high value-added sectors, and the potential for overcapacity that hurts global prices and margins in third country markets as well. This threat exists not only in clean tech but sectors such as mature semiconductors.
These dynamics will play out in different ways by sector and by trading partner. In solar, for example, Jacob notes that Chinese firms have already established an overwhelming cost advantage over European producers; rather than try to challenge China’s dominance, Europe will take advantage of the affordability of China’s solar products to accelerate energy independence. Wind is another story, with EU firms more competitive than in the solar sector and a focus of European industrial policy.
Some of the same policy deliberations exist for the US, such as how much to exclude imports of Chinese solar materials. But relative to Europe, the US has a greater willingness to finance alternatives to Chinese imports through the Inflation Reduction Act, higher tariffs on many Chinese products as a holdover of Trump’s trade war, and also more geopolitical zeal in not becoming dependent on Chinese supply chains. While Washington’s rediscovery of industrial policy has been a source of concern and frustration for long-time allies, their anxiety over China’s ramped up investment and exports in high-tech goods will be an advantage for the US in seeking formal and informal pacts countering Beijing – a trend that 22V’s head of Washington Research Kim Wallace noted in a recent in-depth look at reglobalization [link HERE].
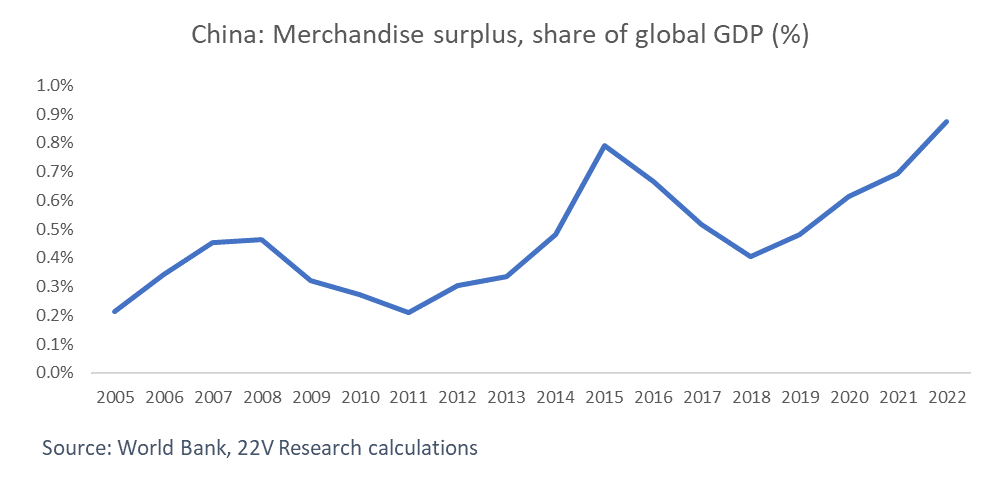
From the standpoint of global growth, China’s merchandise surplus is already at record highs as a share of global GDP (see chart). A medium-term outlook in which China’s property downturn drags on and Beijing offsets it with only modest stimulus means this pattern of a large Chinese external surplus could well continue, limiting the contribution of Chinese demand to the rest of the world and potentially spurring new rounds of trade frictions. Watch this space for more.