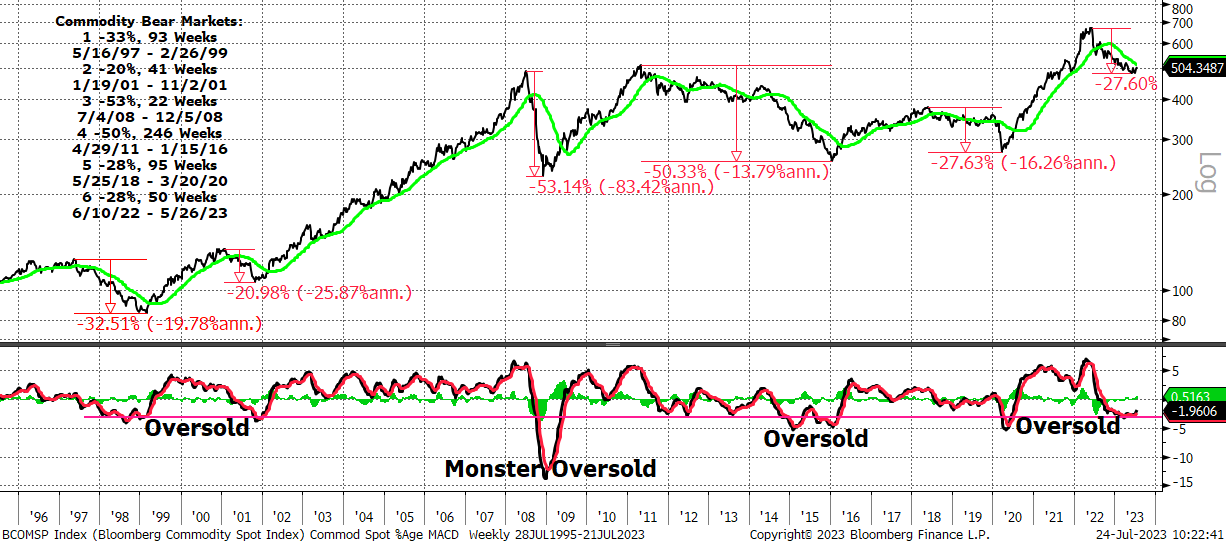
SUMMARY: The Chinese Politburo meeting came earlier than expected this year with no huge surprises. The tone is a bit more constructive than Michael Hirson, 22V’s China analyst, expected, but still in the vein of implying mostly targeted measures and no big new stimulus announcements (HERE). Michael was in China last week, and the view from his contacts is that much bolder measures are necessary but not forthcoming. Short-term, if the dovish narrative takes hold, commodities could get a boost. That is a theme John Roque thinks is worth a look now (more HERE). Longer-term, the dovish narrative will probably disappoint.
RISK-ON vs. RISK-OFF TIMING: The macro environment is different than pre-Jackson Hole last year (when Powell ditched his prepared remarks and delivered a grumpy 12-minute speech on why financial conditions were going to tighten, full stop). The Fed has a chance at a soft landing, and they are likely to go for it. We favor risk-on factors longer-term.
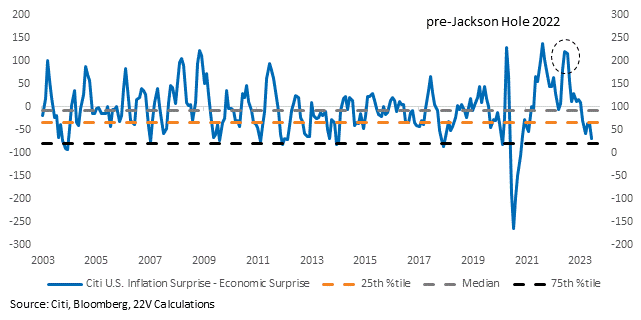
Our macro regime classification model demonstrates how much closer macro data is to a ‘Normal’ period than it was back in 2022 pre and post Jackson Hole. And at that point, inflation kept surprising to the upside, and growth indicators did not, leaving a wide spread between the Citi inflation and economic surprise indices, and extreme pessimism post Powell. The opposite is the case now, which is one of the reasons risk-on factors are more attractive today.

Into the Fed meeting though, we are concerned about a risk-off reversal trade. Given the above, we don’t expect Powell to ditch data dependence or reset fed funds futures higher, his tone about the recent easing of financial conditions is a risk. To be clear, this week won’t be another Jackson Hole moment, but the recent easing of financial conditions makes us wary of mean reversion around the meeting.
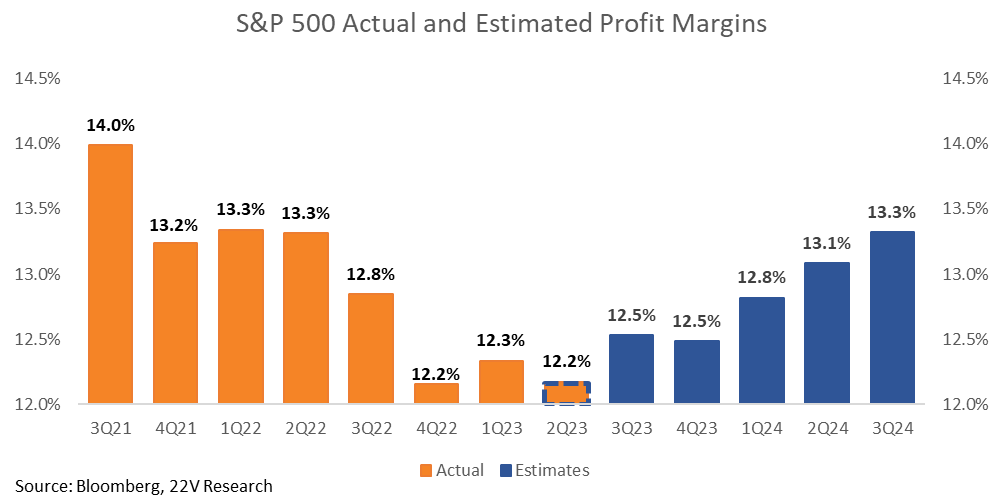
Multiples have expanded to ~20x, up 2 points in the past quarter. Higher multiples would not be a problem if NTM earnings growth expectations were set to jump higher. Revenue growth is forecast to remain slow next year, but low teens EPS growth is expected, largely as a function of margin expansion. That is possible if costs fall quickly enough (wage growth is hard to explain with other data and could fall). The risk is that slowing growth and lower inflation are generally associated with lower profitability. The burden of proof will be on arguing for higher profits in that backdrop.
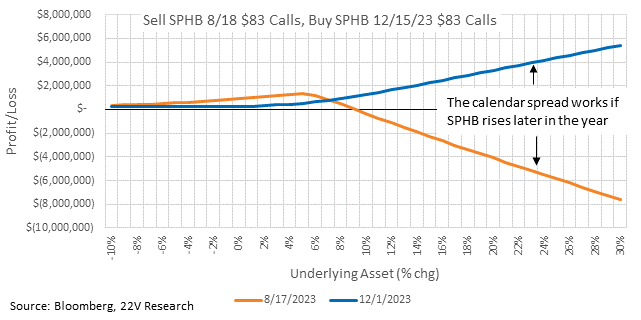
We mock up an options trade to illustrate how we would position ourselves right now, details of which are in the full report below.
MARKET VIEWS: The Chinese Politburo meeting came earlier than expected this year with no huge surprises. The tone is a bit more constructive than Michael Hirson, 22V’s China analyst, expected, but still in the vein of implying mostly targeted measures and no big new stimulus announcements (HERE). Michael was in China last week, and the view from his contacts is that much bolder measures are necessary but not forthcoming because of 1) Beijing’s attention to financial risks 2) determination to stay the course on reshaping the property sector, and 3) some degree of dysfunctional policymaking. Short-term, if the dovish narrative takes hold, commodities could get a boost. That’s a theme John Roque thinks is worth a look now (more HERE). Longer-term, the dovish narrative will probably disappoint.
RISK-ON vs RISK-OFF TIMING: We favor risk-on factors longer-term. The macro environment is different than pre-Jackson Hole last year (when Powell ditched his prepared remarks and delivered a grumpy 12-minute speech on why financial conditions were going to tighten full stop). The Fed has a chance at a soft landing, and they are likely to go for it. Our macro regime classification model demonstrates how much closer macro data is to a ‘Normal’ period today than back in 2022 pre and post Jackson Hole.
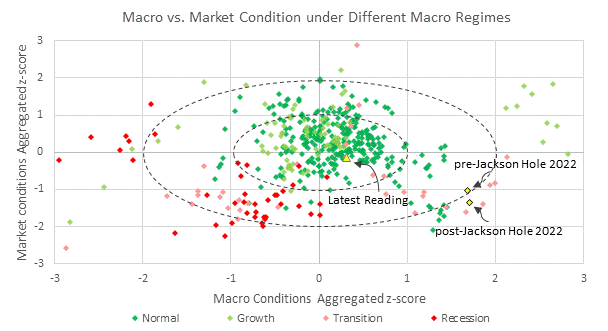
Source: FactSet, Bloomberg, 22V Research
The chart above illustrates how unique August 2022 was. At that point, inflation kept surprising to the upside, and growth indicators did not, leading to a wide spread between the Citi inflation and economic surprise indices, and extreme pessimism post Powell. The opposite is the case now, which is one of the reasons we favor Cyclicals and risk-on factors longer-term.
Plus, the fed funds futures curve is already higher for longer compared to pre-Jackson Hole 2022.
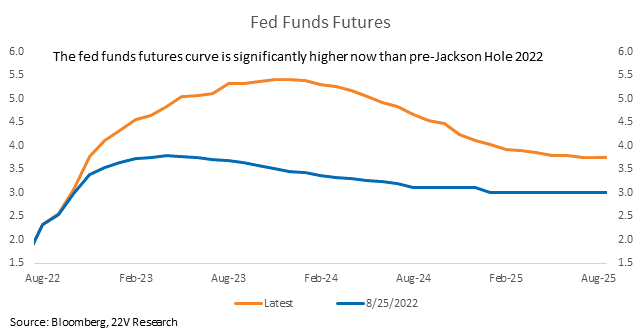
With that overall framework in place, we are concerned about a risk-off reversal trade around the FOMC meeting. The Fed this week has the chance to be risk-off because heading into the event, financial conditions have probably eased a bit too much, multiples are high, and implied volatility is low. We don’t expect Powell to ditch data dependence or reset fed funds futures higher, given the above, but there is a risk to how he sounds about the recent easing of financial conditions. To be clear, this week won’t be another Jackson Hole moment, but easy financial conditions make us a little wary of a pullback trade.
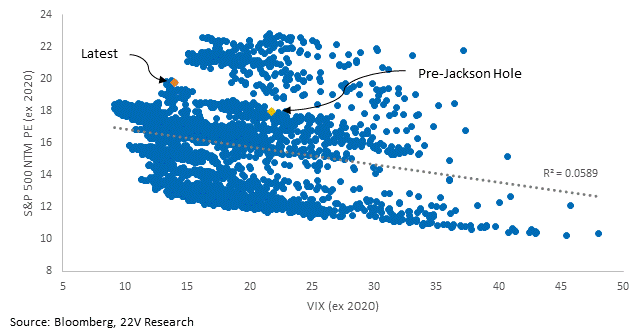
High multiples would not be a problem if earnings growth expectations for the next 12 months were set to jump higher. Revenue growth is forecast to remain slow next year, but low teens EPS growth is expected, largely as a function of margin expansion. That is possible if costs fall quickly enough (wage growth is unusually high and could fall). The risk is that slowing growth and lower inflation are generally associated with lower profitability. The burden of proof will be on arguing for that profitability will expand in that backdrop.
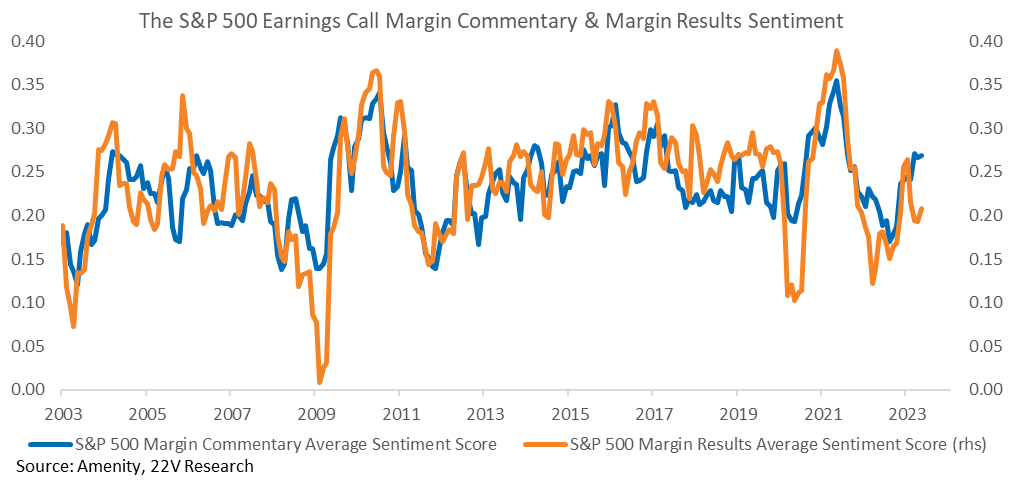
Margin sentiment, forward-looking and current focused, has stalled recently. How management sentiment toward profitability evolves will help us understand the odds of margins meeting expectations. We will be monitoring this metric throughout earnings season.
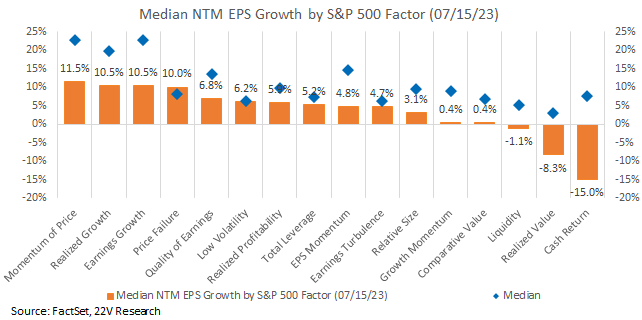
FYI, earnings reporting season is a tailwind to risk-on factors, given eps growth by factor (charted below) but if Powell comes out sounding hawkish, it will supersede the risk-on earnings story. At least short term. Macro influence is still high, even though implied volatility is low. So that’s why we are concerned about a short, risk-off mean reversion trade. This is not a long-term call.
If we were to express our views via a trade, we would sell SPHB 8/18 $83 calls and buy SPHB 12/15 $83 calls. SPHB is a high beta etf that is a good proxy for risk-on internals. It has plenty of liquidity. 7000×2700 makes the trade vega neutral and self-funding.