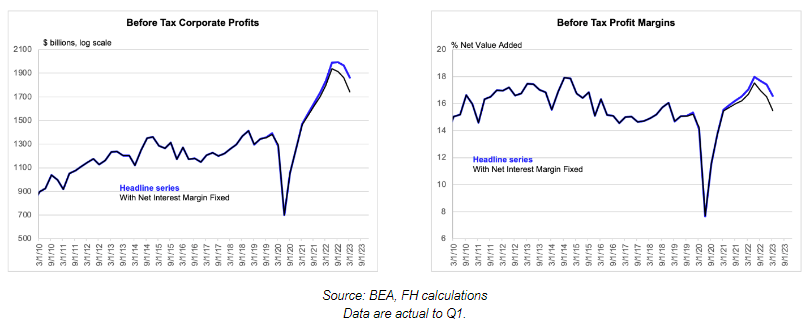
SUMMARY: The risk/reward skew on the S&P and Cyclicals in general is less exciting. We laid out some of the reasons yesterday (HERE): the market is at the high end of our fair value range, and Cyclicals have had a 99th percentile m/m move in a mean-reverting backdrop. Over the past year, we have been arguing that recession risk is farther out than investors thought, keeping us constructive on the market and internals. As Gerard argued this week, corporate profitability (at the economy level) is falling (HERE). That will encourage further loosening of the labor market, which has already started. Wage growth has rolled over, quits are declining, payroll growth has slowed, and hours worked have declined. They are all fine in level terms, but with underlying economic demand running at roughly 1% and broad margins declining, expect the labor market loosening to accelerate. That will reinforce near-term disinflationary themes. It will continue to favor Quality and we should expect Low Vol names to stabilize.
Our tone change may be a bit early. Labor data on Friday will help inform that, and the data could very well be strong. BUT you don’t want to be late positioning for deteriorating labor data. Maybe the data Friday is fine, but the urate is due to increase as profitability falls. Increases in unemployment tend not to be orderly, re-introducing equity volatility. FYI, we still think the odds of a soft landing are 50/50, but fighting the soft-landing battle as the labor market loosens is not worth it. IF it is proven over time that wages/core inflation can decline WITHOUT a step fall in overall economic activity (it will take a number of months to figure that out), a soft landing will become more obvious as the Fed signals they can move back to a more neutral policy stance.

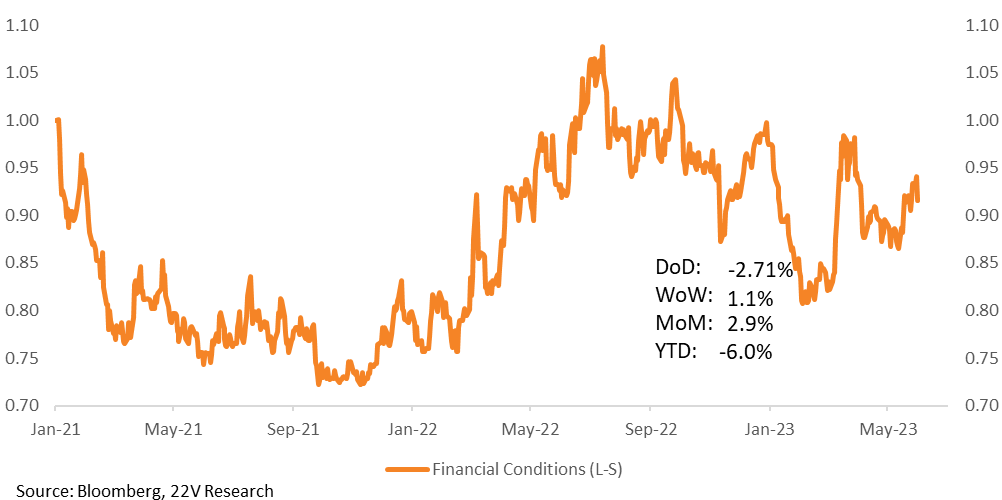
POSITIONING FOR TIGHTER FINANCIAL CONDITIONS: Financial conditions will tighten as the labor market loosens, even if the Fed pauses (which we expect). Volatility should increase and credit spreads widen as the urate climbs.
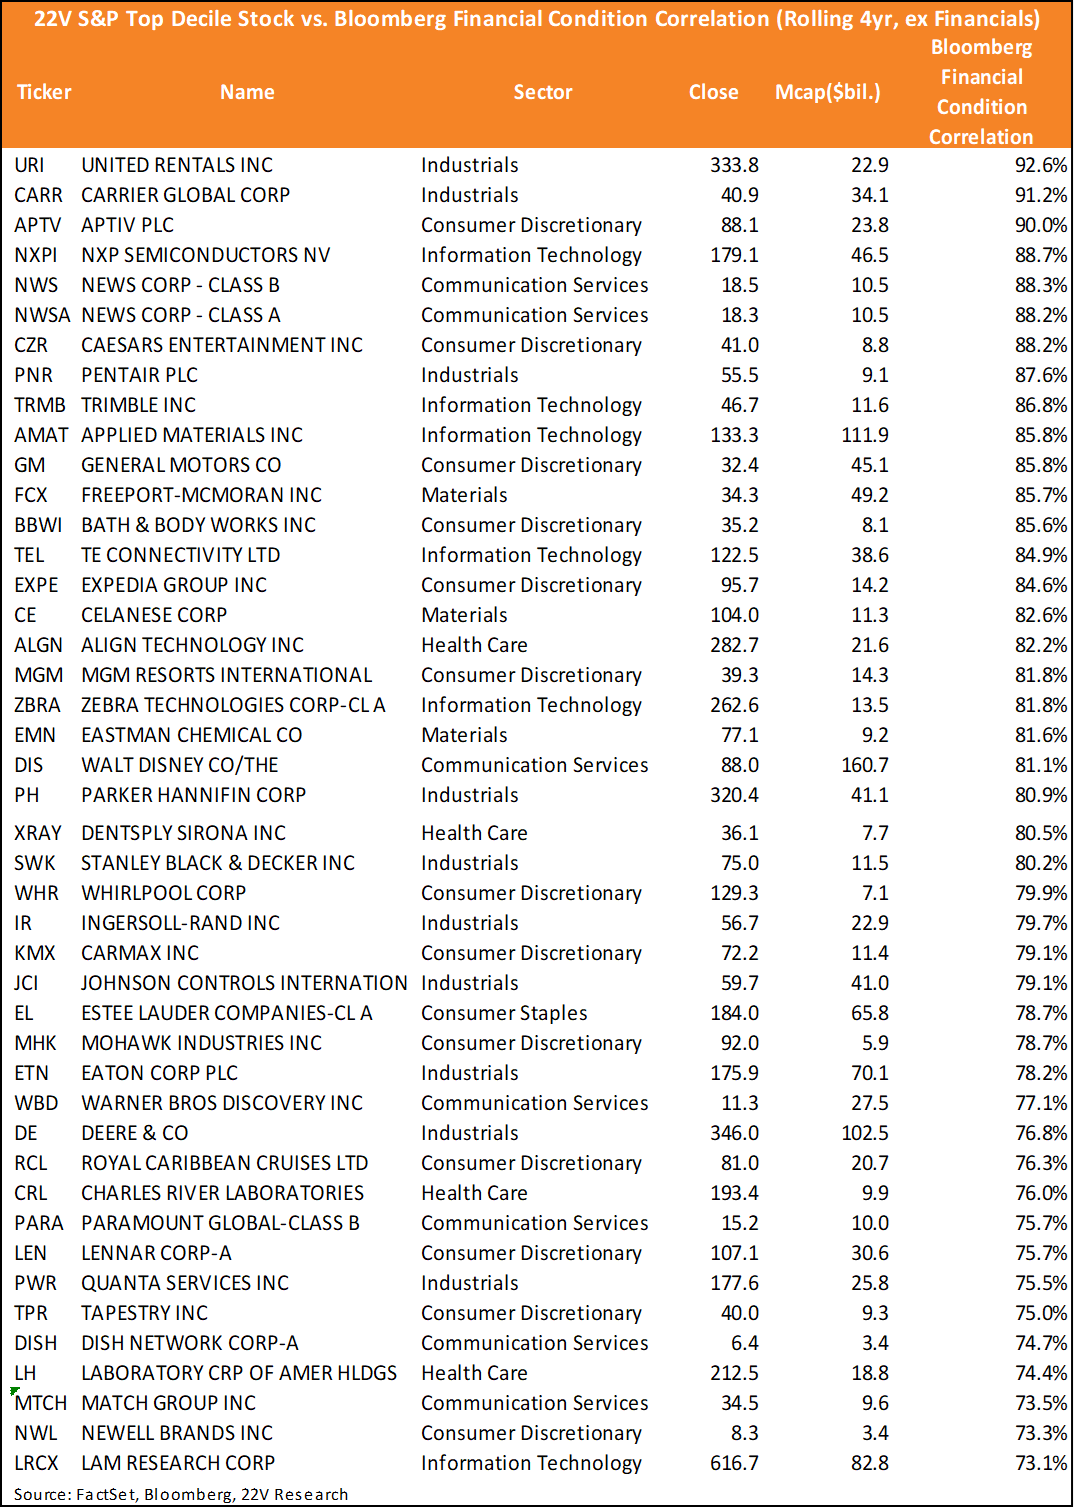
We have a long-short portfolio designed to track changes in FCI. Constituents (ex-Banks, which remain un-investable right now) are at the end of the report. Go long the stocks that benefit from tighter conditions and short stocks that benefit from easier conditions. Again, we want to get ahead of a potential blowup.
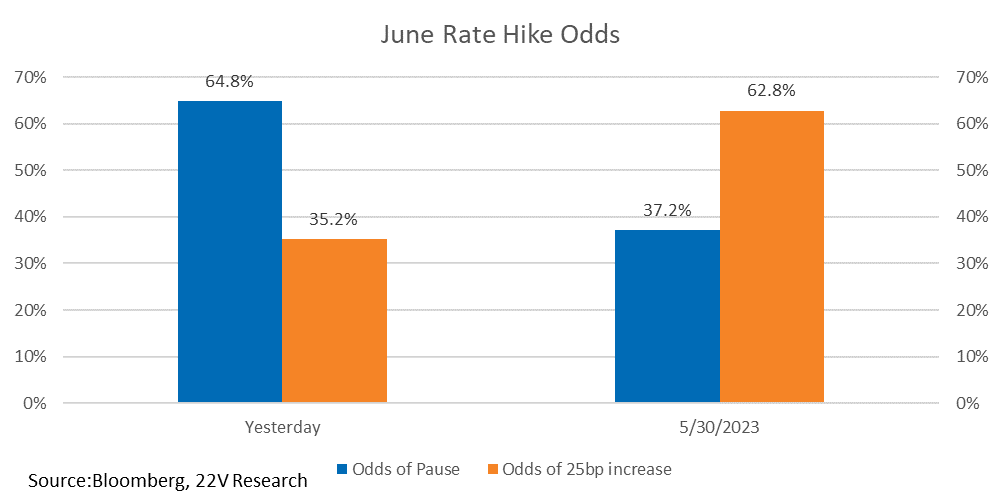
FED LEADERSHIP FYI: Fed Vice Chair Jefferson stated his preference to hold rates at their current levels (HERE). June rate hike odds promptly fell after climbing higher all week off the commentary of other FOMC officials (Mester, Bullard, Bowman, Collins). We have harped on fading the noise from non-leadership Fed officials in favor of the opinions of the leadership (Powell, Jefferson, Williams). Leadership has been telling us the Fed will pause. Expect a pause unless the payroll data is unusually strong.
Full report below…
MARKET VIEWS: We are less excited about the market risk reward and Cyclicals vs Defensives here. We laid out some of the reasons yesterday (HERE): the market is at the top end of our fair value range and Cyclicals have had a 99th percentile move in a mean reverting backdrop. But this time is different than when we argued that recession risk was farther out than investors’ thought this past year. The labor market appears set to loosen and that has been the MAJOR data point we are focused on. As Gerard has argued this week, corporate profitability is falling (HERE) at a time when underlying demand is running about 1%. It’s tough to maintain current levels of wage growth (would imply significantly more margin deterioration) in that backdrop.
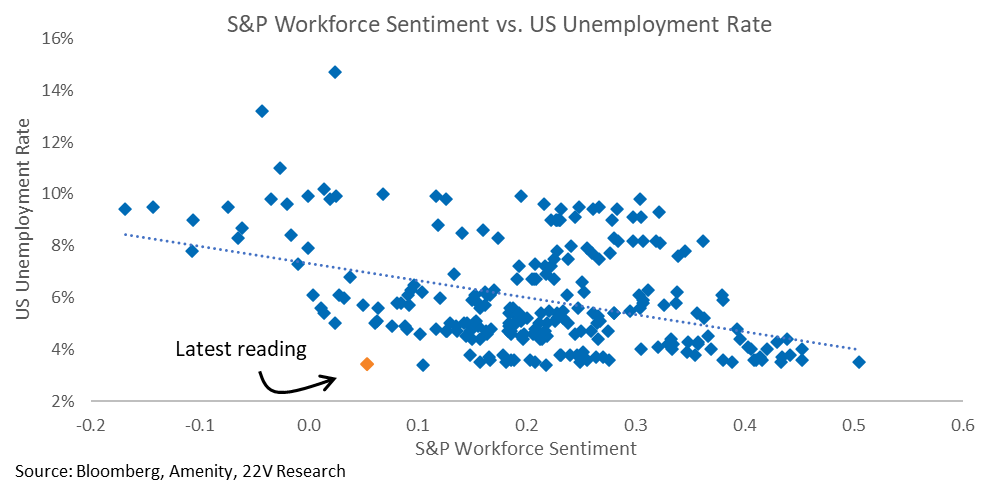
GETTING AHEAD OF DETERIORATING LABOR DATA: Our tone change may be a bit early. Labor data on Friday will help inform that. There is some evidence that data Friday will be strong (WEI and claims this month have been flat, MNI has a model that estimates a very strong Payrolls report) BUT you don’t want to be late positioning for deteriorating labor data. You don’t want to own risk into potential blowups. Maybe the data Friday is fine, but the urate is due to increase as profitability falls. Workforce sentiment, which measures how management teams talk about headcount, hiring, layoffs, and wages indicates the urate should increase.
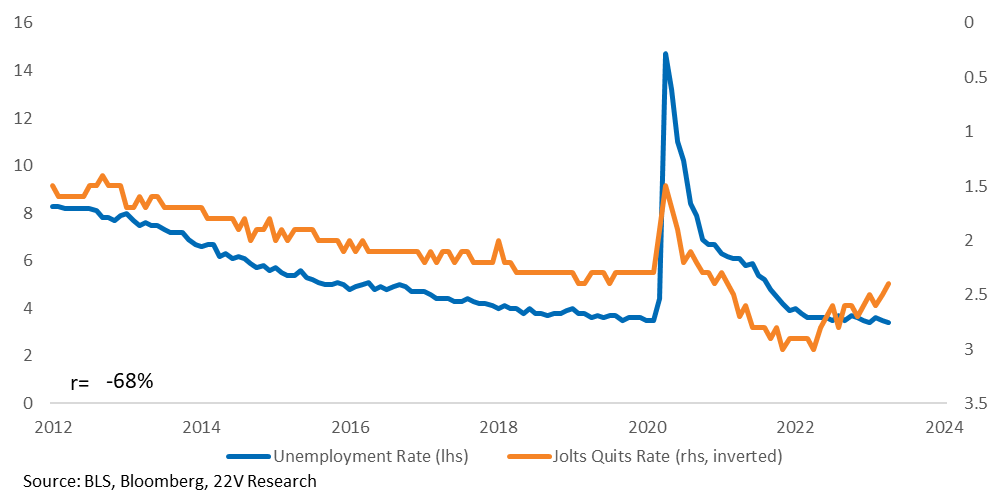
In the JOLTS data yesterday job openings increased BUT the quits rate fell. As Gerard puts it, “the quits rate may be a more objective metric, being based on actual employment decisions, rather than mere postings. To quit a job is a big deal. To post — or to forget to remove — a posting is not.” The quits rate indicates a looser labor market, the question becomes can economic activity hold up as this happens. Increases in unemployment tend to be disorderly, re-introducing equity volatility.
POSITIONING FOR TIGHTER FINANCIAL CONDITIONS: Financial conditions will tighten as the labor market loosens, even if the Fed pauses (which we expect). Volatility should increase and spreads widen as the urate climbs. We will be watching CDX and the percent of companies trading with an OAS >1000bps.
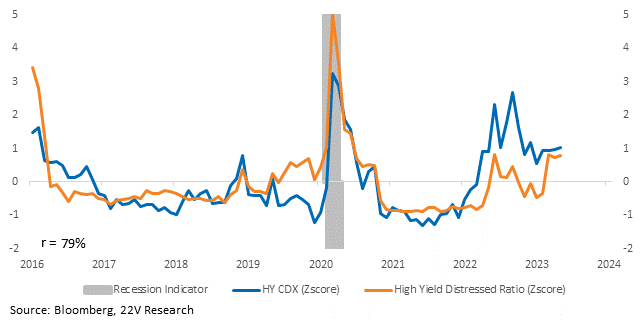
We have a long-short portfolio designed to track changes in FCI. Constituents (ex-Banks, which are un-investable right now) are at the end of the report. Go long the stocks that benefit from tighter conditions and short the stocks that benefit from easier conditions. Again, we want to get ahead of a potential blowup.
FED LEADERSHIP FYI: Fed Vice Chair Jefferson stated his preference to hold rates at their current levels (HERE). June rate hike odds promptly fell after climbing higher all week off the commentary of other FOMC officials (Mester, Bullard, Bowman, Collins). We have harped on fading the noise from non-leadership Fed officials in favor of the opinions of the leadership (Powell, Jefferson, Williams). Leadership has been telling us the Fed will pause.
LONG equities that benefit from tighter financial conditions…
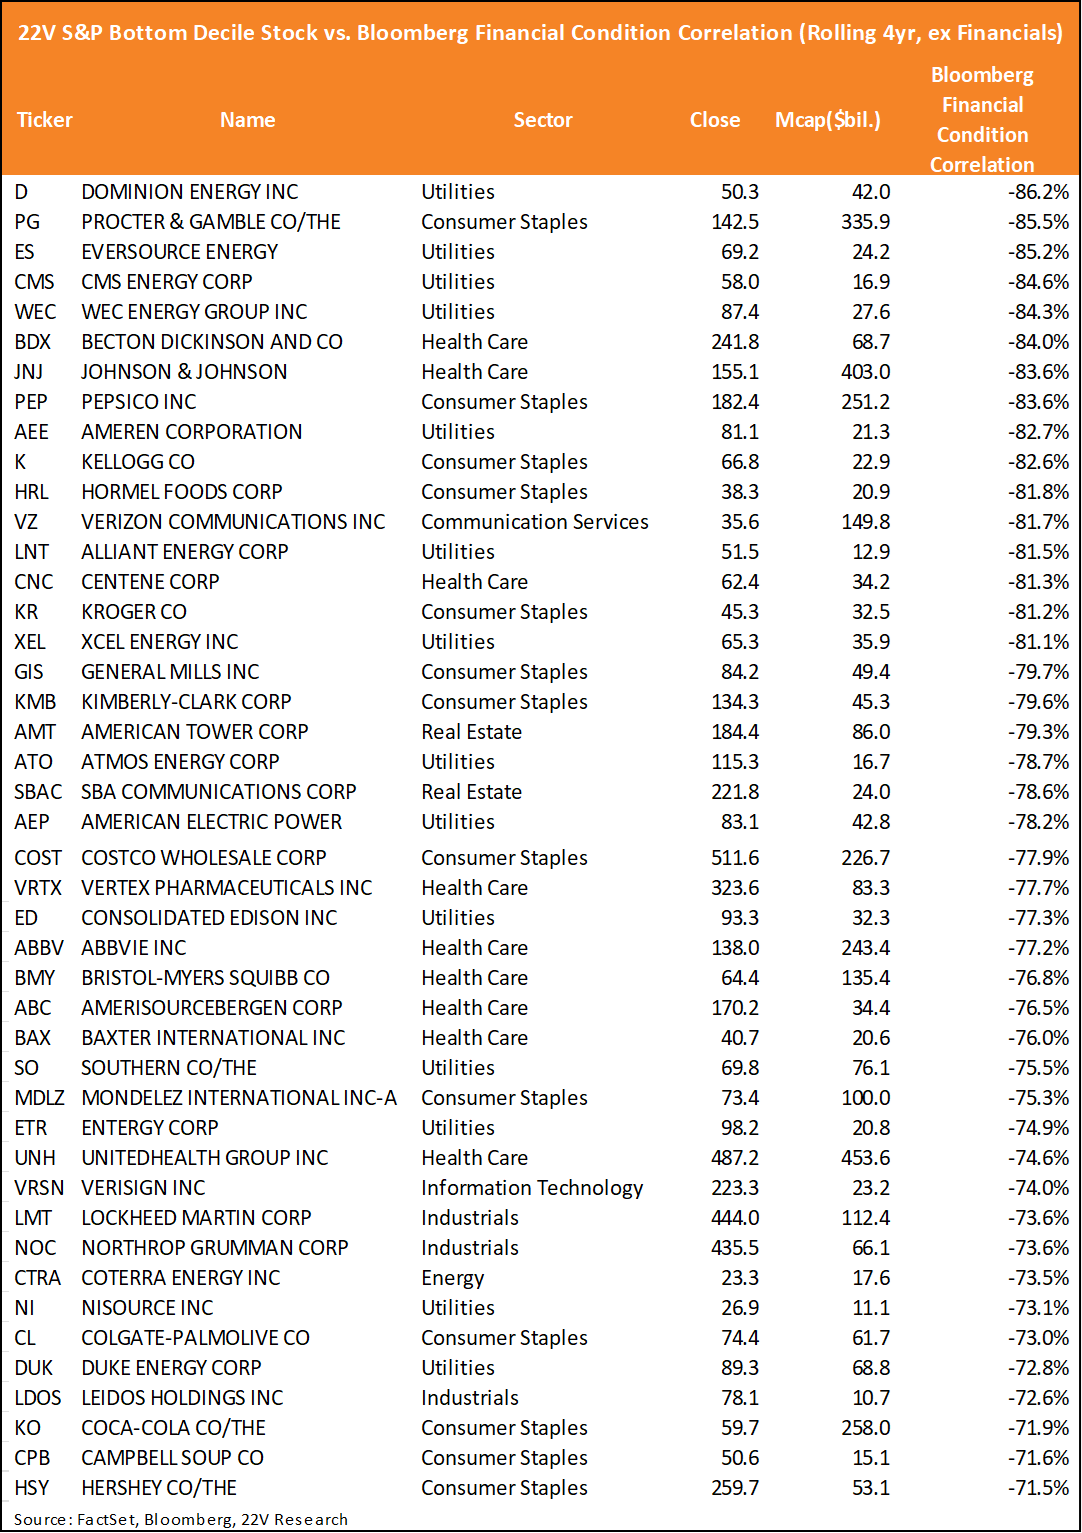
SHORT equities that benefit from easier financial conditions…