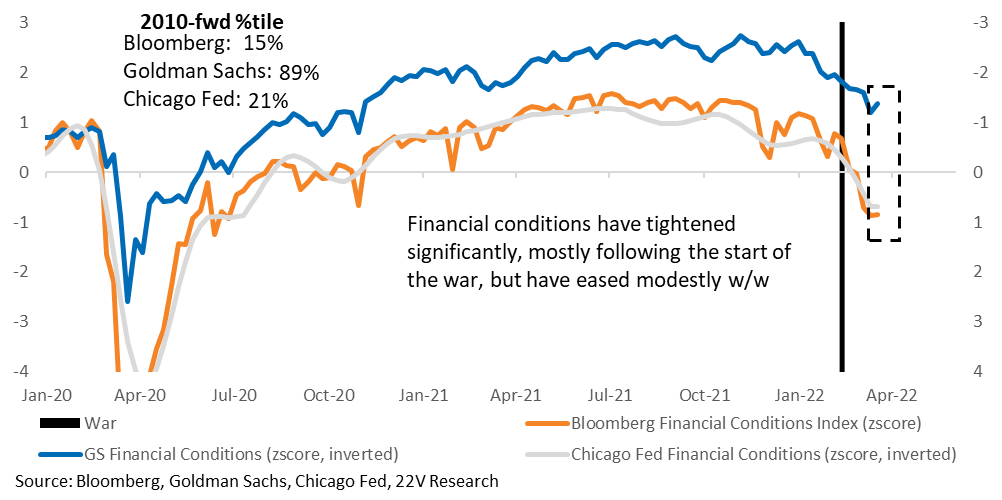
Financial conditions have eased and despite the ongoing war in Ukraine, the S&P rallied 5.5% this week, its best 5-day gain since late-2020. Investors have shifted focused toward the start of the fed rate hiking cycle, which should mean lower inflation and firming real yields. The lack of shocks from the FOMC this week, combined with the difficult to quantify growth headwinds from the war/oil and commodity spike, have created a window where financial conditions can ease, and data may remain weak enough to keep markets from pricing in more rate hikes this year.

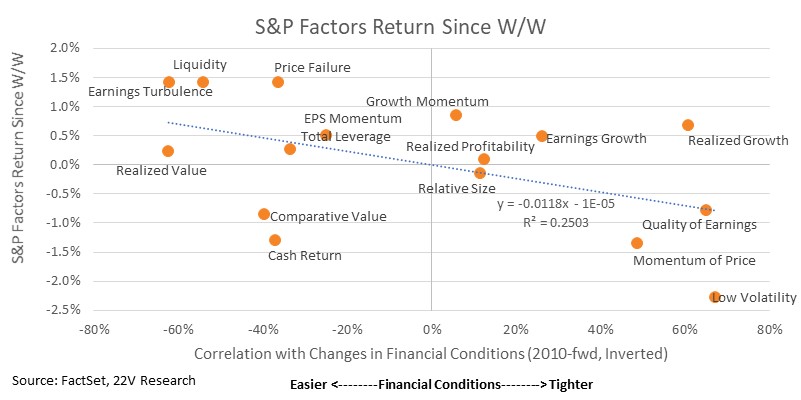
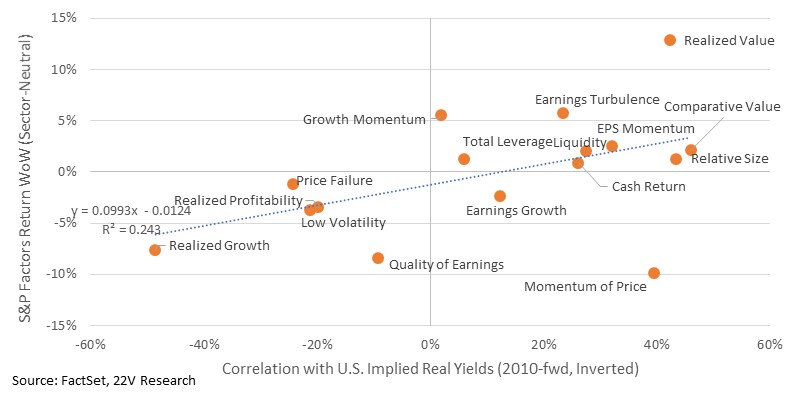
Market returns from the start of the war have been well correlated with tightening of financial conditions with Momentum, Growth, Low Vol, and Quality among the best performing factors. W/W that has reverse and returns are consistent with the easing financial conditions. Momentum names have performed worse than we expected, but that should ease as the current period of market turbulence eases. Higher momentum names tend to perform well in periods of rising real yields AND tightening financial conditions.
The setup heading into the end of March and the start of earnings reporting season in April is more like the start of the year. Pre-war 2022 market internals were dominated by factors that benefit from rising real yields. Firm growth, high inflation, and expectations of a steady pace of rate hikes led to declining inflation expectations and higher yields. That backdrop favored Value, higher volatility names and cash return.
As investors embrace risk-on factors again, speculative Tech names have rebound from their sharp selloff. The meme names and the ARKK index have both rebound some over the past few days. Ultimately, high inflation likely means a faster pace of rate hikes than is currently being discounted, and another round of financial condition tightening, but that theme is on hold near-term.
Market Internals Shifting Away from War Stance: The war between Russia and Ukraine coincided with a sharp tightening of financial conditions in February, but that trend stalled recently and financial conditions have eased. The S&P has rallied 5.5% this led higher by Cyclicals and risk-on factors. Investors have shifted focused toward the start of the fed rate hiking cycle, which should mean lower inflation and firming real yields.
Market returns since the start of the war have been well correlated with tightening of financial conditions with Momentum, Growth, Low Vol, and Quality among the best performing factors. W/W that has reverse and returns are consistent with the easing financial conditions. While investors are discounting a backdrop of gradually slowing growth and a Fed restrained by war-related growth uncertainty, risk-off factors will struggle. Ultimately, high inflation likely means a faster pace of rate hikes than is currently being discounted, and another round of financial condition tightening, but that theme is on hold near-term.
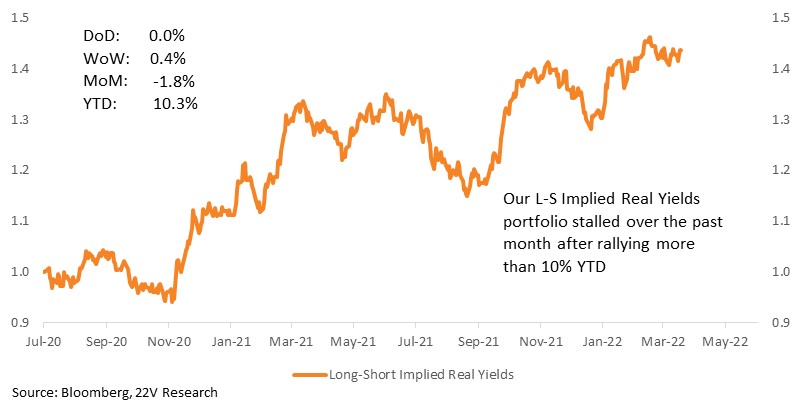
Ove the past month, our Implied Real Yields L-S portfolio has stalled as financial condition tightening dominated market returns. This portfolio consists of stocks most highly correlated (positive/negative) to changes in implied real yields (10yr-5yr inflation swap). From the start of the year through the beginning of the war the Implied Real Yields portfolio gained just under 12%. Even after struggling the past month, it remains up more than 10% YTD (let us know if you would like the full constituents list).
The setup heading into the end of March and the start of earnings reporting season in April is more like the start of the year. Pre-war 2022 market internals were dominated by factors that benefit from rising real yields. Firm growth, high inflation, and expectations of a steady pace of rate hikes led to declining inflation expectations and higher yields. That backdrop favored Value, higher volatility names and cash return. Momentum struggled more than we would have expected in that backdrop as did quality. Medium-term those factors should perform well, but they are at risk near term.
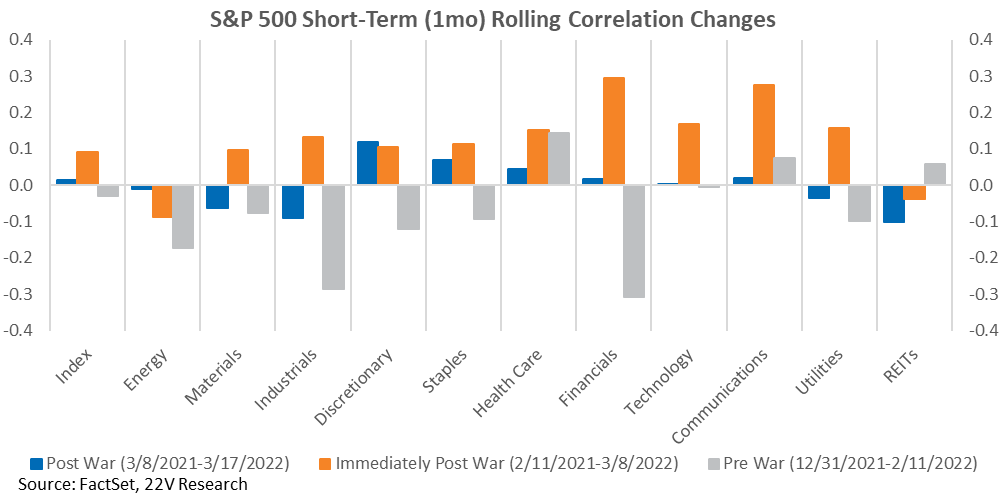
Moving Back to More Stock Picking Friendly Backdrop: Across the market and sectors, short-term correlation increased immediately after the war started, making it more difficult to outperform through single stock selection. Over the past week+, sector correlations have slowed/declined.
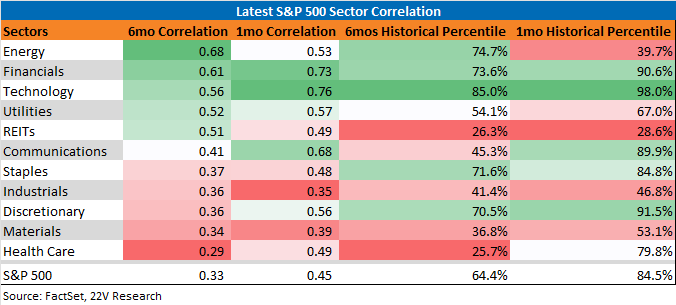
Correlation deltas are interesting, but it is important to keep in mind the degree to which sectors trade together. Correlations within Energy has declined, but it is still the most highly correlated (6mo basis) of all sectors. Its IPC is high as well, suggesting the space remains largely tied to shifts in oil prices. Factor screening within the space is of limited value. Financials are similar.
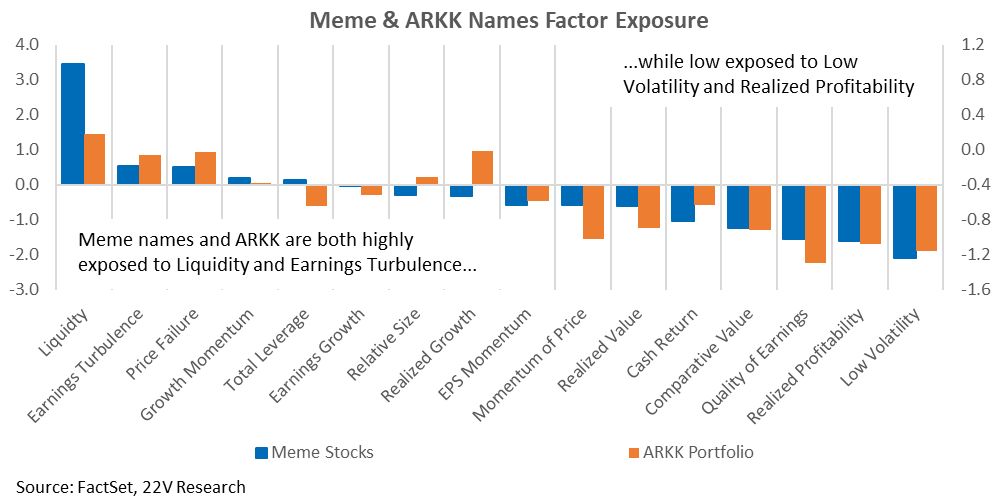
Factor Supports for Speculative Rebound: As investors embrace risk-on factors again, speculative Tech names have rebound from their sharp selloff. The meme names and the ARKK index have both rebound some over the past few days.
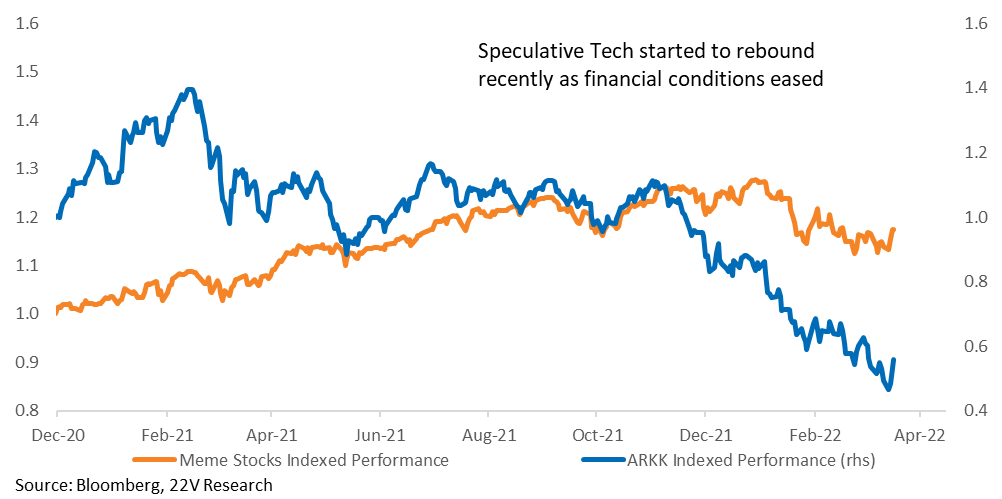
Both Meme names and ARKK holdings are highly exposed to Liquidity and Earnings Turbulence, and negatively exposed to Low Volatility and Realized Profitability. Factor exposure of the speculative Tech names are aligned with the recent factor reversal, support their recovery. However, when investors refocus on the rising rate cycle, speculative tech names are likely to underperform again as they did earlier in 2022.