
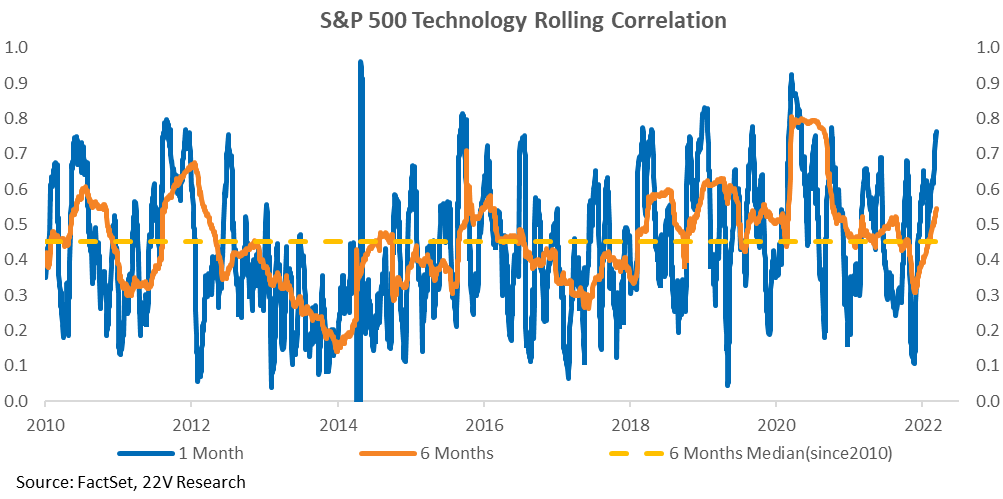
After years of outperformance, mega cap Tech has underperformed so far this year as investors have begun discounting a backdrop of rising rates and above trend growth. As the sectors has moved lower, the correlation between Tech stocks has increased, indicating macro forces are increasingly driving its names. At the sector level it is the third most macro driven group behind Energy and Financials. Profiting from stock selection within Tech is becoming increasingly difficult.
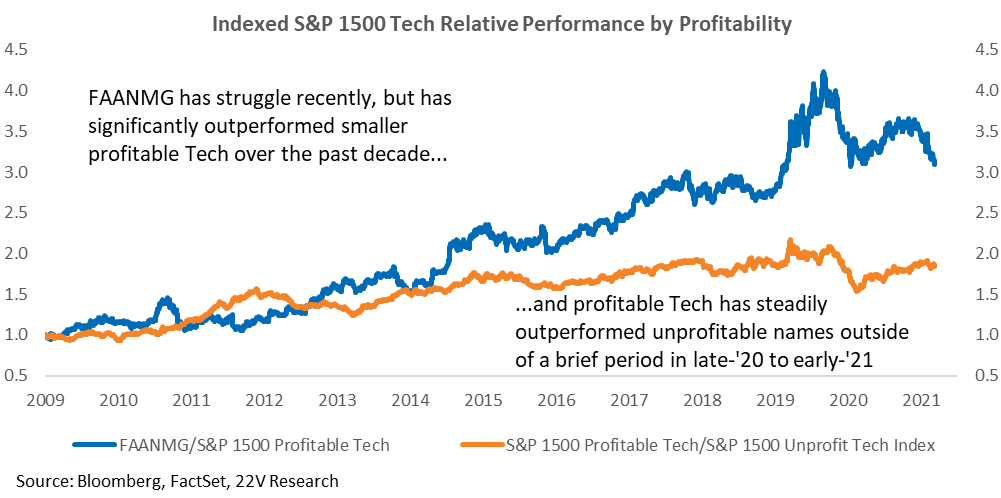
Though FAANMG has struggled recently, over the long-term is has outperformed smaller profitable Tech, and profitable tech names has nearly always outperformed unprofitable tech. Tech stocks with high quality earnings and cash return should be a source of strength in as growth slows and financial conditions tighten.

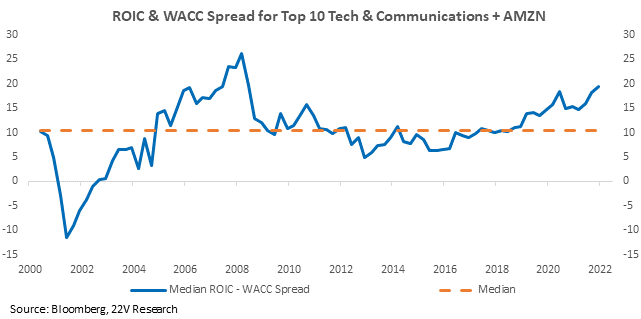
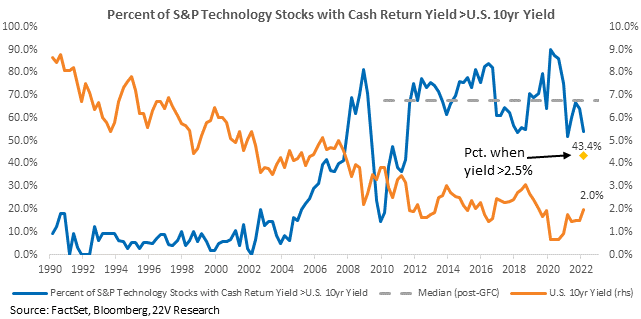
Fundamentals should limit the absolute downside risk to mega cap Tech relative to the broader market. Today, the spread between mega cap Tech’s ROIC and cost of capital is near its highest level on record, and the group’s profit margins are also extremely high. Though valuations with Tech remain elevated, its high growth rate and cash return profile leave it relatively attractive on an expected yield basis. Currently, more than half of Tech names has cash return yields above the U.S. 10yr yield.
Overall, we maintain our market weight position toward Tech. More speculative names face headwinds as financial conditions tighten and increasing correlation/macro influence suggests mega caps could remain under pressure near term. Longer-term, high profitability and cash returns are a support for Tech as a whole and mega caps specifically. We recommend sticking with higher quality, lower turbulence names near-term as market pricing is adjusted to reflect the shift in the monetary policy backdrop.
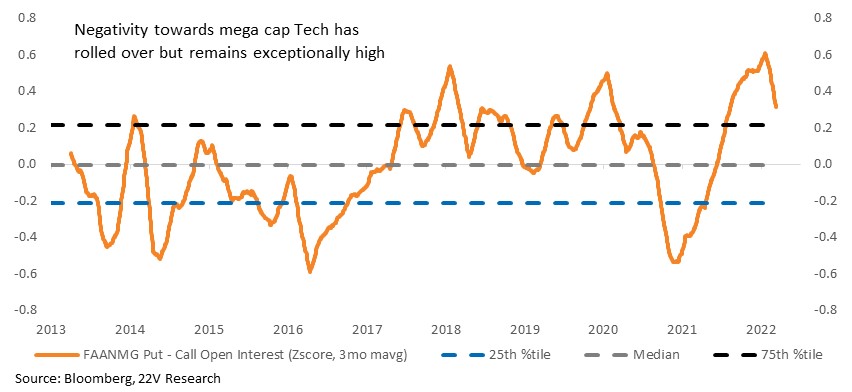
Assessing Technology: After years of market setting gains, mega cap Tech has underperformed YTD as investors begun adjusting prices for a backdrop of rising rates and above trend growth. S&P Technology Index has underperformed the S&P by -6.4%, while the FAANMG basket has underperformed -12.1% YTD. Negativity toward the mega caps peaked in early 2022 but remains extremely high based on the put/call ratio. A positive catalyst for the sector could help unwind that negative positioning and push the stocks higher, but there are no clear ones on the horizon.
Stock return correlations have climbed rapidly higher within Tech recently as the selloff has become more pronounced. 1 and 6-month correlations care at their 98th and 83rd %tiles respectively. On a percentile basis, that is the highest reading of any GICS sector today. Alpha generation within Tech through stock selection has become increasingly difficult.
On a relative basis, profitable Tech names have continued to outperform unprofitable Tech. In general, unprofitable names within Tech have underperformed profitable names, a trend we expect to continue as interest rates normalize higher. FAANMG has fallen sharply but has significantly outperformed smaller profitable Tech long term. The question going forward is a backdrop of rising real yields, tightening financial conditions, and ultimately slower growth will lead to a persistent allocation away from mega caps.
Profitability of large cap Tech has been climbing over the several years, coinciding with the vast outperformance of mega caps. Increasing returns to capital have pushed median ROIC for the group near 30% while the cost of capital has remained steady. Profit margins for Tech in general and mega caps in particular are high relative to most other groups. High profitability will become an increasingly important differentiator for stocks as inflation comes down, and that favors Tech/mega caps.
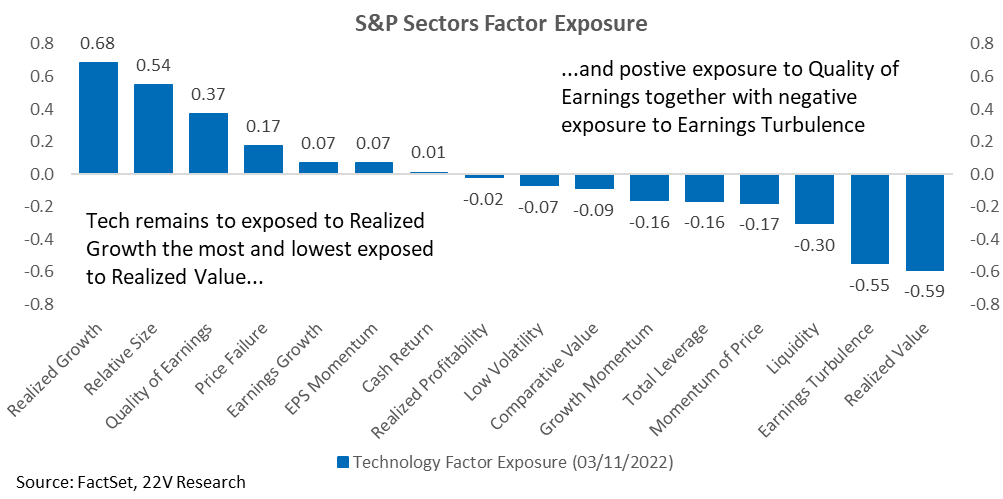
At the factor level, broad Technology remains highly exposed to Realized Growth and Quality and more negatively exposed to Realized Value and Earnings Turbulence. As we mentioned, thinking in terms of Volatility and Quality rather than Growth vs. Value is more important as financial conditions tighten. Quality of Earnings tends to perform well during periods of tightening financial conditions, bringing a tailwind to high Quality Tech relative to more speculative names.
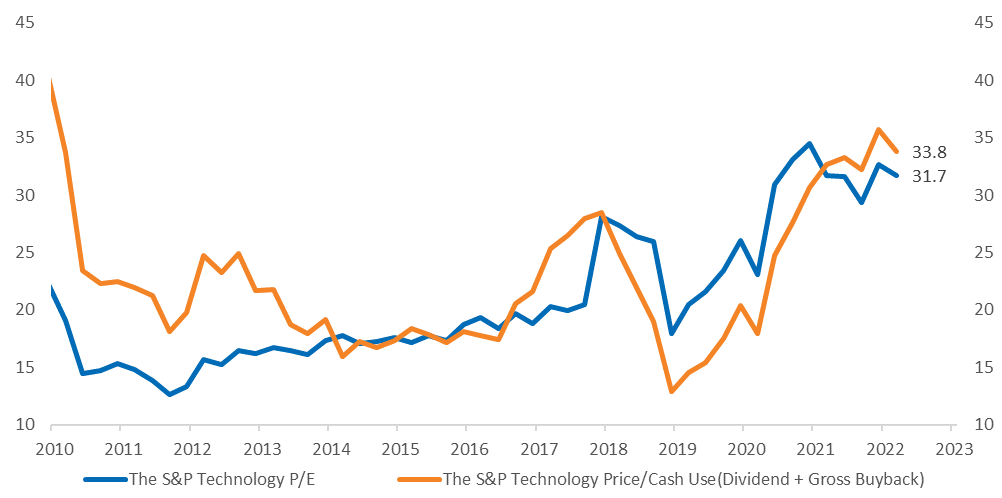
Valuation is where Tech’s positive backdrop becomes more complicated. The P/E of S&P Tech names has reached its highest readings since 2010, leaving the sector looking expensive on an absolute basis. At the same time, cash return within Tech, especially buybacks, leaves the sector with an unusually high total yield. AAPL remains the S&P company with the greatest amount of buybacks, spending $87 billion on net buyback over the past 12 months. Cash return increases the attractiveness of the sector while providing an inorganic support for earnings growth entering a period where that growth will become more scarce.
High cash return is why the percent of S&P Technology stocks with yields greater than the U.S. 10yr remains elevated (52.6%). In other words, more than half of Tech names have cash return yields better than Treasuries. Even as bond yields back up further high cash return will continue to support Tech valuation and performance.
Overall, we maintain our market weight position toward Tech. More speculative names face headwinds as financial conditions tighten, increasing correlation/macro influence suggests mega caps could remain under pressure near term. Longer-term, high profitability and cash returns are a support for Tech as a whole and mega caps specifically. We recommend sticking with higher quality, lower turbulence names near-term as market pricing is adjusted to reflect the shift in the monetary policy backdrop.

