Market volatility has increased as first the shift in Fed policy and more recently the invasion of Ukraine reduced risk appetites. We have been focused on thematic investments as macro influence over markets have generally remained low and market directionality has become less clear. As the Fed moves to raise rates and lower inflation, price sentiment will come under pressure, while tight labor markets and remaining supply chain issues will keep costs high. The backdrop leaves pricing power as one of our favorite themes. In a rising rate backdrop, Companies with the ability to maintain pricing power should be better able to maintain profitability and earnings as those factors move from abundant to scarce.
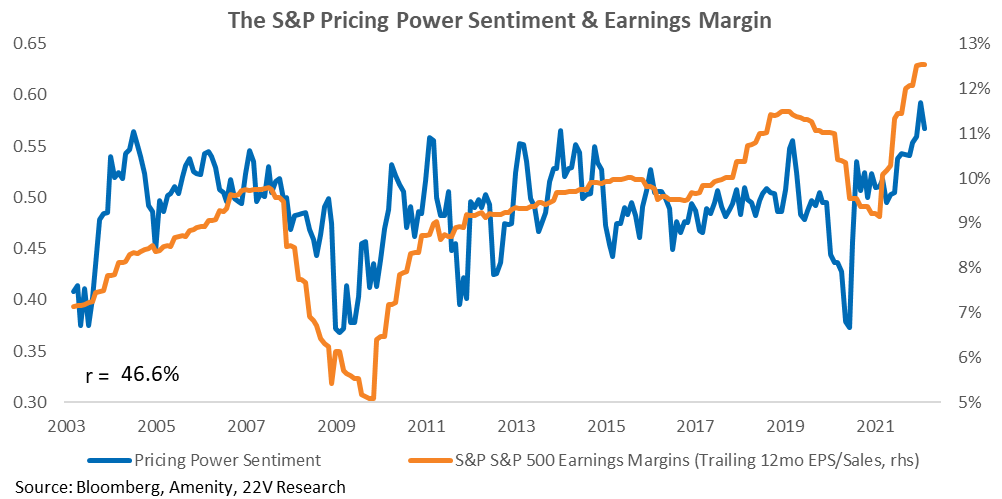
At the end of 3Q reporting we create a Pricing Power Sentiment portfolio based on the Amenity Analytics pricing sentiment readings. Historically, there has been a positive correlation between pricing power sentiment and relative S&P profit margins. The portfolio has outperformed the S&P by 2.2% YTD as inflation and the shift in fed policy has become an increasing concern. With 4Q earnings reporting winding down, today we rebalance the portfolio based on the latest sentiment scores.

We expect pricing power will prove a valuable sorting factor across sectors and industries, and that will become clearer as rate hikes get underway and inflation eases. Currently, at the index level both pricing power and margin sentiment are still near their all-time highs, consistent with profitability consistently beating expectations.
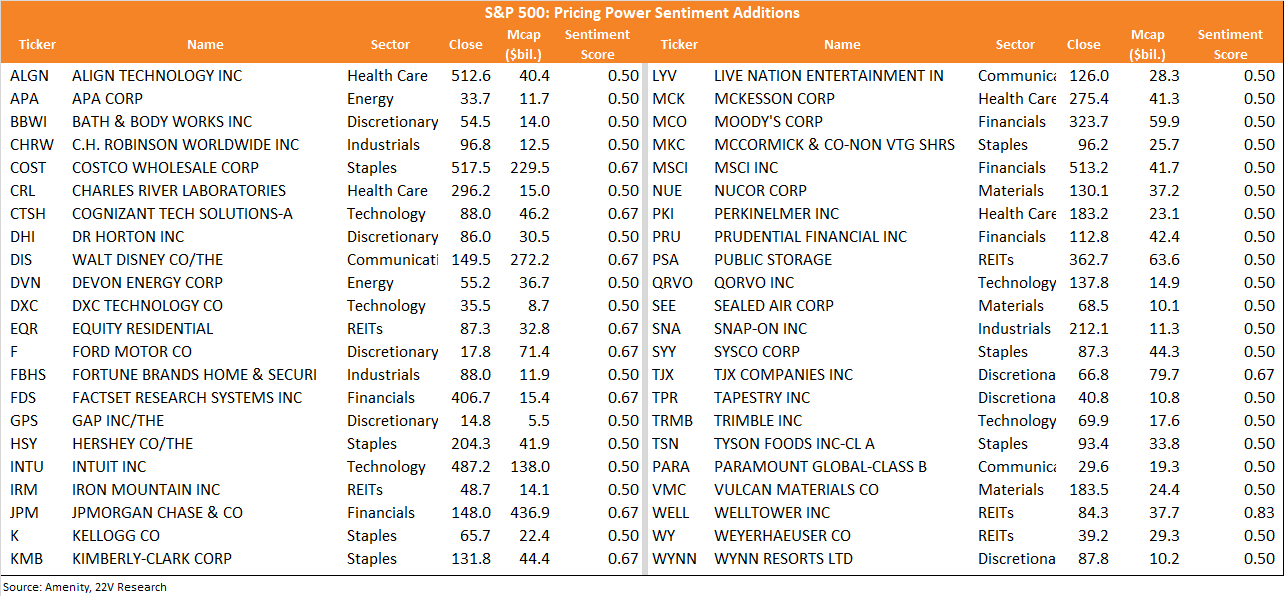
Pricing power is difficult to systematically screen for using traditional factors. At the end of the report, we list the additions to our rebalanced pricing power sentiment portfolio. For those taking a systematic approach, these are names we expect will be less negatively impacted by rising rates and weakening margins over the coming quarter. For more fundamentally focused investors, this list is meant as screening tool to systematically search for possible high pricing power names.
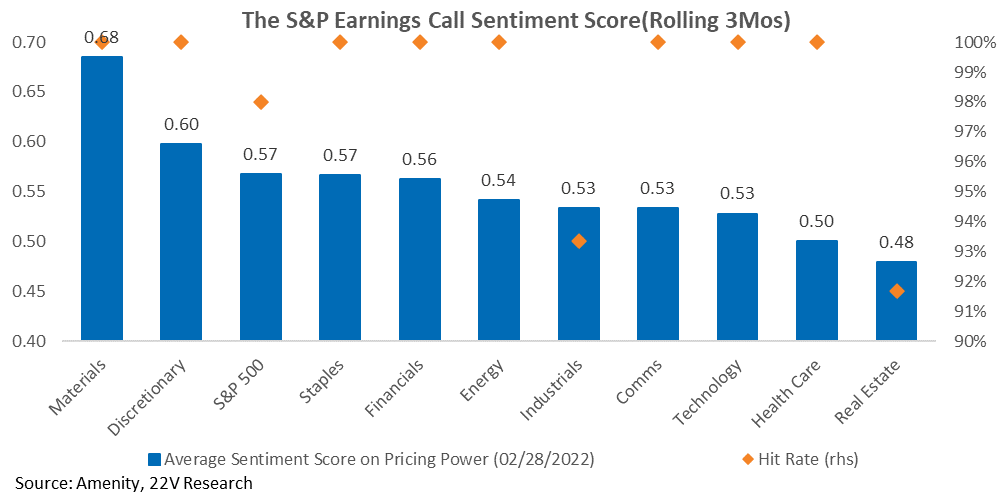
Pricing Power Portfolio Rebalancing: As inflation continues to rise, companies ability of maintain pricing power will become increasingly important factor. Historically, there has been a positive correlation between pricing power sentiment and realized profit margins. Currently, S&P pricing power sentiment is 0.57, down slightly from last quarters all-time high reading. That reading is consistent with the still elevated level of index margins. Overall pricing power has improved as the COVID overhang as eased and inflation has moved higher.
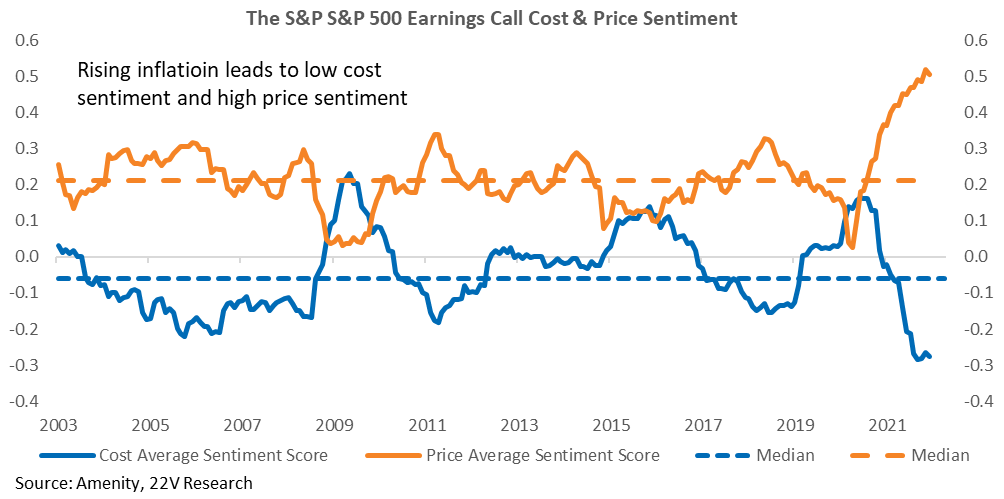
Pricing power sentiment remains near its all-time high, assisted by strong goods and services inflation. At the same time, cost sentiment has fallen to near its lowest level in 19 years. As the Fed moves to raise rates and lower inflation, price sentiment will come under pressure, while tight labor markets and remaining supply chain issues will keep costs high.
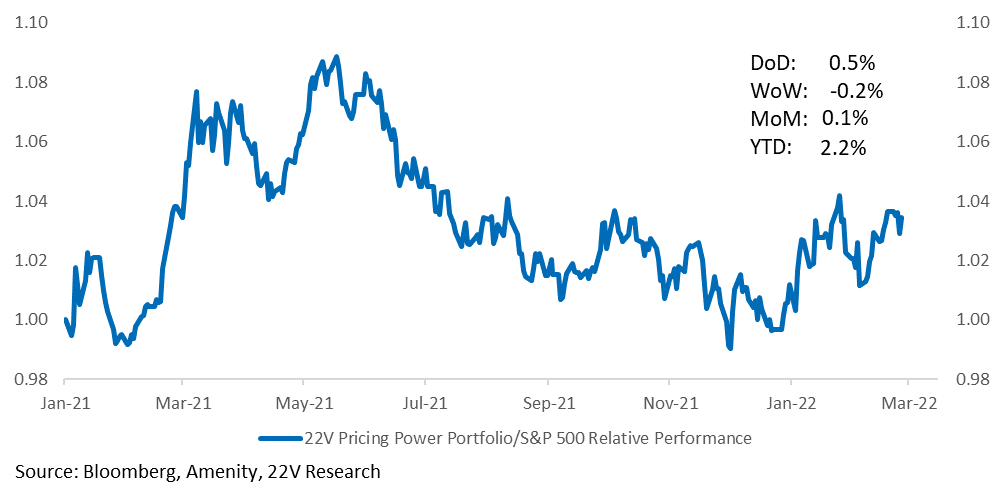
We construct a pricing power portfolio at the end of each earnings season based on management sentiment measured using the Amenity natural language processing (NLP) tool. The portfolio consists of companies with high relative pricing powering sentiment expressed during 4Q earnings call. The portfolio has outperformed the S&P by 2.2% YTD as inflation and the shift in fed policy has become an increasing concern.
Within the index, Materials and Discretionary are the sectors with the highest pricing power sentiment scores, both exceeding the index average. REITs and Health Care have the lowest pricing power sentiment. On average, Cyclical names are posting better pricing power sentiment than Defensives. No Utilities names mentioned pricing power enough to have ratings, so the sector was excluded from our rankings.
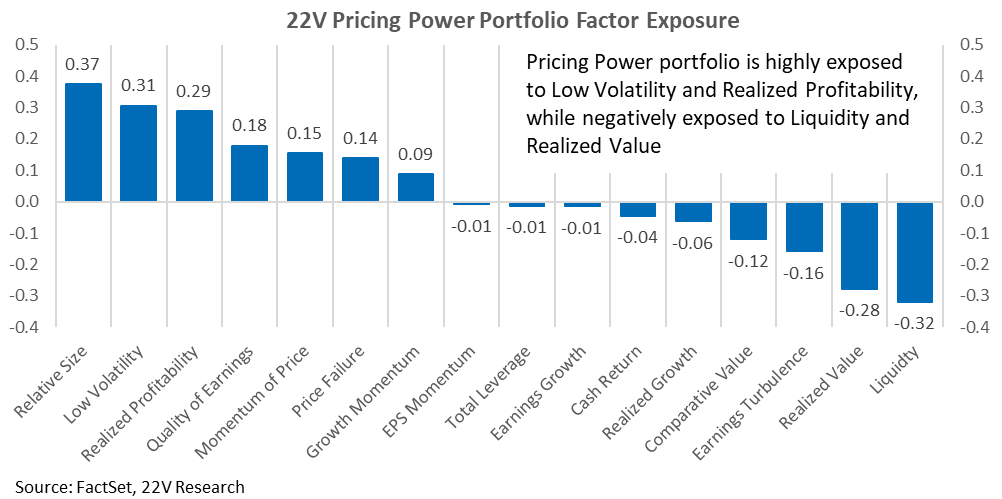
At a factor level, our rebalanced pricing power portfolio has high exposure to Relative Size, Low Volatility and Realized Profitability, while it is negatively correlated with Liquidity, Realized Value and Earnings Turbulence. Factor exposure shows the profitability of high pricing power names given high exposure to Realized Profitability and Quality of Earnings.
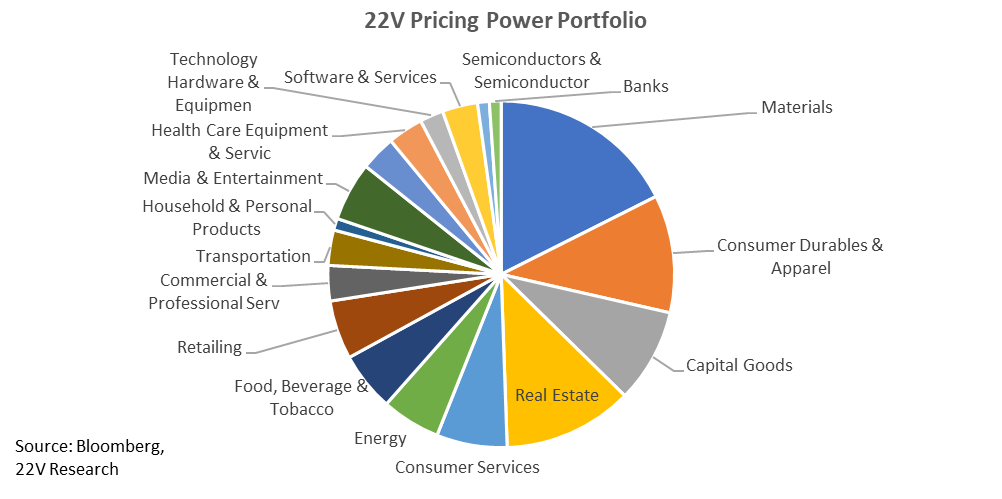
In line with sector level pricing power scores, Materials account for the greatest number of names in the updated portfolio. 16 out of 100 names in the basket fall into Materials, followed by Consumer Durables & Apparel, and Capital Goods. The portfolio industry group exposure is more exposed to Cyclicals than Defensive names.
Below we list first the new names added to our Pricing Power Sentiment portfolio. These names with the strongest pricing power sentiment during their latest earnings releases. These are the new names we would focus on when looking for companies that can maintain their profitability as rates trend higher over the coming quarter. Email us for a complete list of constituents.