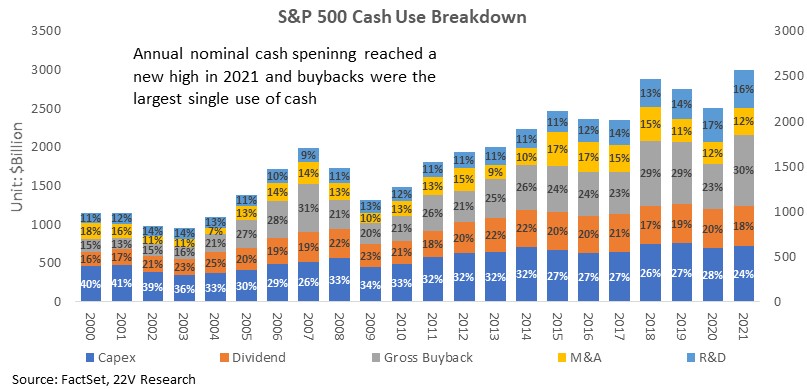
Economic growth and corporate earnings have rebounded, exceeding their pre-pandemic levels. Total cash spending rebounded as well, growing 19.5% in 2021 to ~$3tril, exceeding the $2.8tril spent in 2019. Buybacks are again the most popular cash use with gross share repurchases reaching $900bil, and far exceeding dividend payments of $526 billion. Normalized buybacks (relative to cash flow) were much more volatile than dividends during the COVID shock and that same higher beta helps explains why buybacks able make up 30% of total spending. Management sentiment towards buyback was higher during 4Q conference calls, exceeding its pre-COVID level and suggesting further expansion in 1Q22.

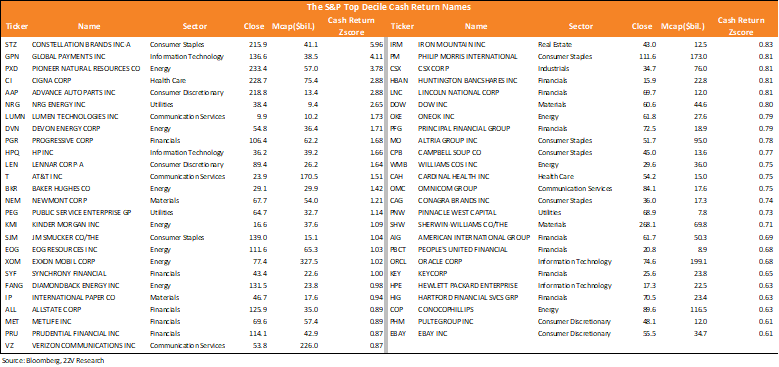
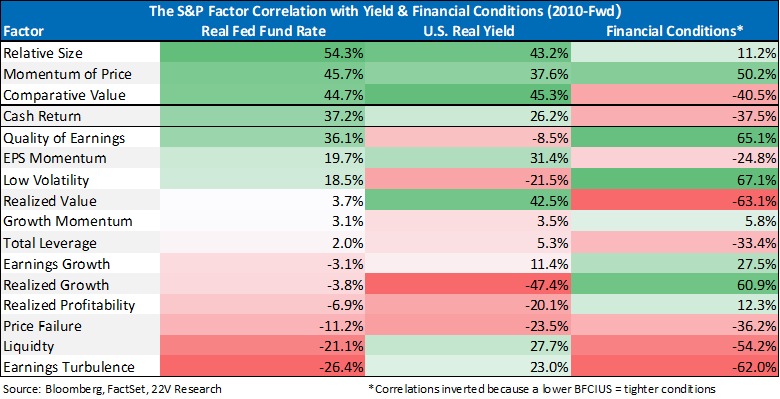
Our Cash Return style factor, which ranks companies by their dividend and buyback yield, payout ratios and growth rates, has been gaining steadily since 2020. With the Fed is expected to start rising rates in March, real rates/yields are climbing higher and financial conditions are tightening. That macro backdrop will limit nominal cash return, but should be a tailwind for high Cash Return names given the correlations between Cash Return performance and the change in real yields/financial conditions. At the end of this report we list the S&P names with the highest Cash Return exposure.
Strong Buyback & Tailwind on Cash Return: Most S&P names have published their 4Q earnings, and total cash use has fully recovered from its COVID trough and now exceeds its 2019 level. Net Buybacks were $786 billion in 2021, far greater than the $526 in dividend payments. Capital expenditure climbing 4.1% to $720bil, modestly below its pre-COVID level. Increased capital spending during the economic recovery is another reason economic growth remains above is post-GFC trend today.
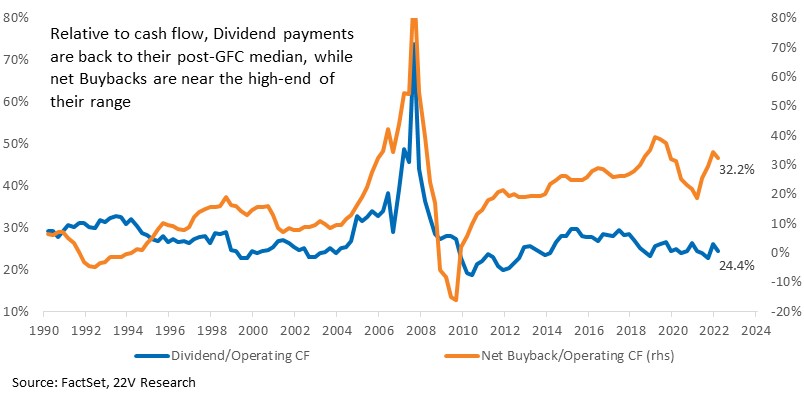
Trailing dividend payments as a percent of operating cash flow were stable during COVID and remain near their post-GFC median. Buyback, which have become increasingly popular, particularly over the past decade, were much more volatile during the pandemic. Share repurchases are higher beta than dividends, falling faster as the recession began and rebounding quicker as the economy recovered. Though off their 1Q19 peak relative to cash flows, spending on net buybacks are at a new nominal high.
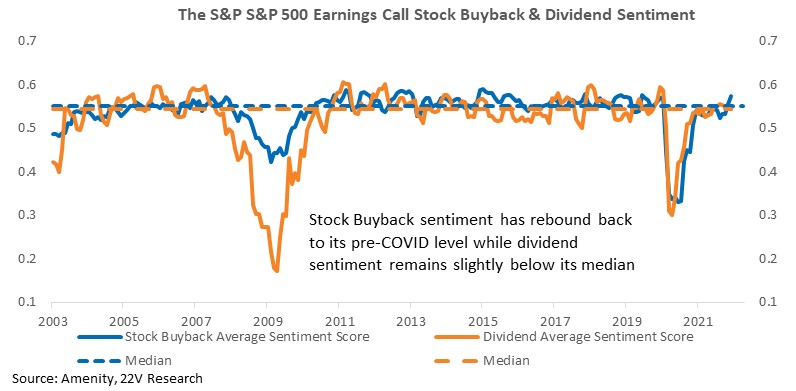
In line with the spike in and breakdown of cash use, management sentiment towards buyback has rebound quicker as well. Sentiment toward buybacks during 4Q conference calls, which we measure using the Amenity natural language processing tool, rebound back to pre-COVID levels. Dividend sentiment rebound as well though it is lower than buyback sentiment. Buybacks are once again the most popular way to return cash to shareholders.
Our Cash Return factor, which ranks companies by their dividend and buyback yield, payout ratios and growth rates, has gaining since the COVID market low. Returns to the Cash Return factor have been strong over the past decade as cash return has become increasingly popular. Performance of the factor, on an unconstrained basis, has stumbled a bit recently as mega-caps, many of which have high cash return profiles, have come under pressure.
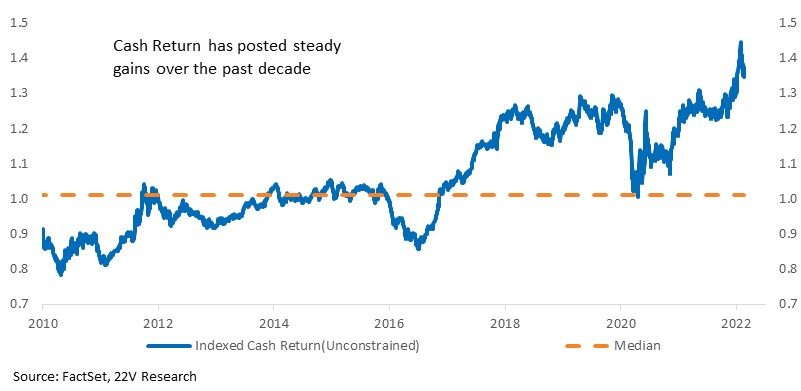
Longer-term, the macro regime shift favors Cash Return. It is widely expected that the Fed will start raising rates in March to rein in rising inflation. Real fed funds and real yields are already climbing higher and financial conditions should tightened further as well. That backdrop is a tailwind to Cash Return given the positive correlation with yield and negative correlation with the Bloomberg Financial Conditions Index.
Below we list the names with the highest Cash Return score. These names are most exposed to Cash Return. The rising rate and tightening financial conditions should continue to support the names with high Cash Return exposure.