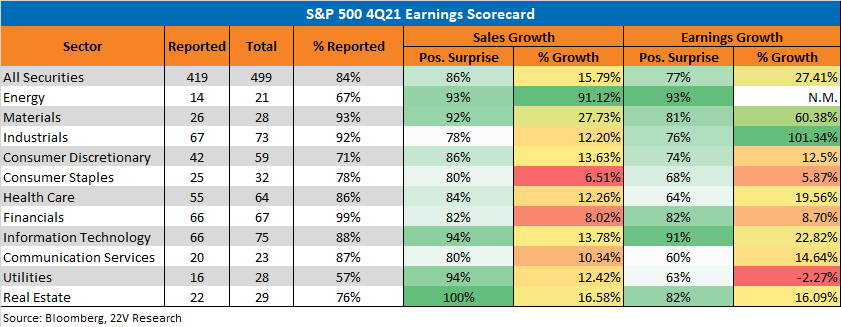
Most of the S&P (85%) has reported 4Q earnings and once again posted much stronger than expected results. Corporate margins defied expectations throughout 2021, powering a nearly 50% EPS growth last year, more than 2X the growth expected at the start of ‘21. Stronger sales and expanding margins allowed the index to post a mid-20% total return despite PEs contracting more than -1 point.
So far in 2022, the S&P is down more than -9% on a nearly -2.5 point PE contraction. Again, strong fundamentals have mitigated the valuation driven market decline, but the outlook for revenue growth and profitability has weakened. Management sentiment, measured using the Amenity Analytics natural language processing tool, toward current financials remains positive, but forward guidance, margin, and earnings sentiment have all declined. Half of the GICS sectors now have negative forward earnings sentiment.
Firm U.S. economic and high inflation have pushed rate hike expectations higher and tightened financial conditions. Part of what the Fed is pushing back against is the strong pricing power that has allowed company margins to consistently beat aggregate analyst expectations. Weakening pricing power is a threat to 2022 EPS estimates, which are based on margins firming over the course of the year.

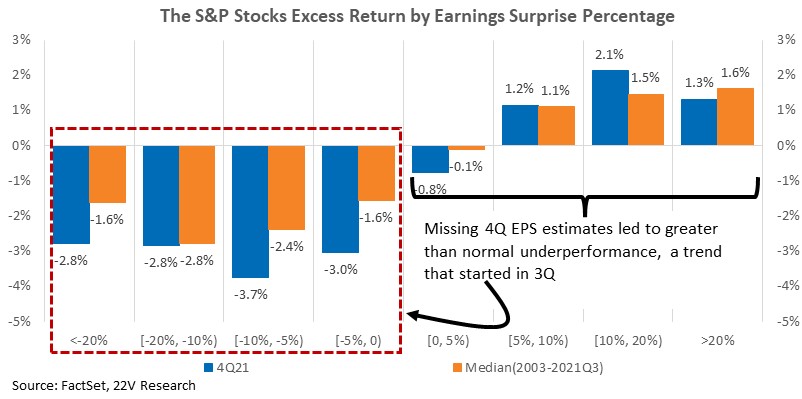
In 4Q, most companies posted positive earnings and sales surprise (86% and 77% respectively), with Cyclicals stronger growth than Defensives, especially deep Cyclicals such as Energy, Industrials and Materials. But companies that missed estimates underperformed by a larger degree than normal. That is a continuation of a trend that started in 3Q.
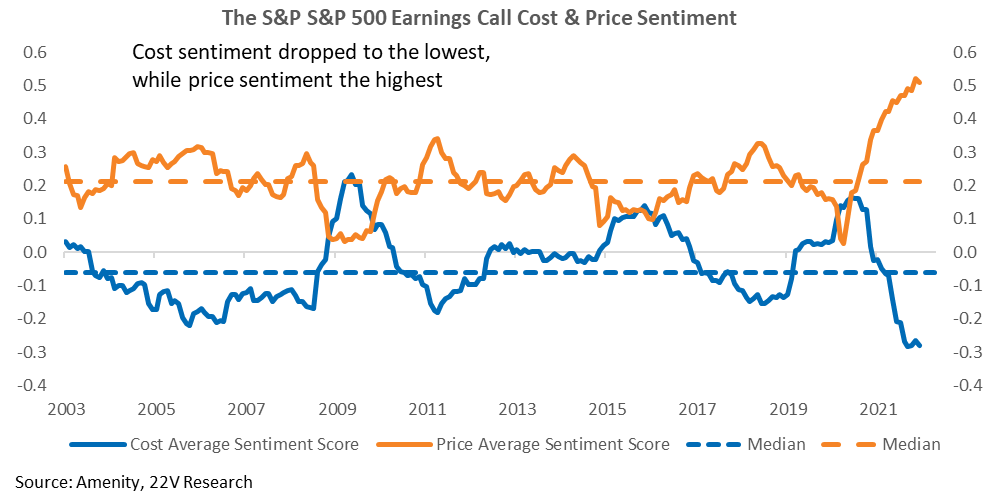
Inflation remains an influential factor for S&P companies. Management sentiment towards costs reached a new low in 4Q while price sentiment skyrocketed. Again, rising sales prices allowed companies to pass along increasing costs. Given the Fed’s assault on inflation, monitoring pricing power, which we also measure using sentiment analysis, will be another important component of avoiding downside risk during earnings reporting season.
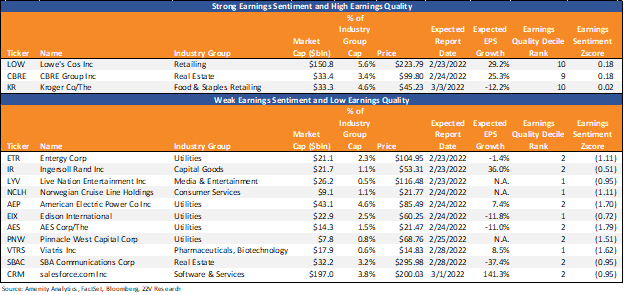
To help avoid earnings misses for the remainder of reporting season, at the end of this report we list the companies reporting over the next week that have the best/worst Quality of Earnings scores and forward earnings sentiment from the previous quarter.
4Q Earnings Show Profitability Increasingly at Risk: Most of the S&P (85%) has reported 4Q earnings and again saw much stronger than expected results. most companies posted positive earnings and sales surprise (86% and 77% respectively), with Cyclicals stronger growth than Defensives, especially deep Cyclicals such as Energy, Industrials and Materials. 4Q results, particularly top line growth, are another sign that economic activity remains strong.
The percentage of companies beating earnings and sales estimate remained higher than normal in 4Q, but stock performance around beats has been lackluster. The 14% of companies that missed EPS estimates saw greater than normal underperformance around reporting.
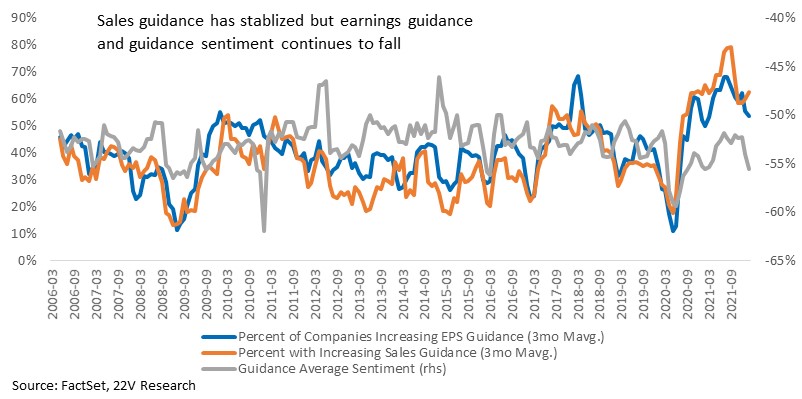
Looking ahead to 1Q22 and beyond, the EPS outlook has deteriorated some. Earnings guidance has softened with the percent of companies increasing EPS guidance moved lower. Guidance sentiment deteriorated as well. Sales guidance both rebounded and remains at a high level though, so top line growth should remain strong.
Firm U.S. economic and high inflation have pushed rate hike expectations higher and tightened financial conditions. Part of what the Fed is pushing back against is the strong pricing power that has allowed company margins to consistently beat aggregate analyst expectations. Weakening pricing power is a threat to 2022 EPS estimates, which are based on margins firming over the course of the year. Margin sentiment, which peak in late 2021, has moved rapidly lower, with “commentary” (forward looking sentiment) falling back to its longer-term median.
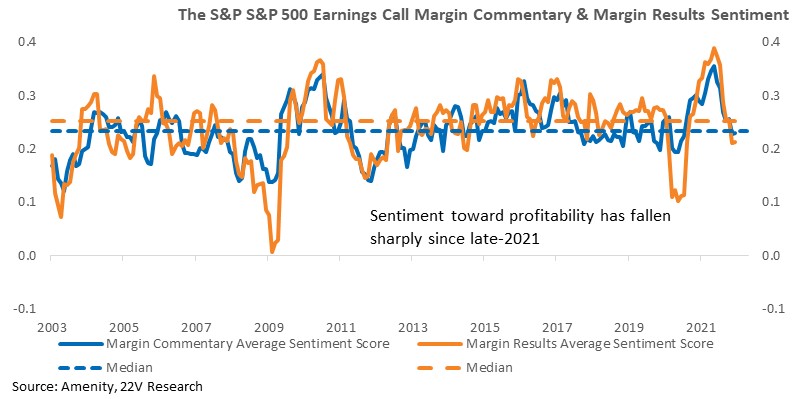
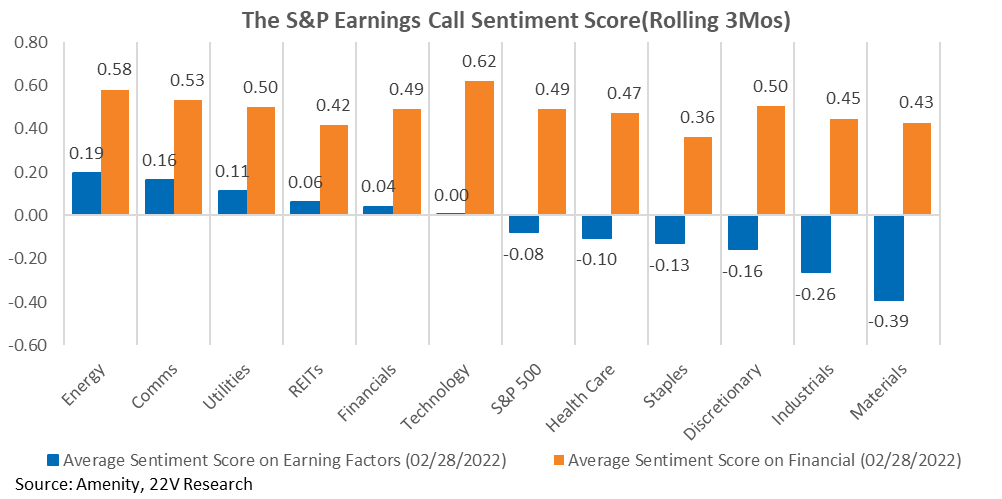
Deteriorating margin sentiment is consistent with the weakness in total earnings sentiment. Sentiment toward earning factors, which focus on forward looking earnings, have dropped and half of earning factors have been negative. Energy and Communications have the best earnings sentiment while Materials and Industrials have the worst. S&P financials, a measure of current fundamentals, remained strong in 4Q, but forward looking measures are more important when thinking about where fundamental supports are likely headed in 2022.
Inflation remains an influential factor for the S&P companies. Management sentiment towards costs reached the lowest level in our series in 4Q, while pricing sentiment skyrocketed. Strong pricing allowed corporate margins to expand despite increased cost pressures. Given the Fed’s assault on inflation, monitoring pricing power, which we also measure using sentiment analysis, will be another important component of avoiding downside risk during earnings reporting season.
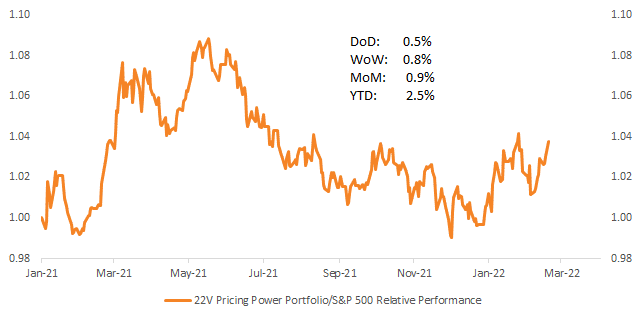
Our pricing power portfolio, which contains the companies with the strongest pricing power sentiment readings, has been outperforming this year. As investors adjust to the Fed’s new policy stance, particularly as inflation eases, strong pricing power companies should continue to outperform.
In the near-term, to help clients avoid earnings misses and negative guidance, in the table we list the S&P stocks with the best earnings sentiment and Earnings Quality rankings that haven’t reported earnings yet. The second basket is the short end; those names with the worst sentiment and Earnings Quality ratings and are more likely to miss. Email us for a complete ranking of remaining stocks for 4Q earnings season.