
Our entire repository of COVID charts is HERE.
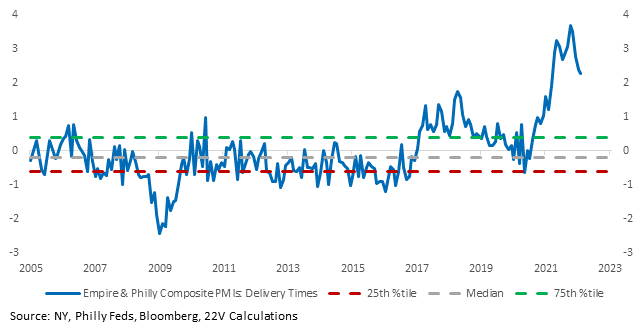
Supply chain sentiment continues to improve while the number of times supply chains are mentioned in the news keeps increasing. So far, the Omicron disruption to important supply chain countries just hasn’t been as bad as expected. And there are preliminary signs of progress; most recently, delivery times fell in the early Fed regional PMIs.

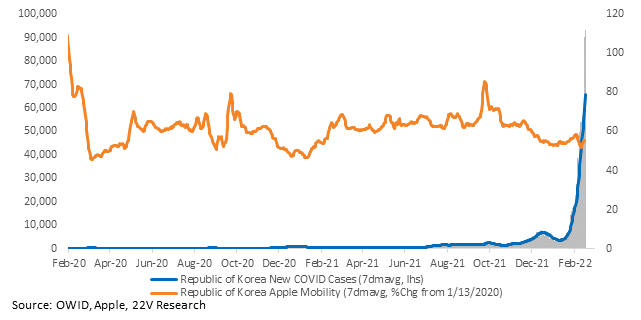
Case growth may still be in its earlier stages, but countries are still resisting restrictions. Oxford’s stringency indices remain below levels reached during previous waves. Case growth is increasing but mobility is stable. So far so good, though the situation could change if severe cases spike.
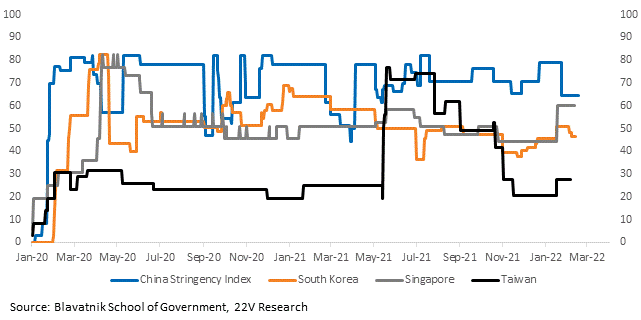
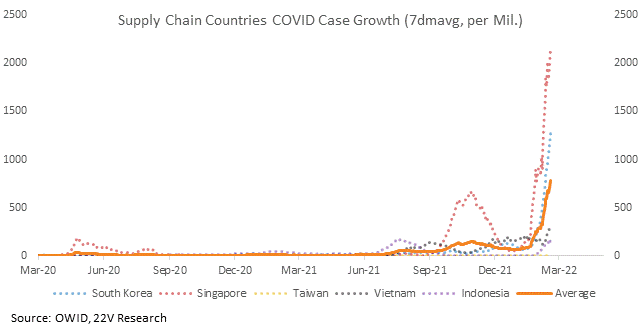
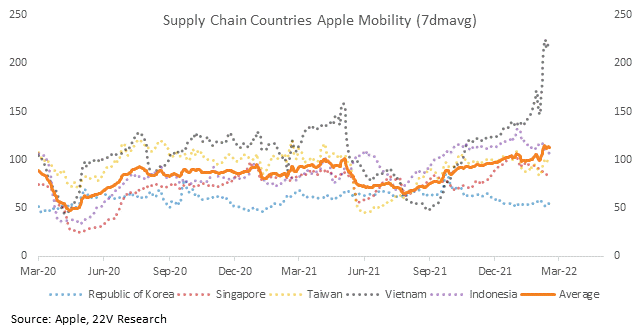
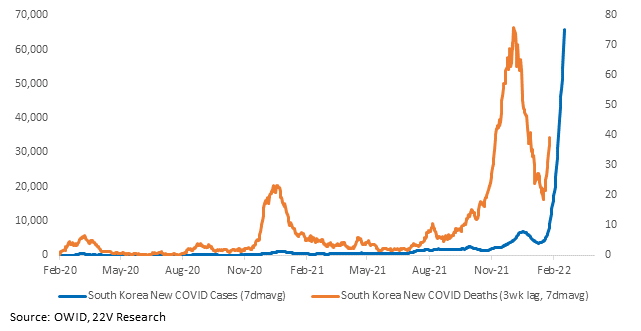
South Korea’s case growth is particularly ugly. Deaths have increased, but note daily deaths are still below 100. The extremely high booster rate helps. So far, restrictions are minimal and those that have been implemented have been met with rather vigorous resistance. These are good signs for the outlook for activity and the outlook for supply chains.
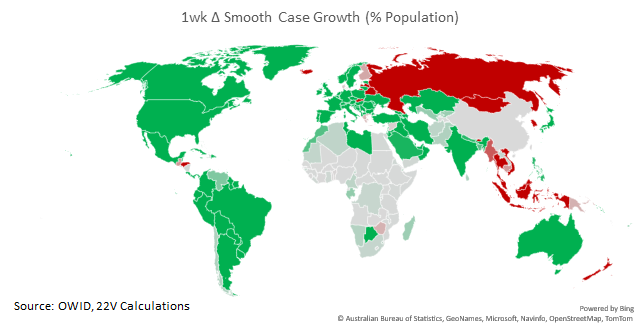
Case growth is improving almost everywhere outside of Southeast Asia.
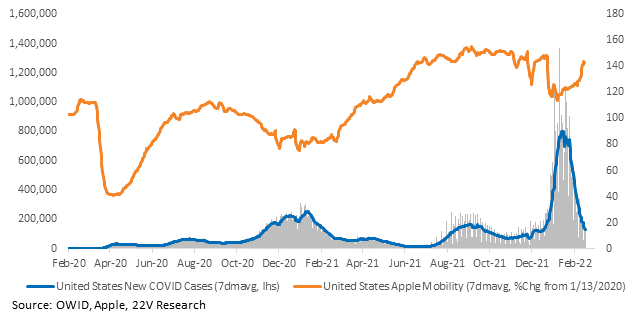
Case growth has rapidly declined in the U.S. and mobility is improving. COVID-sensitive activity is picking up too – OpenTable reservations and TSA crossings have both jumped.
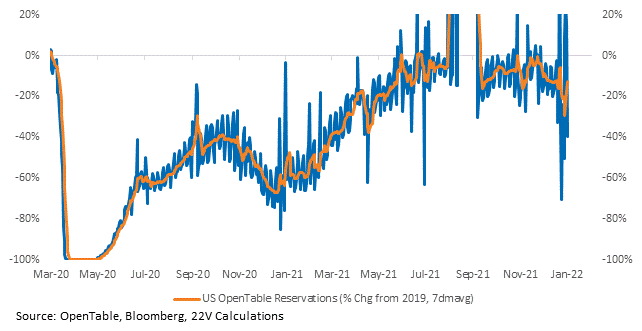
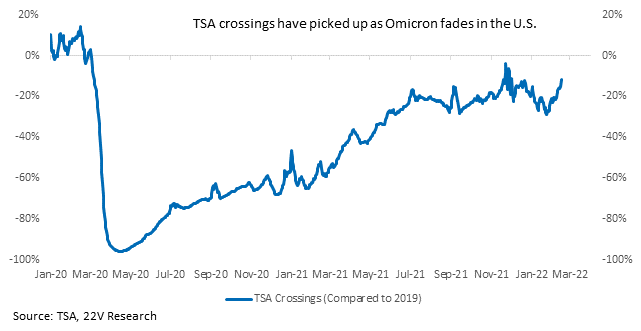
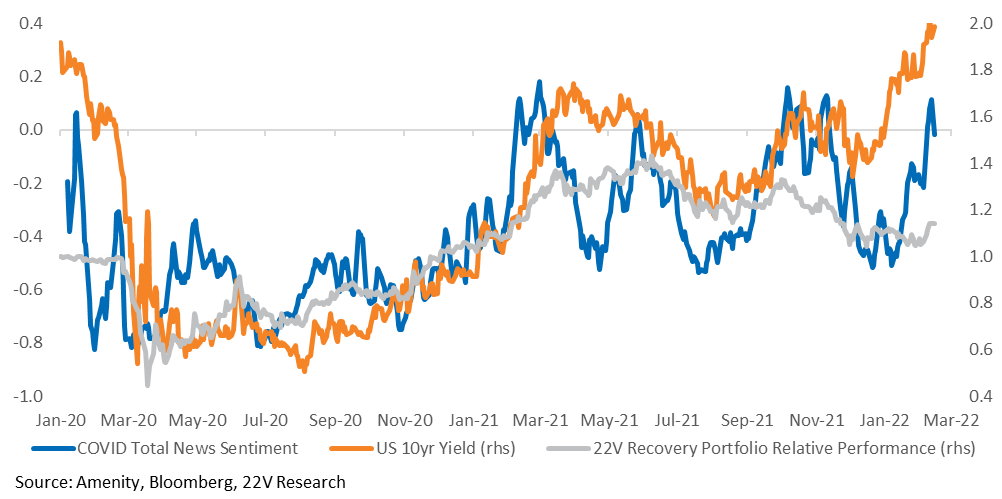
We are entering a quiet macro period, in which the Fed is unlikely to reset expectations for financial conditions. The market seems to be pricing in the Immaculate Tightening– inflation slows without the Fed having to tighten financial conditions significantly. We do not expect that to play out, especially given the pressure on core inflation from rent and wages. But short-term, there isn’t a catalyst for tighter financial conditions. The factor exposure of our Recovery Portfolio shows it’s poorly positioned for tightening financial conditions. But there’s plenty of room for it to “catch up” to improving COVID sentiment and 10yr yields short term before the Fed resets expectations.
Charts for every state and country we have data for are HERE.

