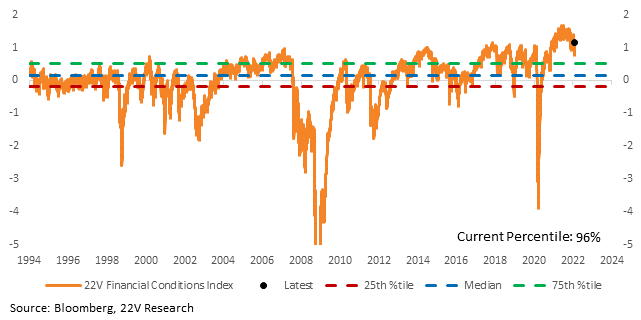
SUMMARY: Today we will try to answer if “enough” has been priced into Fed futures and financial conditions to accomplish the Fed’s goal of slowing growth / inflation. The quick answer is no. Futures markets are now pricing in an 80% chance or a 50bp rate hike in March and the 10yr Treasury increased +9bp on the day (92nd %tile move) to above 2%, but financial conditions hardly tightened yesterday, and inflation expectations (a proxy for the demand outlook) remained firm despite the sharp increase in real rates.
Financial conditions take into account the expected path of Fed tightening. If financial conditions are not tightening despite the aggressive increase in rate hike expectations, more must be done to tighten financial conditions and slow demand growth. The good news, if 50bp is not enough to tighten financial conditions, the S&P is a tough short TODAY because the Fed is unlikely to do more in the short-term. And Cyclicals can still rally relative to Defensives near term until it becomes clear that EVEN MORE has to be done to slow growth.
The longer-term problem for Cyclicals is that more tightening needs to be done.
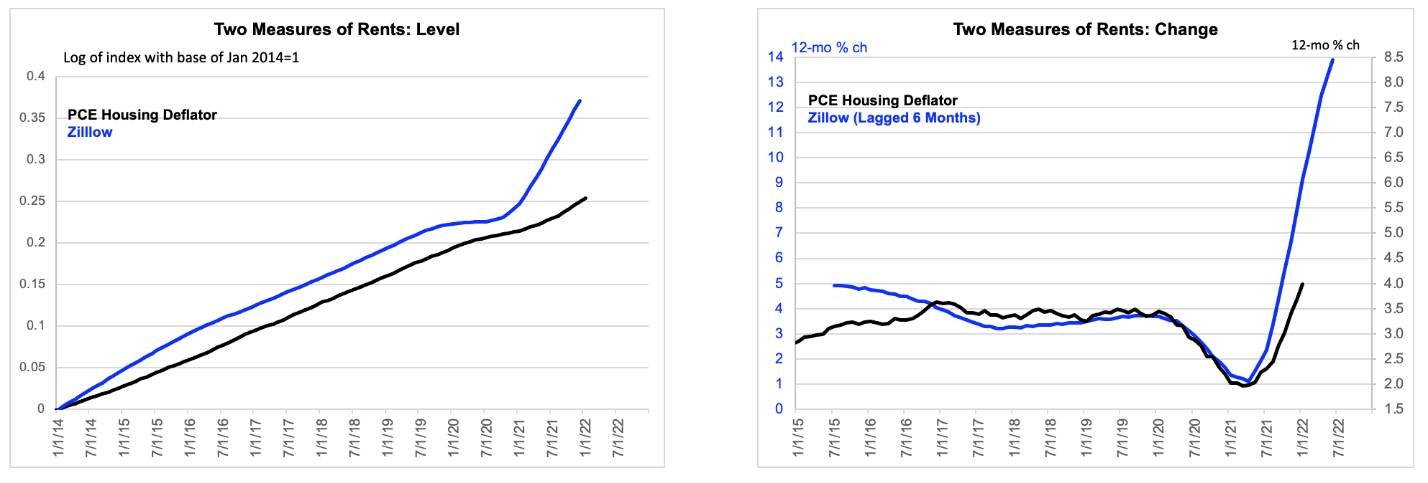
The tight housing and labor backdrop with above-trend economic growth are keeping financial conditions easy and inflation expectations stubbornly high. The rents component of the CPI didn’t even really contribute to the CPI beat yesterday, but Zillow data suggests a sharp increase going forward. As Gerard highlighted in his report, “I believe that the first derivative in rent is likely to be persistent and suspect that the second derivative is likely to do so as well. That is, if rent is quickening, do not expect it to slow meaningfully soon — and probably expect it to continue quickening.” Zillow data suggest a sharp increase in the Housing PCE Deflator.
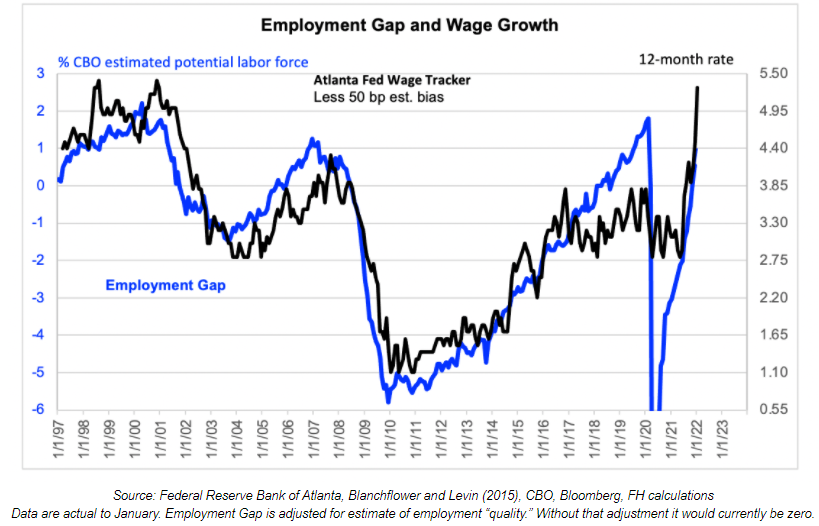
The other thing is wages. The wage growth tracker (released yesterday by the Atlanta Fed) suggest a sharp closing of the employment gap and as Gerard highlighted, “Quickening wages would seem to be a double-edged sword. They are directly inflationary… and they confirm that the labor market has tightened… The Q1 ECI is still a couple months out, but this is not a good omen for an indicator that has recently moved the Fed.”
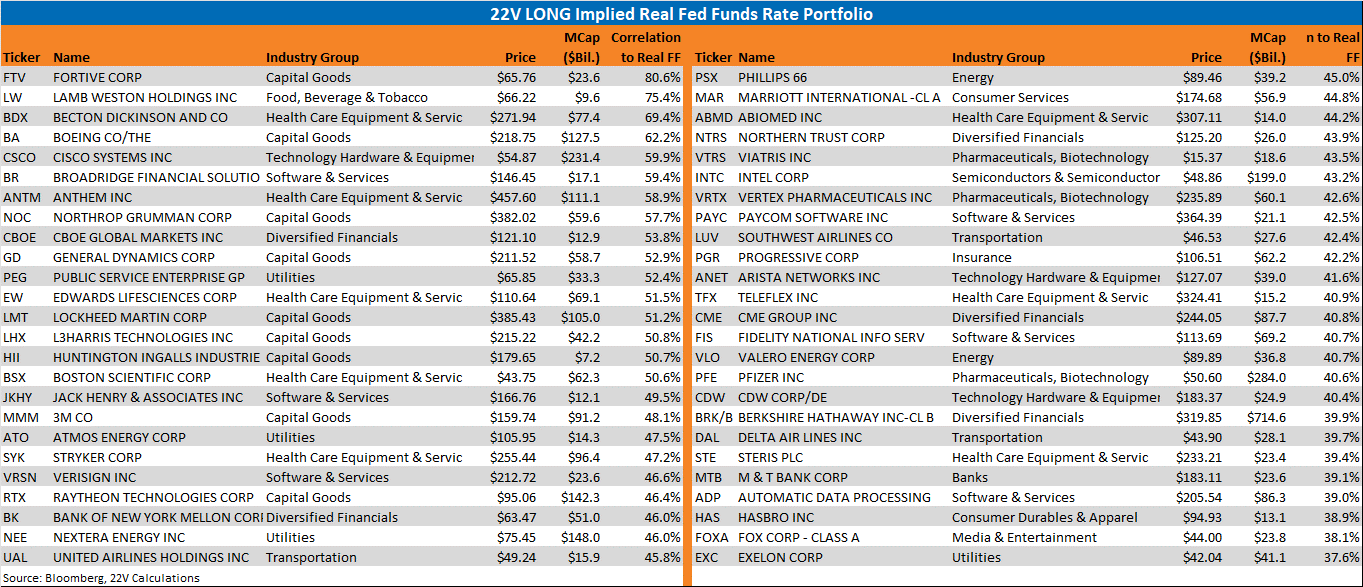
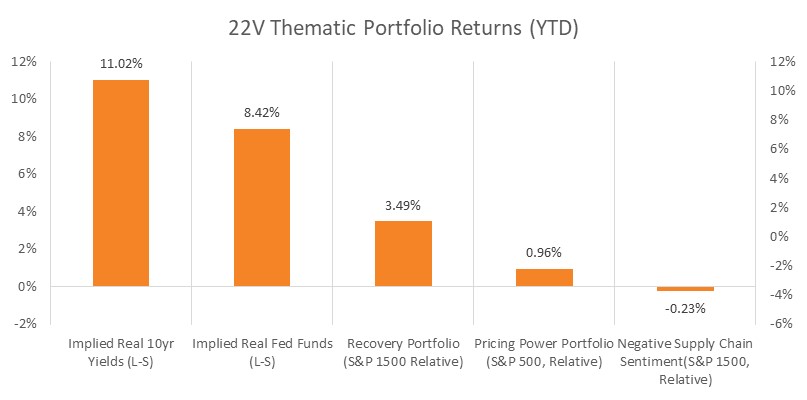
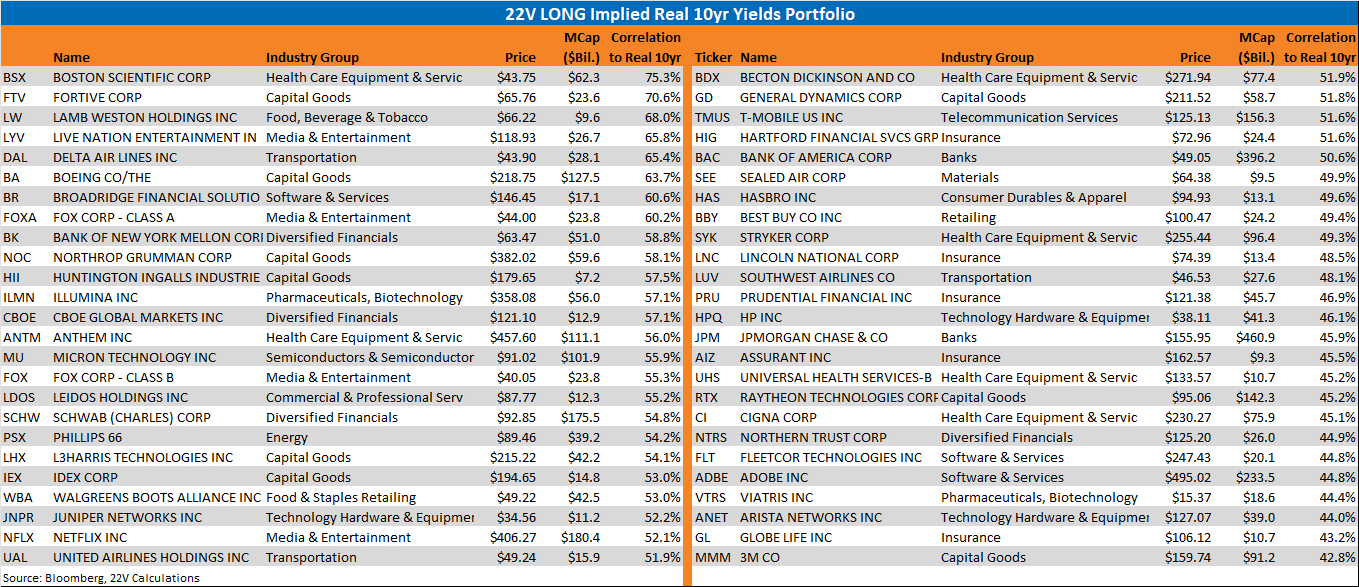
Bottom line – tight housing and labor markets and above trend economic growth suggest financial conditions need to tighten even more than they have. That means rising real yields will be a durable theme. Most of our thematic portfolios have performed well this year, but those designed to take advantage of rising real rates/yields are significantly outperforming (names in those baskets are at the end of the report). We continue to focus on the thematic portfolios as the overall market and Value vs Growth call is VERY hard right now. Constituents of all our thematic portfolios can be found HERE.
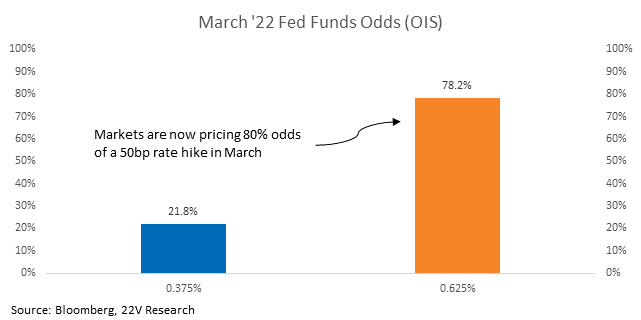
MARKET VIEWS: Yesterday’s strong CPI and wage data derailed the risk-on rally that had lifted the S&P +4.3% since Jan 21st. Strong core-CPI puts the Fed’s target for year-end inflation further away and necessitates a more aggressive pace of tightening. Today we will try to answer if “enough” has been priced into Fed futures and financial conditions to accomplish the Fed goal of slowing growth/inflation. The quick answer is no. Futures markets are now pricing in an 80% chance of a 50bp, the 10yr Treasury increased 9bp on the day (92nd %tile move) and is now sitting above 2%. At the end of December, 2% was the consensus forecast for the end of 2022.
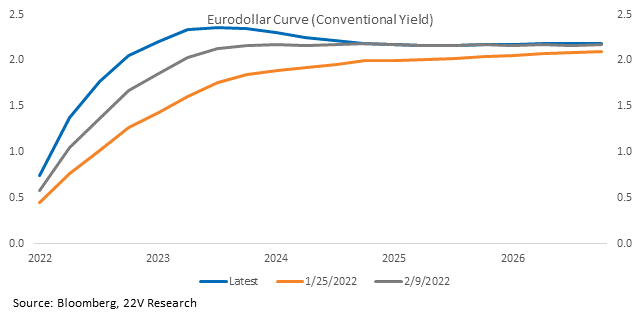
The Fed funds futures curve has shifted up meaningfully. Fed rate hike expectations within the next two years have increased dramatically. Investors are not changing estimates of the longer-term Fed funds rate, which is interesting, but a longer discussion.
We have witnessed an aggressive shift higher in rate hike expectations (50bp now basically called for in March) and financial conditions have not even tightened. They remained relatively flat yesterday despite the move wider in CDS spreads and lower in markets. Financial conditions take into account the expected path of Fed tightening. If financial conditions are not tightening, despite the aggressive increase in rate hike expectations, more has to be done to tighten financial conditions.
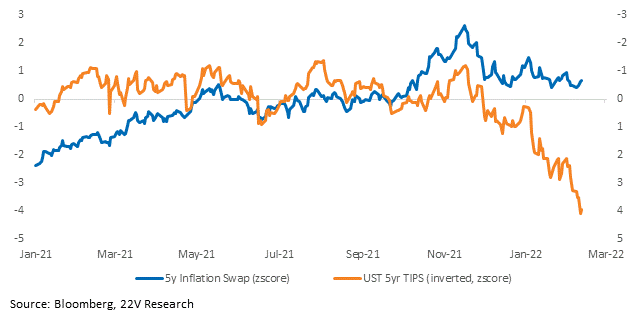
Consistent with the above point, real yields moved significantly higher yesterday, yet inflation expectations (using the 5yr inflation swap), which is a view on demand growth in the future, increased slightly. The sharp rise in real rates is not impacting the forward demand outlook much at all, which is consistent with financial conditions remaining easy.
Two things likely helped keep financial conditions easy and inflation expectations firm despite the sharp increase in rate hike expectations: 1) The CPI came in hotter than expected and it beat across the board, yet rents have not really contributed yet. As Gerard noted in his report, “I believe that the first derivative in rent is likely to be persistent and suspect that the second derivative is likely to do so as well. That is, if rent is quickening, do not expect it to slow meaningfully soon — and probably expect it to continue quickening.” Zillow data suggest a sharp increase in the Housing PCE Deflator.
We also got the Atlanta Fed’s wage growth tracker yesterday and sticky CPI readings. Wage growth was strong and is associated with rising “Sticky” CPI. The wage growth tracker suggests a sharp closing of the employment gap and as Gerard highlighted, “Quickening wages would seem to be a double-edged sword. They are directly inflationary… and they confirm that the labor market has tightened… The Q1 ECI is still a couple months out, but this is not a good omen for an indicator that has recently moved the Fed.”
Bottom line – the tight housing and labor markets and the trends in the economy suggest more aggressive actions from the Fed will be needed to tighten financial conditions. That means rising real yields will be a durable theme. Other micro-themes are also important: Pricing Power should become more important as inflation eases and Negative Supply Chain Sentiment should improve as Omicron fades and COVID restrictions are lifted. Most of our thematic portfolios have performed well this year, but those designed to take advantage of rising real rates/yields are significantly outperforming (names in those baskets are at the end of the report). We continue to focus on the thematic portfolios as the overall market and Value vs Growth call is VERY hard right now. Constituents of ALL our portfolios can be found HERE.

Long implied real yields…
Long implied real fed funds rate…