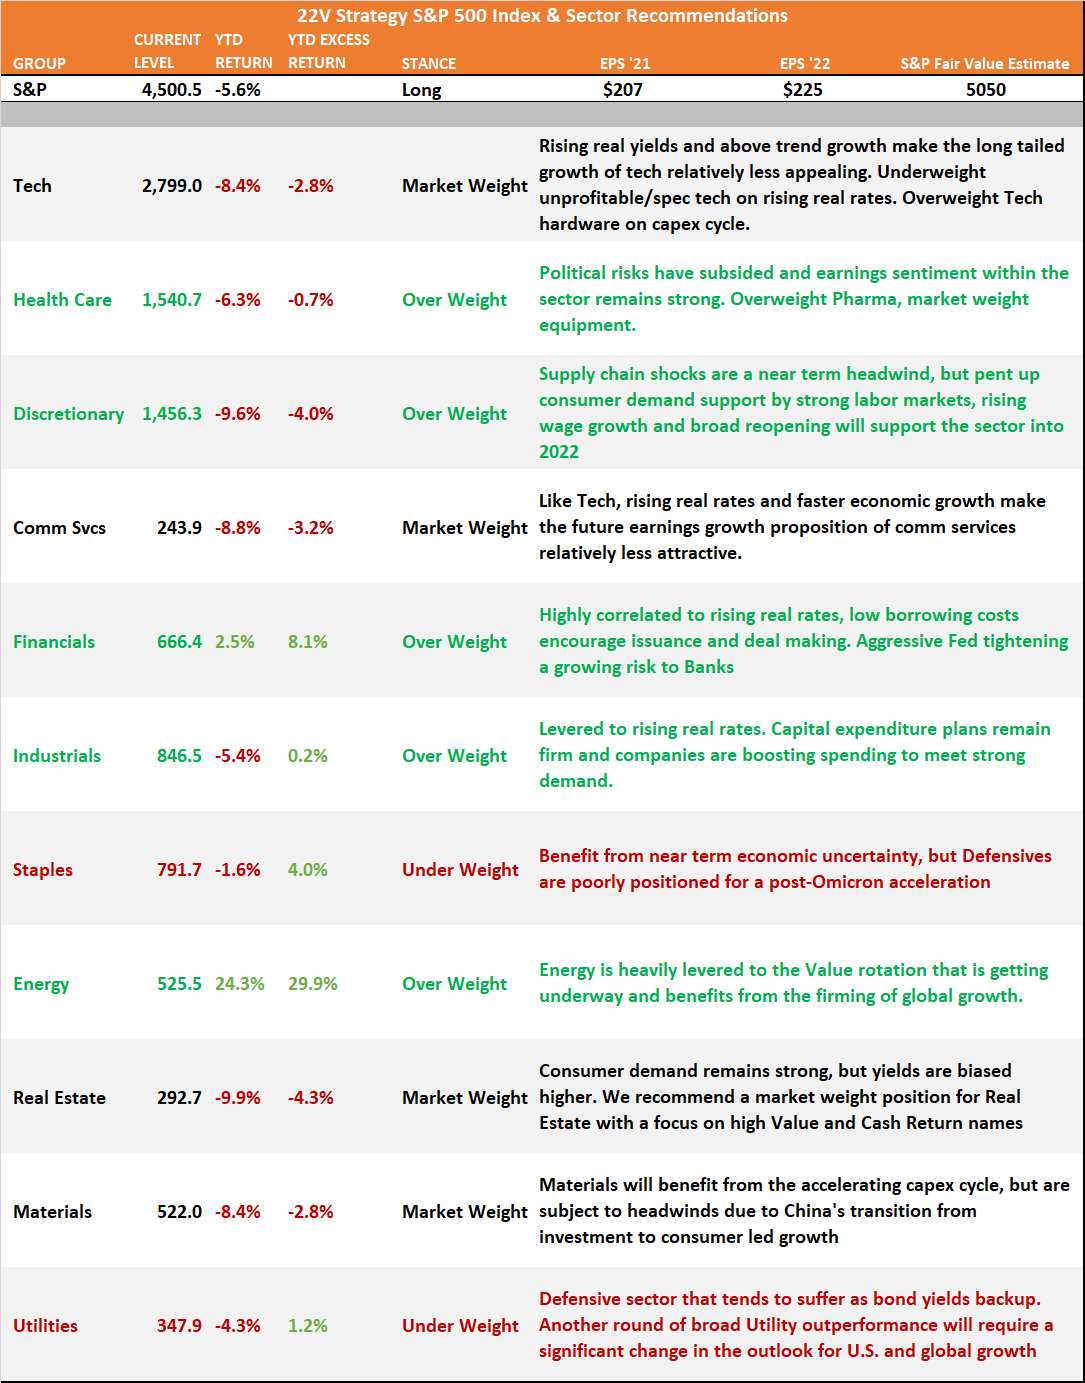
SUMMARY: Long rates are moving higher globally again as investors focus on just about all global central banks having a hawkish pivot. For the first half of last week factor returns aligned to tightening financial conditions while back half returns were most consistent with rising real yields. In the near term, rising real yields and a reacceleration in economic growth as Omicron fades (likely) is not a terrible combination for the market (Cyclicals should bounce) and Strong Value, high cash return, and relatively stable earnings insulate mega cap Tech from the headwinds of rising yields AND tightening financial conditions. With negativity toward Mega caps unusually high, expect some near-term stabilization.
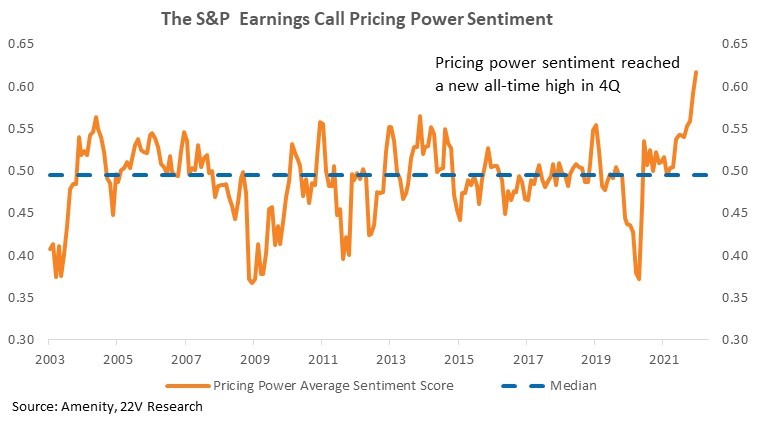
Unfortunately, it looks like it will be tough to avoid a sharp tightening of financial conditions longer term. Economic growth is firm, labor markets are tight, rents are biased higher and with about half of companies reporting, management sentiment toward pricing power has reached a new all-time high in 4Q. The Fed wants to reduce that pricing power to slow inflation and if the economy remains firm and labor markets tight, a sharp increase in financial conditions will be required for the Fed to accomplish its goals of slowing growth to slow inflation. This will become more obvious to investors in March/April as economic readings firm.
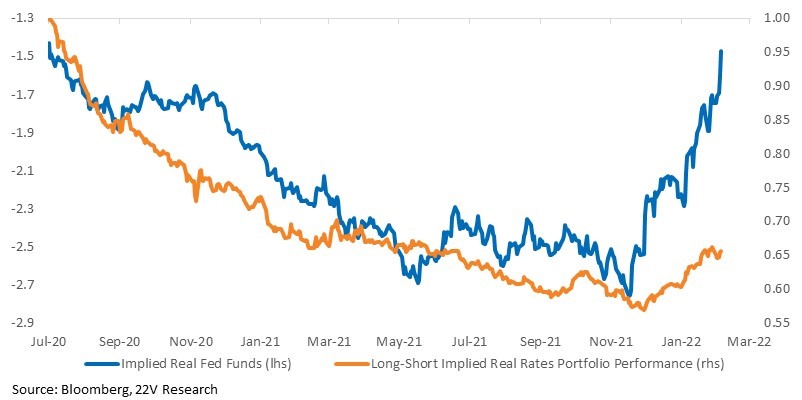
Our implied real fed funds portfolio has significantly outperformed MTD but has considerably lagged the massive increase in expected fed funds. Longer term, stay long companies that benefit from increase in the real fed funds rate (happy to send the list of names).

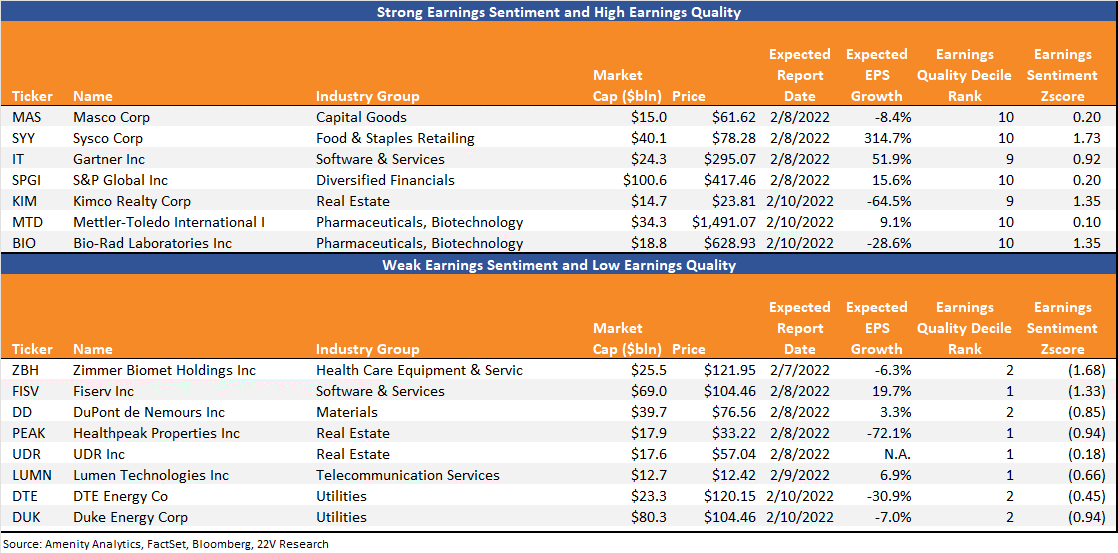
Earnings season has been treacherous from a volatility point of view, so we include a table that contains the stocks expected to report this week that have the best Earnings Sentiment and Earnings Quality rankings (stable and higher odds of beating earnings). The second basket is the short end; those names with the worst sentiment and Earnings Quality ratings. Email us for a complete ranking of all stocks reporting this week.
FYI on what earnings sentiment is: Earnings sentiment rankings are correlated with earnings surprises. In other words, companies with high earning sentiment scores tend to beat earnings expectations while those with lower scores tend to miss more often
Full report below…
MARKET VIEWS: During the first half of last week factor returns aligned to tightening financial conditions while back half returns were more consistent with rising real yields. Rising yields is now a global story with Asia, European, and US long rates moving significantly higher last week. They are up again overnight. In the near term, rising real yields and a reacceleration in economic growth as Omicron fades (likely) is not a terrible combination for risk assets. We expect Cyclicals to rebound some. In addition, and as mentioned in a Quant report this morning, Strong Value, high cash return, and relatively stable earnings insulate mega cap Tech from the headwinds of rising yields AND tightening Financial conditions. With negativity toward Mega caps unusually high, expect some near-term stabilization.
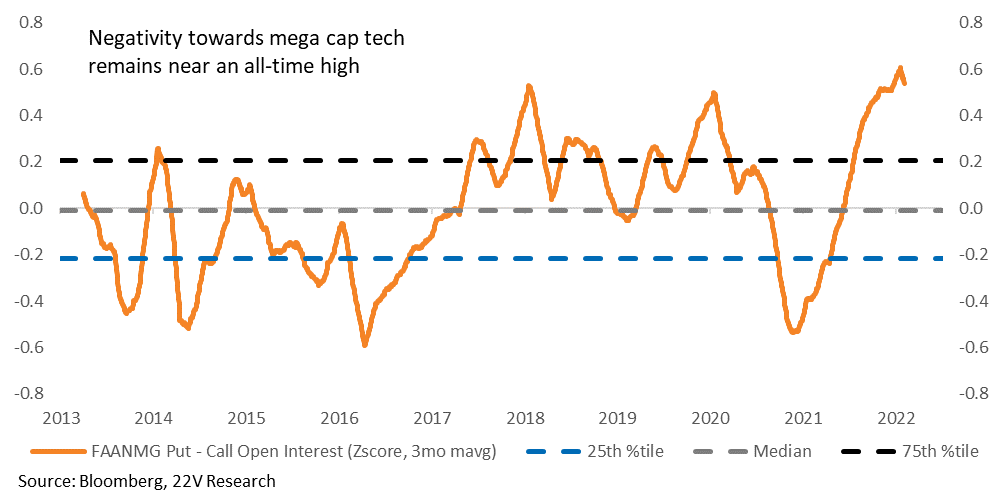
The above suggest a near term stabilization of the overall market. When investors again start pricing in a sharp tightening of financial conditions, market downside risk will increase, and Cyclicals will suffer. Unfortunately, it looks more likely a sharp tightening of financial conditions will be needed. Economic growth is firm, labor markets are tight, rents are biased higher and with more than half of companies reported, management sentiment toward pricing power has reached a new all-time high in 4Q. The Fed wants to reduce that pricing power to slow inflation and if the economy remains firm and labor markets tight, a sharp increase in financial conditions will be required. That outcome will become more obvious to investors in March/April.
Fed rate hike expectations moved sharply higher as investors internalized what the firm economic backdrop and consistent inflation impulse means for monetary policy. Our implied real fed funds portfolio has significantly outperformed MTD but has lagged the massive increase in expected fed funds. Longer term, stay long companies that benefit from increases in the real fed funds rate.
Earnings Season Has Been Treacherous: To help avoid earnings misses and negative guidance, below are the stocks with the best earnings sentiment (Earnings sentiment rankings are correlated with earnings surprises. In other words, companies with high earning sentiment scores tend to beat earnings expectations while those with lower scores miss more often.) scores at the end of last reporting season that also have the highest Earnings Quality rankings. These are names that are well positioned leading into earnings reporting season. The table below contains the stocks expected to report next week that have the best Earnings Sentiment and Earnings Quality rankings. The second basket is the short end; those names with the worst sentiment and Earnings Quality ratings. Email us for a complete ranking of all stocks reporting this week.
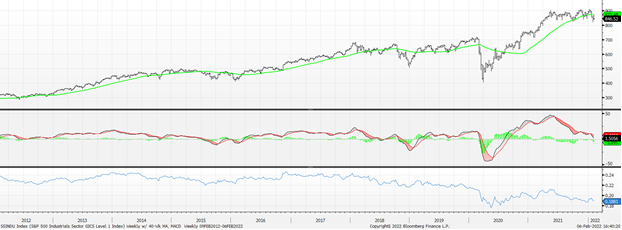
According to John Roque Market weakness is now infecting Industrials and its Technical Score has weakened to 1 with 63% of the stocks in the sector having weak to bearish scores. The S&P Industrials (top panel) is now below its cresting 40-Week Moving Average, its weekly MACD (middle panel) is close to negative territory, and relative to the S&P 500 (bottom panel) it is close to testing its 2020 lows.
Sector Update: The S&P continued to stage a modest rebound from its Jan 24th low, gaining 1.5% last week. Cyclicals led the market higher with some notable exceptions. Materials were down slightly on the week, and Comm Services was the worst-performing sector. Excluding FB’s -23% decline, Comm Services would have been higher last week. However, removing AMZN’s 9.5% rally would have left Discretionary up less than 20bp. Mega cap names continue to exert significant influence over the overall market level. But a little over 2/3rds of S&P names posted absolute gains last week. Earnings remained strong, with 4Q index growth revised up to 28% and full-year 2021 EPS estimates rising to $205.9 (we expect they will end the season around $207). Factor returns were skewed toward risk-on but were trendless with respect to major macro themes. The first half of the week, factor returns aligned to tightening financial conditions while back half returns were more consistent with rising real yields. Energy was the best performing sector again, illustrating that factor profiles (Energy is heavily exposed to both Value AND Earnings Turbulence) are less important in highly correlated, macro-driven sectors. While oil prices are on the rise, Energy remains an overweight.