
Our entire repository of COVID charts is HERE.
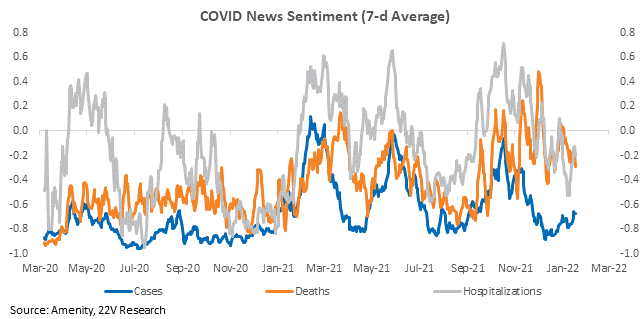
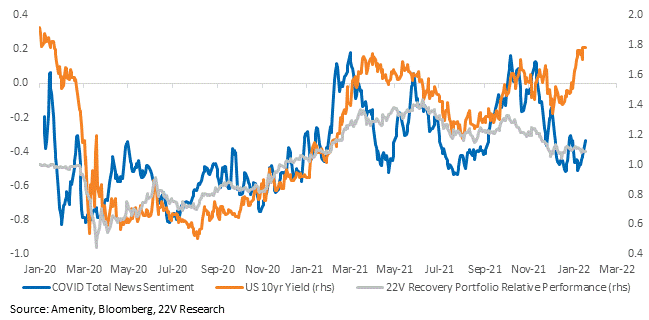
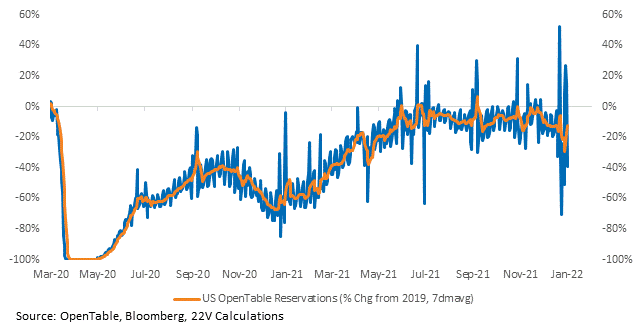
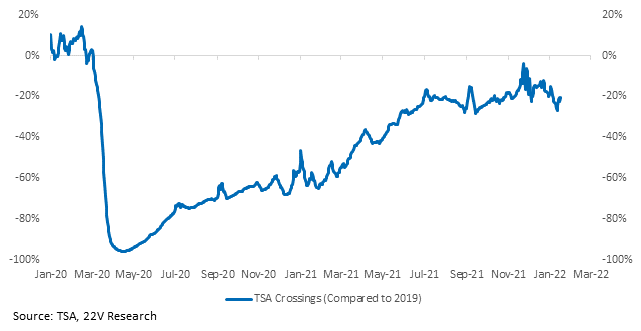
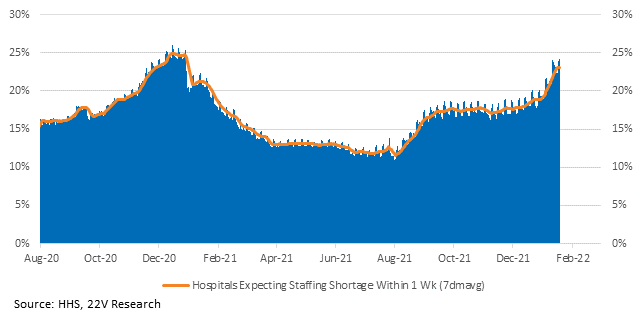
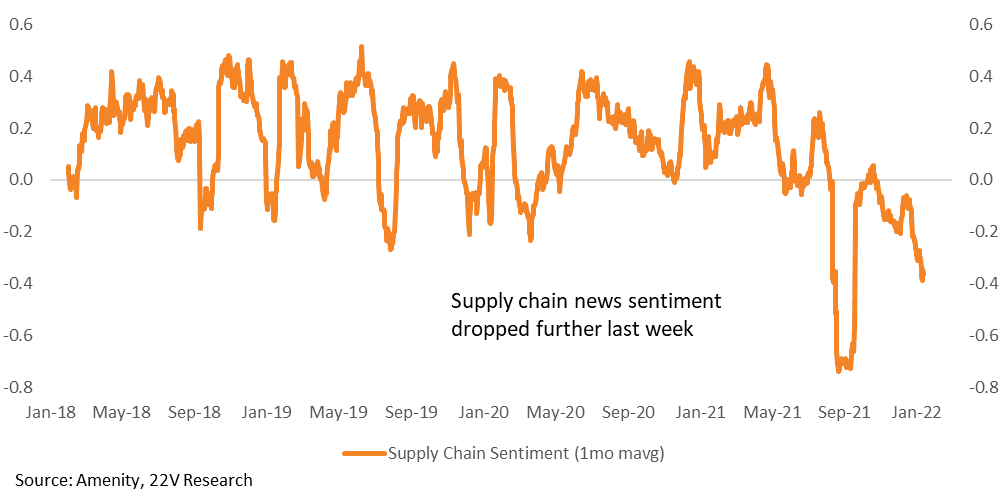
COVID sentiment is volatile; death sentiment is falling while hospitalization and case sentiment are improving. Total sentiment is better but still significantly worse than pre-Omicron. Languishing sentiment is a headwind to our Recovery Portfolio, which has not broken out since the Omicron wave began in November. Investors need more confidence in demand for COVID-sensitive industries like travel and dining (charts 3 and 4) and in restrictions. The threat of restrictions will remain as long as staffing shortages are making headlines (chart 5). Reopening names are likely also impacted by China’s commitment to zero-COVID, worsening supply chain sentiment (chart 6), and tighter financial conditions.
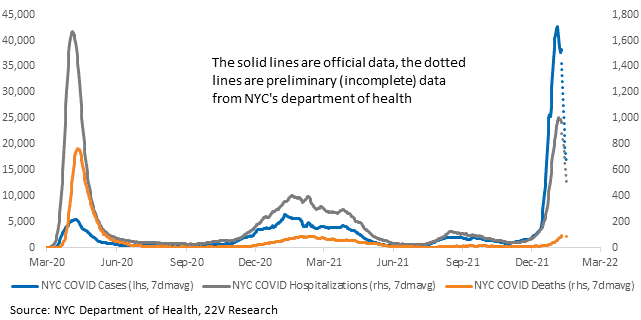
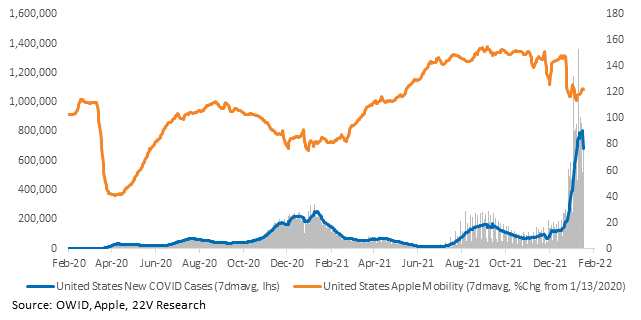
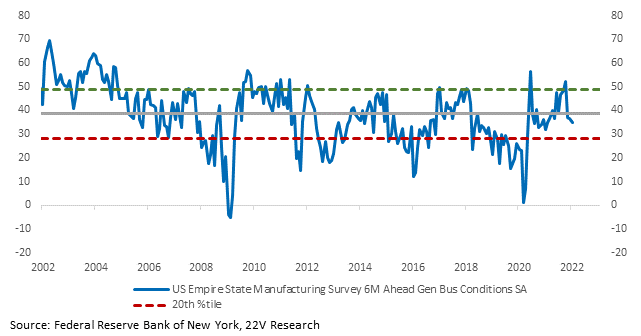
There is a holiday reporting lag that may be interfering with the data in the U.S. So, we are reluctant to draw conclusions from the drop in the 7dmavg of country-aggregate case growth. We will take a deeper look at trends by state later this week. We do have encouraging official data from NYC; case growth and hospitalizations look to have peaked. Deaths have stayed low despite record case growth, which is an encouraging sign for activity. Granted, activity in NY dropped during Omicron, but low severity is encouraging for a rebound in activity. Empire manufacturing data showed Omicron’s disruption but also indicates expectations for future activity were not similarly disrupted. Also, not every state will react like NY.

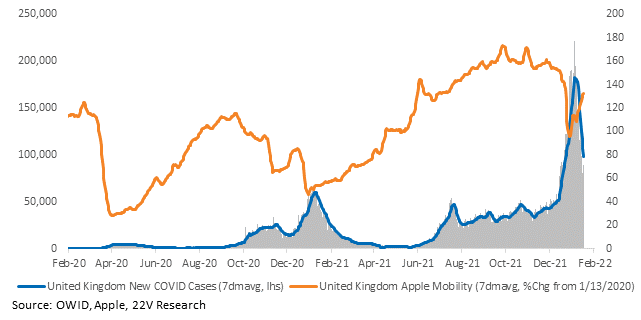
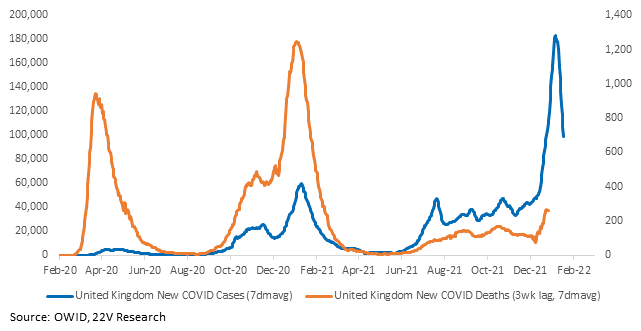
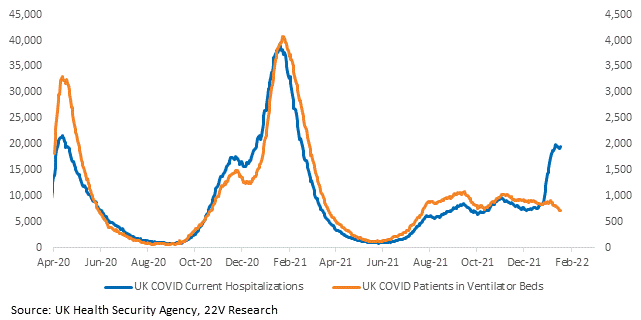
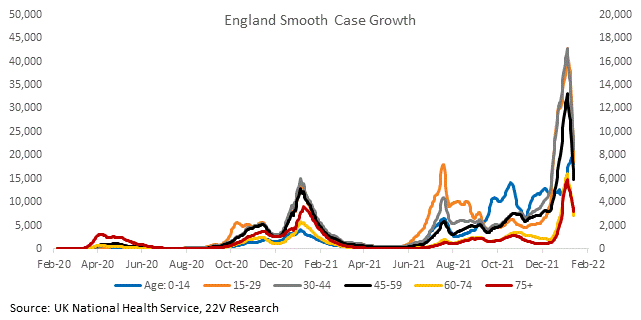
The UK’s data is reassuring. Case growth is rapidly decelerating and mobility recovering. Deaths have stayed low. Patients on ventilators diverged from hospitalizations. And case growth rates are lower across age cohorts.
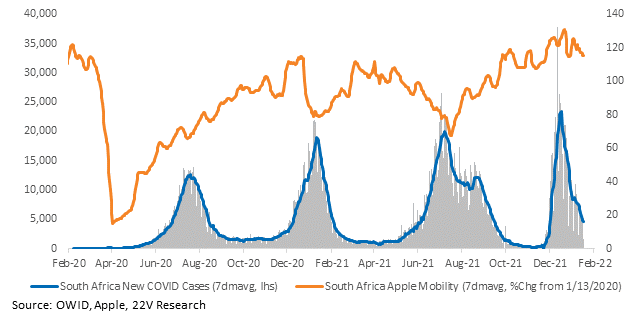
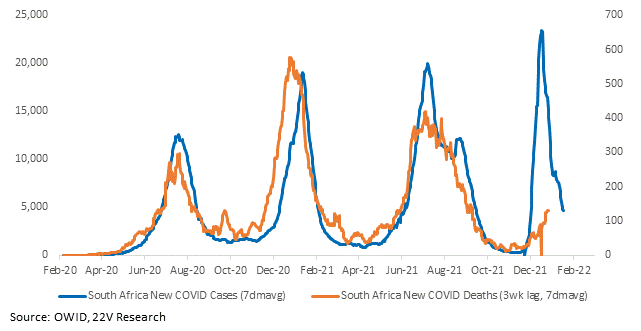
South Africa’s continued improvement is reassuring as well. Deaths have stayed low here too.
Charts for every state and country we have data for are HERE.

