
Our entire repository of COVID charts is HERE.
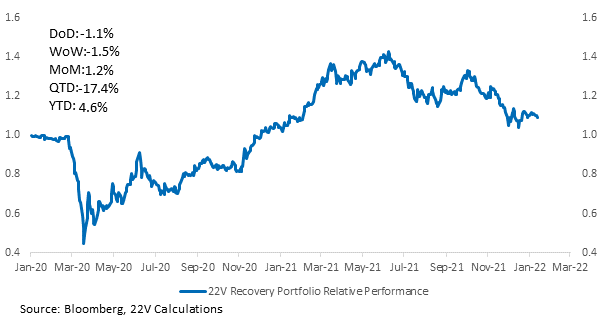
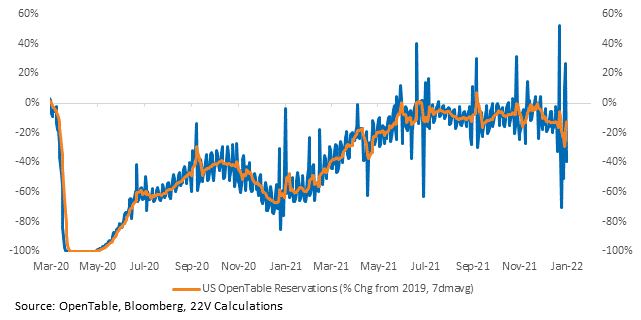
Our Recovery Portfolio has been underperforming since Omicron was identified and labeled a variant of concern in November. As we discussed yesterday, deteriorating sentiment is a significant headwind to COVID-sensitive industries like travel and restaurants. Investors are concerned with softening demand and potential restrictions. OpenTable data shows in-restaurant traffic has been declining throughout Omicron. TSA crossings have failed to recover to pre-pandemic levels and have recently dropped. Omicron is not a demand shock but is a headwind to certain industries; a peak in case growth and recovery in sentiment would be welcome relief. Reopening trades might also be suffering from the Fed’s intent to tighten financial conditions (because they have higher debt levels) and slow demand growth.

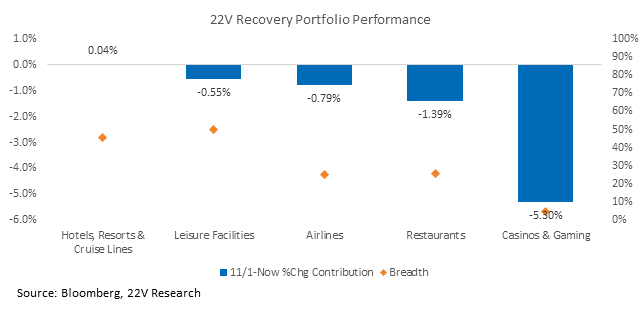
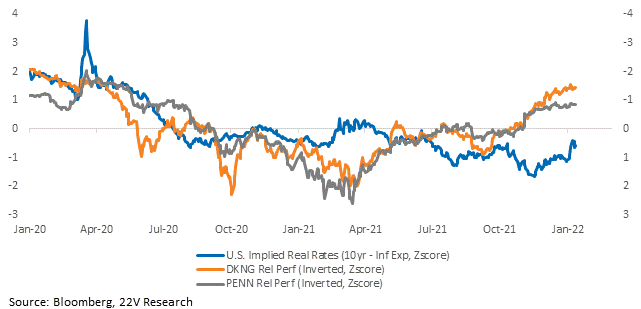
Casinos & Gaming has had the worst contribution to the total return of the portfolio. More speculative names within the industry group are being weighed down by higher implied real rates. Implied real rates will continue to increase, creating a longer-term headwind for the Portfolio through their influence on the industry group.
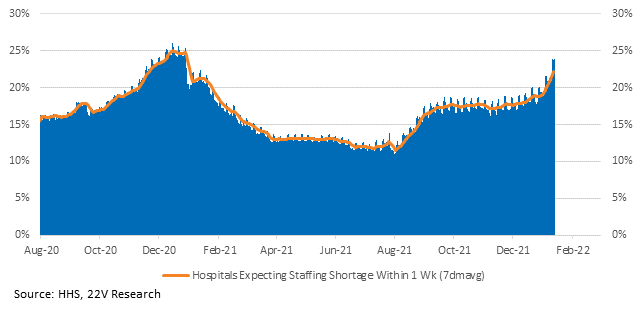
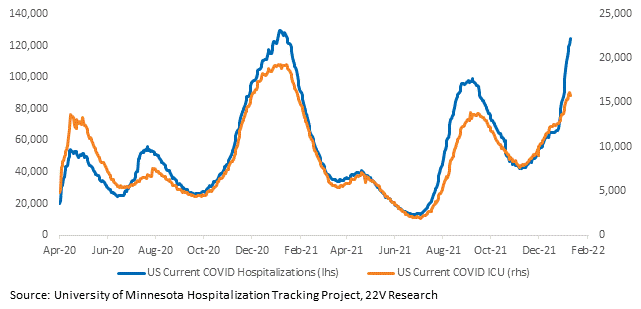
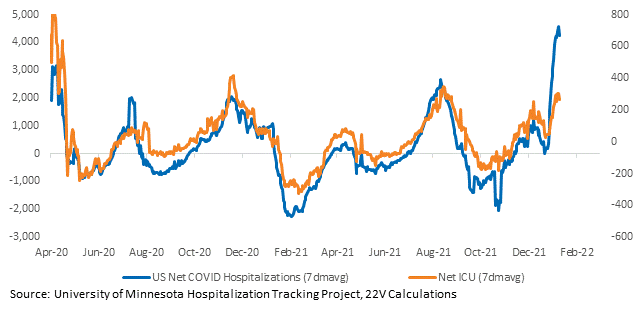
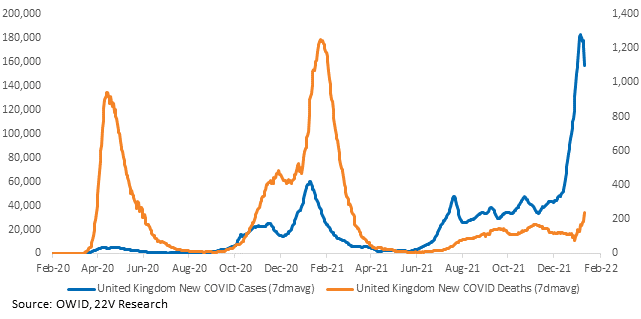
Staffing shortages have to stop making headlines before the specter of restrictions can ease. But the percentage of hospitals reporting an imminent critical staffing crunch continues to increase. Hospitalizations are at highs too, but net ICU admissions are lagging hospitalizations. Fewer patients are in critical condition. Deaths have stayed low in the UK, which is a very encouraging sign for severity here in the U.S.
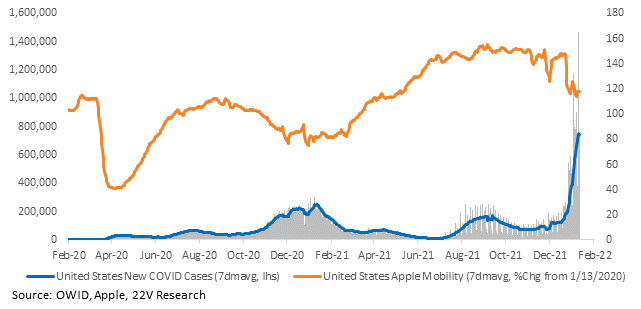
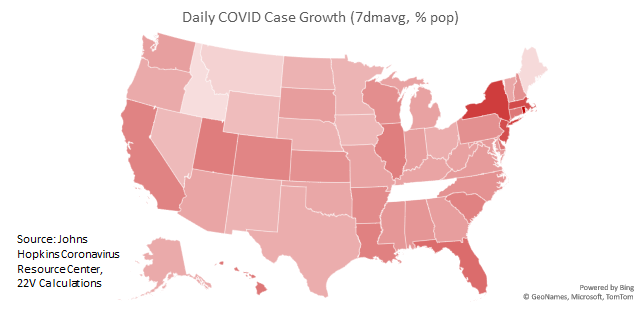
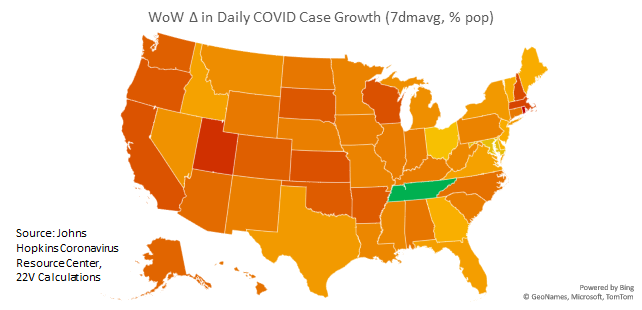
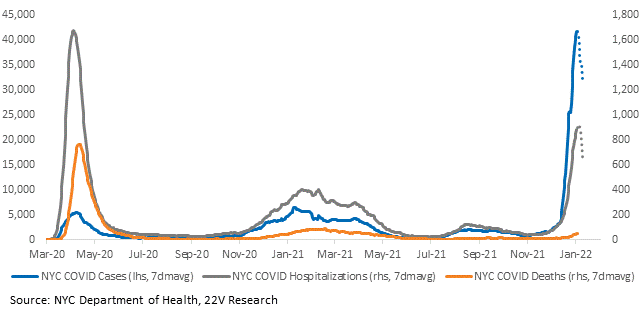
Case growth in the U.S. continues to increase across almost every state. FYI, the official data from NYC still has not indicated a peak. Preliminary data, which is subject to large revisions, looks better.
Charts for every state and country we have data for are HERE.

