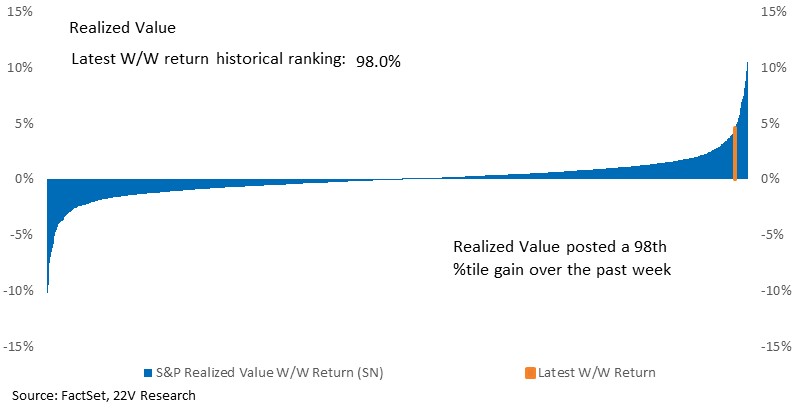
SUMMARY: The next week is about payrolls (today) and CPI (next Wednesday). Participation is the critical metric in the payroll report and Rents in the CPI report. A slight increase in participation today and a strong payroll number will not change the Fed outlook, but it could provide some short-term relief for Tech. The way to think about it, if participation rates are increasing economic growth will not need to weaken significantly (1%ish or below) for the Fed to accomplish its goal of moving inflation down to 2% over time. Over the past week, Realized Value has posted a 98th %tile gain…it is not reasonable to expect Value to keep outperforming like it has. That is why just a small uptick in participation today should lead to some relief in Growth.
If participation is flat/lower (we are focused on prime age participation rate) and the unemployment rate falls more than expected, a faster pace of policy tightening may be necessary. All things equal, that would be bad news for tech.
The bottom line: Investors will need to be comfortable that participation can go back to pre-pandemic trends, not just the CBO’s estimate, to become less worried about the Fed tightening financial conditions more aggressively. If that happens, there will be 3 or 4 rate hikes this year, economic growth will remain strong and inflation lower. A good outcome. Unfortunately, we won’t be able to tell how participation is trending, relative to the pre-pandemic trend, for some time. That is why today is about short-term trading opportunities (if you’re into that sort of thing) and not figuring out a change of trend.
FYI: Most economist have labor force participation going back to the CBO’s forecast of potential and assuming ~3.3% econ growth and 1 ¼ quarter productivity estimates (which could be too low), the unemployment gap would close by the end of 2022 according to 22V economist Gerard MacDonell (who has been right on the Fed/inflation). For investors to get comfortable that the Fed doesn’t need to tighten financial conditions significantly, we would like to see participation trend toward pre-pandemic levels, rents rise less than Zillow data implies and for productivity to be stronger than ~1.25.
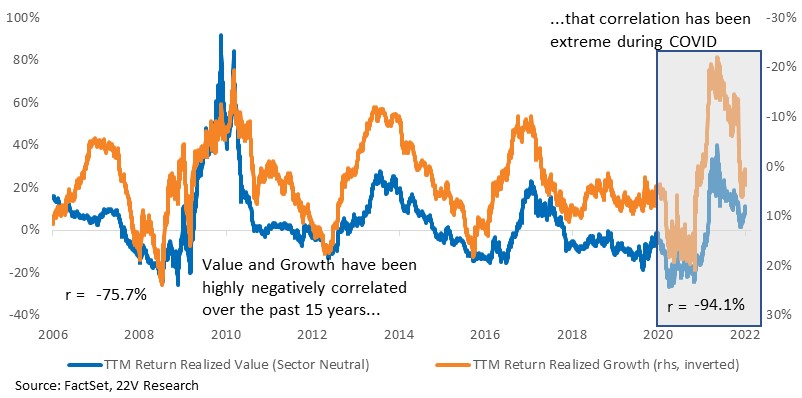
Value & Real Yields: The return correlation between Value and Growth has been nearly perfectly negative since the start of COVID and real rates have further to climb to get to pre-pandemic levels. Its unlikely Value will maintain its recent outperformance, but Value tailwinds remain strong assuming real yields continue to move higher. Which they should unless markets start to price in the Fed crushing growth.

MARKET VIEWS: The next week is about payroll (today) and CPI (next Wednesday) and if those readings increase or decrease the Fed’s tightening bias. Participation is the critical metric in the payroll report and Rents in the CPI report. A slight increase in participation today and a strong payroll number will not change the Fed outlook, but it could provide some short-term relief for Tech. The way to think about it, if participation rates are increasing it implies economic growth does not need to weaken significantly (1%ish or below) for the Fed to accomplish its goal of moving inflation down to 2% over time. The higher participation rates go, the better. If participation is flat/lower (we are focused on prime age participation rate) and the unemployment rate falls more than expected, that would reinforce the trends from this past week. All things equal that would be bad for tech.
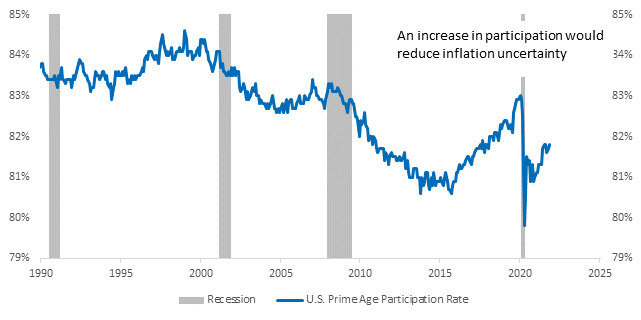
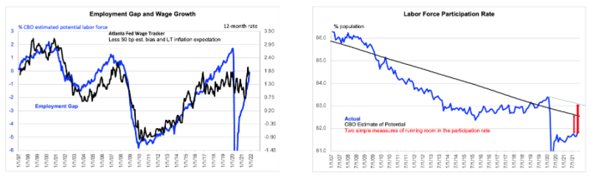
Keep in mind that most economist have labor force participation going back to the CBO forecast of potential (grey line in the right-hand chart below) and assuming 3.3% ish econ growth and 1 ¼ quarter productivity estimates (which could be too low), the unemployment gap would close by the end of 2022 according to Gerard. That means higher wages (bottom left chart) and the Fed tightening faster than markets are currently pricing. The bottom line: investors will need to be comfortable that participation can go back to pre-pandemic trends, not just the CBO’s estimate of participation, to become less worried about the Fed crushing growth. If that happens, you get 3/4 rate hikes this year, strong econ growth and inflation moves lower. A good outcome. Unfortunately, we won’t be able to tell how participation is trending, relative to the pre pandemic trend, for some time.
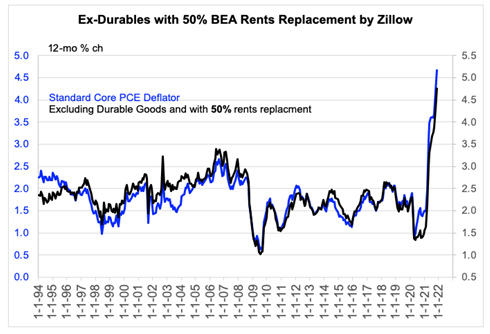
On CPI and rents, which is the other part of this, Gerard’s inflation estimates are slightly above the Fed’s, but skewing higher. The signal from Zillow’s data is becoming increasingly alarming, but it is tough to map that over to Owners Equivalent Rents (OER). Gerard blends in the Zillow data, which shows rents inflation around 8%. That would map to a 4.25% inflation rate. For the Fed to be comfortable that they don’t need to tighten financial conditions significantly, we would like to see participation trend to CBO estimates and then to pre pandemic levels, rents come in much less than Zillow implies and productivity to be stronger.
VALUE VS GROWTH: Value factors have rallied over the past few weeks as investors have embraced the Fed policy pivot and implied real yields increased sharply. Value is supported by the Fed’s goal of diving real yields. Real yields still have a long way to go to get back to pre-pandemic levels, which seems like a reasonable base case given the underlying strength in the economy and high inflation.
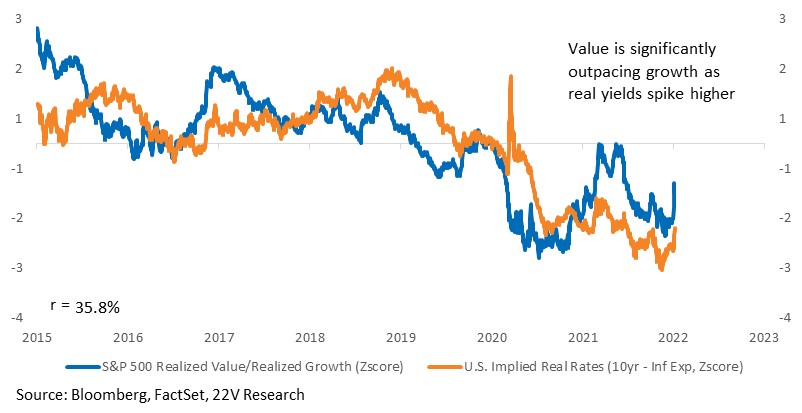
The magnitude of the recent moved has been extreme. Over the past week Realized Value has posted a 98th %tile gain…it is not reasonable to expect Value to keep outperforming like it has. That is why just a small uptick in participation today should lead to some relief in Growth.
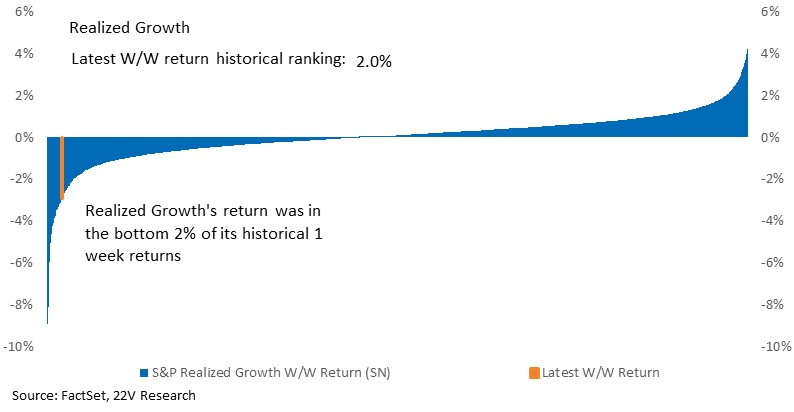
The decline in Realized Growth is in its 2nd %tile.
The return correlation between Value and Growth has been nearly perfectly negative since the start of COVID. While real rates have further to climb and the Fed maintains its tightening bias, pull backs in Value stocks are buying opportunities. Especially as/if the pandemic fades as an issue.