SUMMARY: Investors are likely to wait and see how bad the actual Omicron wave is before reacting again (positively or negatively). That should mean some sideways chop in Reopening names after their large rebound. Vaccine efficacy is important but determining the R0 will help people game out if hospitals will become overrun or not despite very low severity (because of a global surge). That is why the Omicron bears are so focused on R0. We won’t have more concrete information on this for a few weeks.
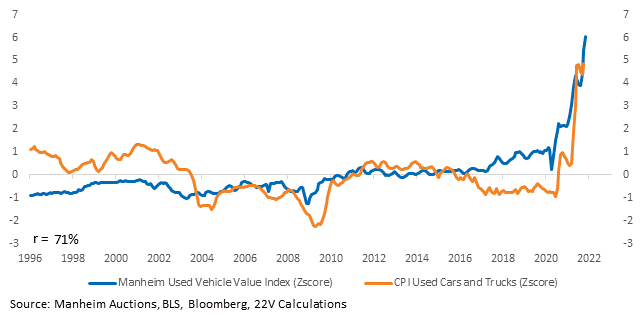
Focus will be on CPI and the Fed over the next week. CPI has upside risk given the increase in Manheim used car prices again in October. People know this, but FYI. Markets are pricing in roughly 3 hikes next year at this point, given Larry Summers, former NY Fed President Bill Dudley and the entire sell side shift to a hawkish stance (quantitative tightening is now being talked about in 1Q23), 50-75bp of hikes next year will likely be viewed on the dovish side.
A few things people are getting wrong on the Fed rate hike path. In an environment of Core PCE still ending 2022 above 2.5%, monetary policy will still be accommodative (real rates deeply negative) under just about all scenarios. Paraphrasing Jason Furman, who was well ahead of the shift in Fed policy and some say helped cause the shift, monetary policy should continue to be expansionary, just not extremely so. Think about it in these terms, when the Fed started tightening in last cycle, core PCE was 1.6%-1.7%. Today it is 3.6% and wages are MUCH stronger.

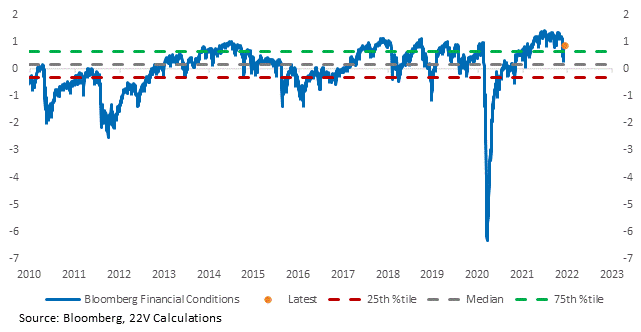
At the start of the last tightening cycle, real implied 10yr yields were +150bp higher than today. Yep, you read that correct, +150bp. Unless markets price in a Fed mistake (it could happen, but why price that in now?) financial conditions will remain easy. Despite the aggressive shift to hawkish forecasts by the sell side and the Fed pivot, financial conditions have remained easy. Easy financial conditions support Cyclicals.
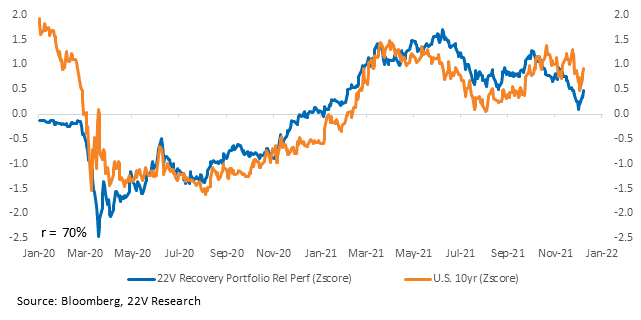
The counter to the support of Cyclical arguments is the yield curve. We looked at the spread between the recent move in the 2yr relative to the 10yr (in % terms) and it is in the 100th %tile historically. We believe the 2yr yield is going higher, but unless you can make a firm call that a Fed mistake is coming, expect some upward pressure on 10yr yields going forward. Also, the major overhang on the 10yr has been COVID, which is why the correlation between the 10yr and Reopening has been high. If COVID impacts fade, 10yr yields are going higher and yield curve relief is coming. Just as the entire world is calling for aggressive yield curve flattening. That will support Banks and Defensives will suffer relative.
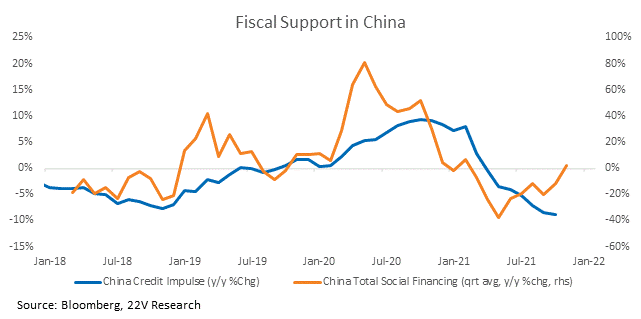
China social financing has bottomed, chart in the full report below.
MARKET VIEWS: Omicron is a major swing factors in markets right now, but investors are likely to wait and see how bad the actual Omicron wave is before reacting again (positive or negative). So we likely have some sideways chop in reopening names after the large move off the lows. Efficacy is important but figuring out how high the R0 is will help people game out if hospitals will become swamped or not despite very low severity (because of a global surge in cases in a very short period of time). That is why the Omicron bears are so focused on R0 and we won’t have more concrete information on this for a while. The focus is likely to be on CPI and the Fed and we cover that today. The markets are pricing in roughly 3 hikes next year and at this point, given Larry Summers, former NY Fed President Bill Dudley and the entire sell side shift to a hawkish stance, 50-75bp of hikes next year will likely be viewed on the dovish side.
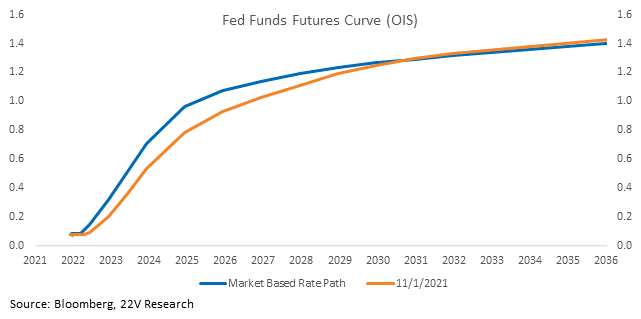
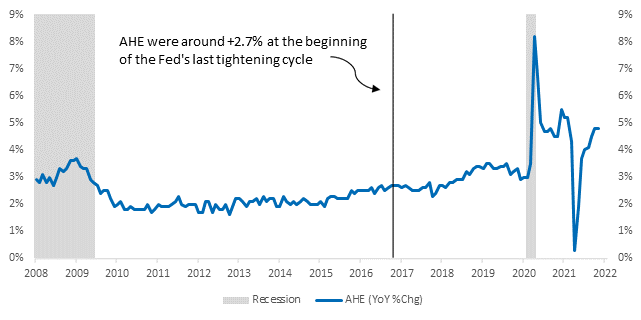
The major point of the previous chart, the next year or so of hikes are priced and if the futures curve is wrong, it is wrong by a hike or two. Not meaningfully off. In an environment of Core PCE still ending 2022 above 2.5%, just about all scenarios for monetary policy will still accommodative (real rates deeply negative). Jason Furman, who was well ahead of the shift in Fed policy and some say helped cause the shift, puts it this way (paraphrasing) Monetary policy should continue to be expansionary, just not extremely so. Think about it in these terms, when the Fed started tightening in last Cycle, core PCE was in the 1.6 to 1.7% range. Today it is 3.6% and wages are MUCH stronger.
At the start of the last tightening Cycle, real implied 10yr yields were +150bp higher than current levels. Yep, you read that correct, +150bp. Unless the markets start to price in a Fed mistake (which the Fed clearly doesn’t want to make, it could happen, but why price that in now) financial conditions will remain easy. Despite the aggressive shift to hawkish forecast from the sell side and the Fed pivot, financial conditions have remained easy. Outside of the short-term impact from Omicron. Omicron is a bigger issue for financial conditions than the Fed.
So what do we do from here? Keep in mind that 2yr rates have moved aggressively. As John Roque pointed out yesterday. “The 2-year Treasury yield, which is running its fastest race ever, is today’s Secretariat. The yield, which is currently at 0.70%, is 180% above its 200-day moving average (bottom chart). This is its greatest overbought reading of all-time.”
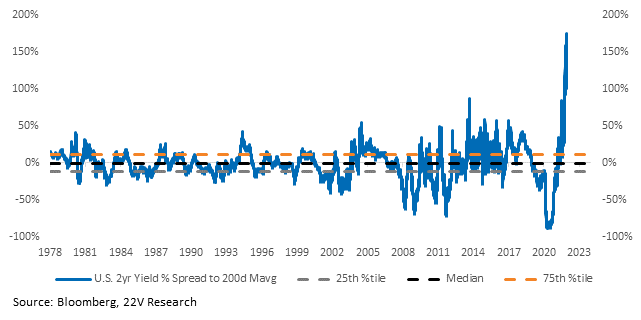
We looked at the spread between the recent move in the 2yr relative to the 10yr and it is in the 100th %tile historically. We believe the 2yr yield is going higher, but unless you can make a firm call that a Fed mistake is coming, expect some upward pressure on 10yr yields going forward.
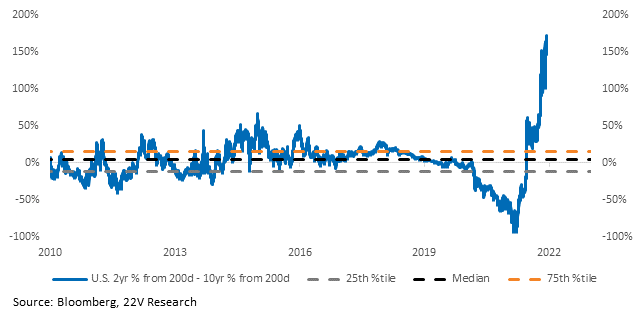
The yield curve has flattened aggressively and the sell side is now tripping over themselves to make flattener calls. The implication of that is Defensive outperformance. Fed policy is still going to be extremely easy next year (and beyond) even with rate hikes and if Omicron fears fade, 10yr is moving up aggressively. The 10yr has been tracking reopening stocks and that helps explain the aggressive flattening (Fed pivot combined with Omicron). The risk of course is persistent COVID overhang for the 10yr.
The problem with what is laid out above (yield curve steepening relief) is near term. CPI is tomorrow and its likely to be stronger than expected. Manheim used vehicle prices suggest another jump in used car prices. Durable goods inflation will come down next year and that is fairly consensus, so people might look through a higher headline CPI number tomorrow.
CHINA CREDIT UPDATE: China social financing was a weaker than expected this morning but has clearly hooked up on a YoY basis. The China credit impulse has not yet but will in the coming months (comps are easy). China levered names tend to do well when China social financing and the credit impulse increase.