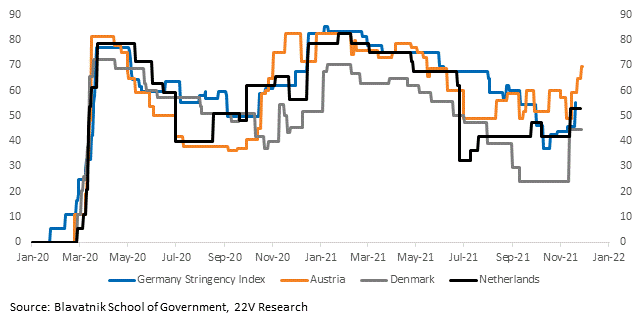
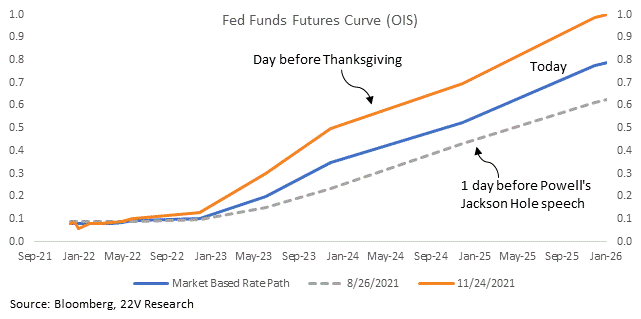
SUMMARY: Risk assets are retracing some of yesterday’s gains after Moderna’s CEO doubted the effectiveness of current vaccines against the new variant in an interview. We are monitoring severity (so far Omicron is milder than Delta) and policy responses. Restrictions are rising in Europe but are still below early 2021 levels, are stable in the U.S. and Asia. Powell noted in prepared testimony that the variant poses downside risks to employment and economic activity and increased uncertainty for inflation. That has led to a sharp decline in Fed rate hike expectations and is helping support large cap tech names.
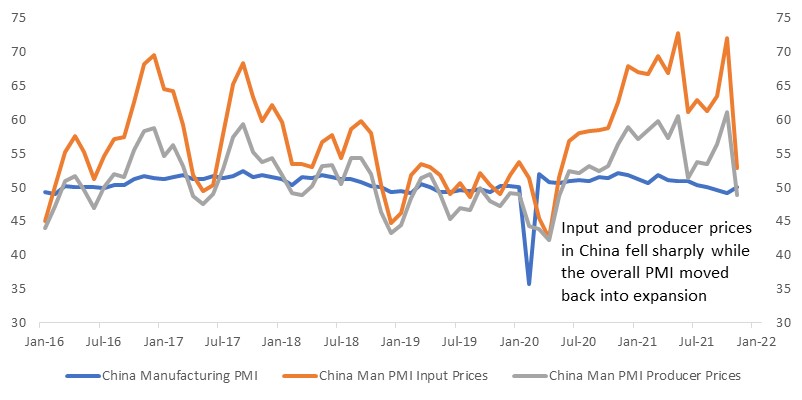
China’s manufacturing PMI beat expectations, rising to 50.1 (est 49.7, prior 49.2) and moved back into expansion for the first time since August. Importantly, inflationary measures eased significantly with input prices falling to 52.9 from 72.1 and output prices declining to 48.9 from 61.1. Signs that inflation is easing in China increases the odds of a policy response from Chinese authorities (one reason people think China has been slow to respond is because of the high inflation rates). Better economic data from China a strong European CPI print and a decline in US rate hike expectations are helping support the Euro overnight.
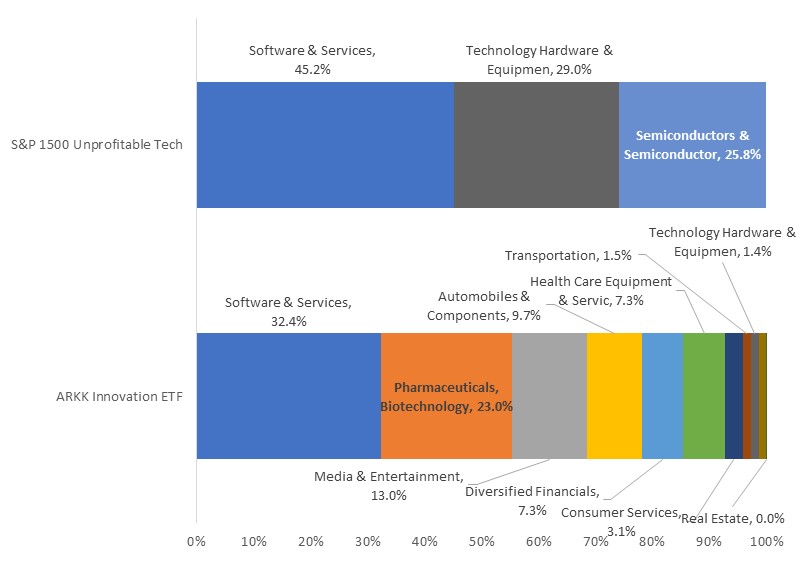
The backdrop is still complicated and many of the pre-Omicron trends remained in place with quality, low volatility and profitability factors outperforming. That should continue. Unprofitable Tech and highly speculative names continued to struggle. Frequently, ARKK and unprofitable Tech (define as negative earnings before extraordinary items) are conflated. It is useful to keep in mind that there is zero crossover between ARKK holdings and the 31 unprofitable Tech companies in the S&P 1500.
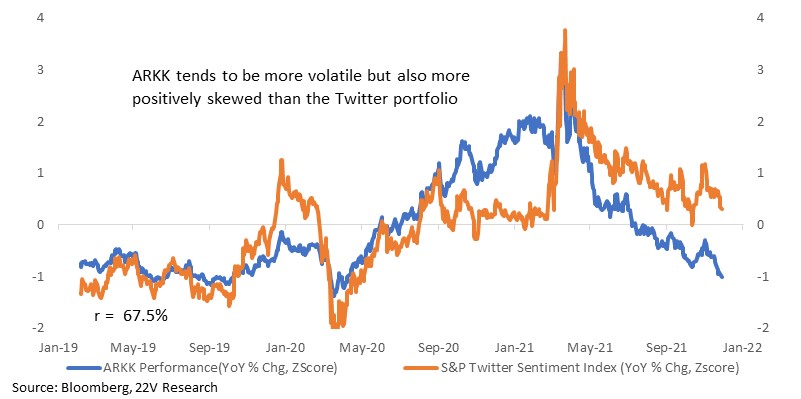
Rather than being a Tech basket, the ARKK Innovation Fund tends to be highly correlated with the performance of the most popular Twitter names.

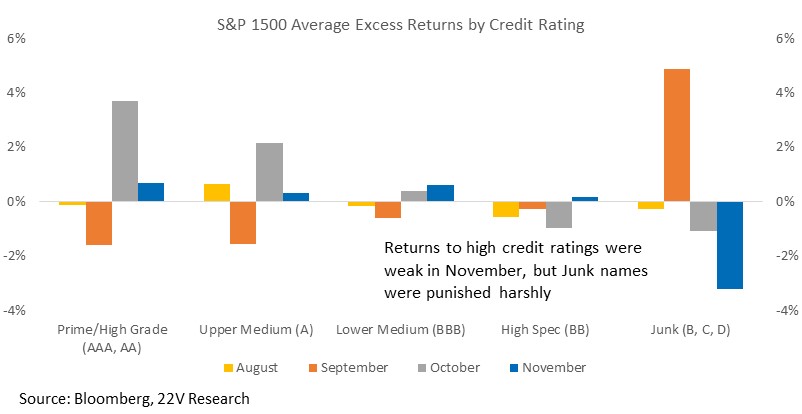
High risk stocks (speculative names, unprofitable companies, those with poor credit ratings) have suffered as volatility has moved higher. We expect that trend to remain in place as investors adapt to new market dynamics (fed policy, Omicron, etc.). Keep in mind that although 10yr yields have moved lower, inflation expectations have declined and credit spreads have widened. That is why higher risk stocks are not benefiting from the decline in rates.
Full report below…
MARKET VIEWS: Risk assets are retracing some of yesterday’s gains as renewed concerns about the Omicron strain rattle investors. Moderna’s CEO doubted the effectiveness of current vaccines against the new variant in an interview. As we noted in our COVID charts update yesterday, limited data means forecasts of case growth and hospitalizations remain guesses. We are monitoring severity (so far Omicron is milder than Delta) and policy responses. Restrictions are rising in Europe but are still below early 2021 levels, are stable in the U.S. and Asia. Unless restrictions move much higher, the economic outlook is unlikely to change much.
Medium term, activity levels and supply chain issues continue to improve. China’s manufacturing PMI beat expectations, rising to 50.1 (est 49.7, prior 49.2) and moved back into expansion for the first time since August. Importantly, inflationary measures eased significantly with input prices falling to 52.9 from 72.1 and output prices declining to 48.9 from 61.1.
Signs inflation is easing will help reduce the macro uncertainty that has weighed on risk appetites. Volatility remains elevated across asset classes. Higher than expected inflation has left the fed less willing to look through current price increases, especially if labor market slack continues to decline. The U.S. payroll report out this Friday will provide important signals on that front (participation and wage growth in particular). For now, rate hike expectations have collapsed, which is should provide SOME cushion for stocks.
ARKK IS NOT Unprofitable Tech: Stocks rallied yesterday, but many of the pre-Omicron trends remained in place. Unprofitable Tech and highly speculative names continued to struggle. Frequently, ARKK and unprofitable Tech (define as negative earnings before extraordinary items) are conflated. It is useful to keep in mind that there is zero crossover between ARKK holdings and the 31 unprofitable Tech companies in the S&P 1500. ARKK holds stocks from Tech, Biotech, Discretionary, Financials, ,etc. 44 holdings, ~10% of the portfolio is TSLA (technically not a Tech company) and five stocks make up a third of the ETF.
ARKK is heavily skewed towards a particular kind of holding; popular (high liquidity) names with volatile earnings and frequent price swings (Price Failure). It has negative exposure to almost all other factors and is strongly skewed AWAY from Value.
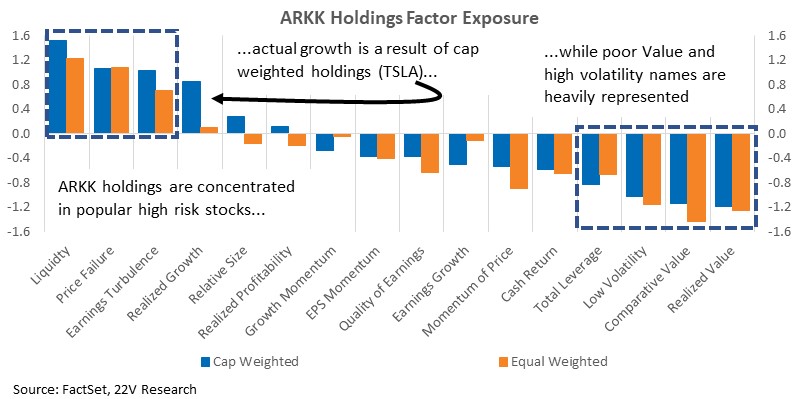
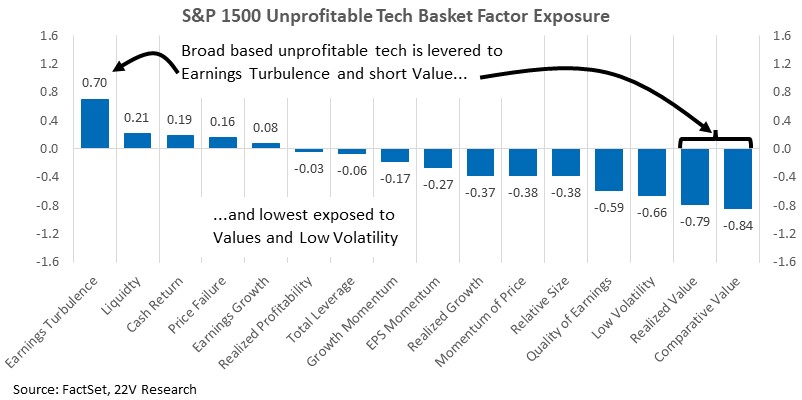
As the factor exposure chart above illustrates, ARKK does tend to hold companies with poor Realized Growth but because of its heavy holding of TSLA, it is skewed toward profitable companies. Broad unprofitable Tech has 1) high Earnings Turbulence, but less than in the ARKK portfolio, 2) has much less extreme factor skews in general. Put another way, being unprofitable is a relatively more important characteristic of the unprofitable tech basket, while ARKK is more of a pure bet on high visibility growth names.
Rather than being a Tech basket, the ARKK Innovation Fund tends to be highly correlated with the performance of the most popular Twitter names.
Over the past two months, investors have rotated out of highly speculative names and into higher quality names. Headlines tend to focus on the weakness in certain areas of the market, but the rotation into higher quality stocks reinforces the idea that the current shift in volatility (higher) and risk appetites (lower) is causing more of an internal rotation than a broad market selloff.