
Our entire repository of COVID charts is HERE.
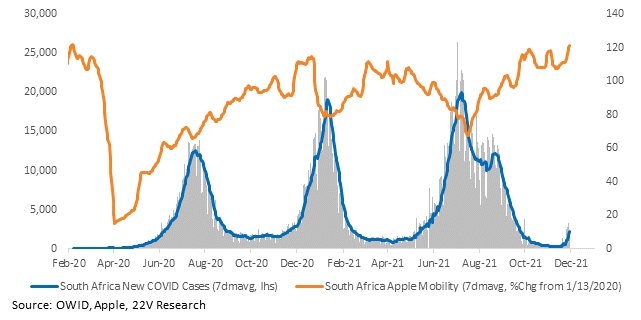
John Burn-Murdoch of the Financial Times put together a great graphic of COVID cases and hospitalizations in Gauteng, South Africa, the epicenter of omicron. Cases are rising faster but hospitalizations are on the same pace; that could imply the variant is less severe and/or people have some built up immunity from prior infections and vaccinations. That could also be because the cases are primarily in the young, but we have no reason to be overly pessimistic and assume it’s all demographics. In the same vein, the EU has recorded 44 confirmed cases of the omicron variant in 11 counties and all are either asymptomatic or people with mild symptoms. So far, the prospective omicron wave does not appear to be too different than the delta wave, during which activity remained elevated because cases were decoupled from hospitalizations and deaths.

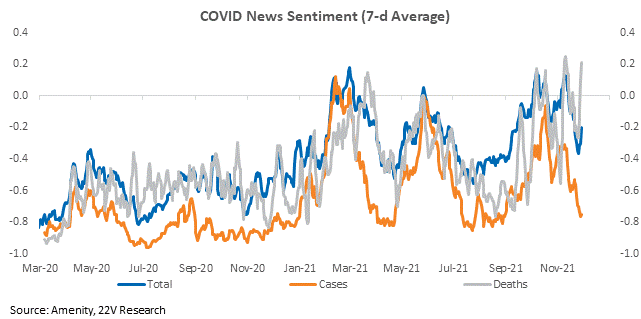
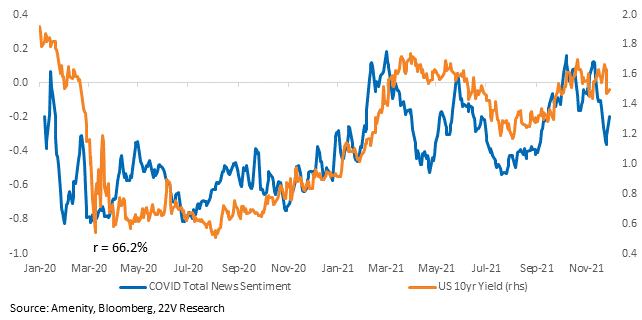
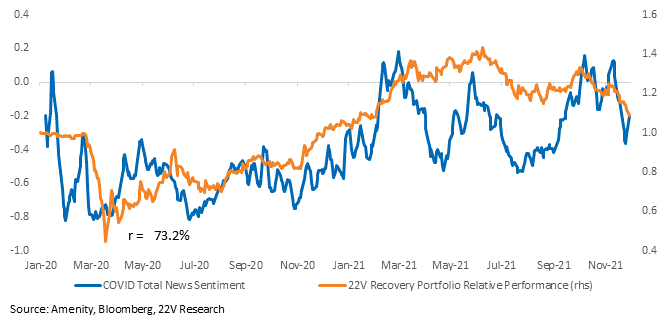
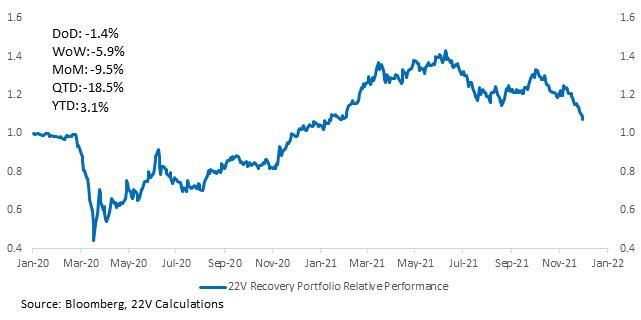
Total COVID sentiment dropped initially following the Omicron news. Death sentiment has rebounded as headlines surfaced about milder symptoms while case sentiment continues to deteriorate. 10yr yields and Recovery Portfolio performance have both followed total sentiment lower. Recall that the 10yr is used as a hedge.
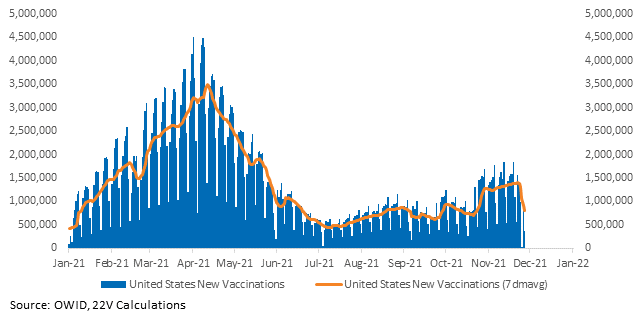
Moderna’s CEO doubted the effectiveness of current vaccines against the new variant in an interview after Moderna’s Chief Medical Officer said vaccinated people should still be protected in an interview on Sunday while BioNTech Founder Ugur Sahin believes omicron is unlikely to cause severe illness in vaccinated people, emphasizing how little information we all have and how important it is to monitor severity. Pfizer CEO Albert Bourla believes Pfizer’s COVID treatment pill will still be effective because it was designed with the likelihood of variants in mind. Ideally, vaccines and treatments will still help against Omicron; boosters continue to be rolled out globally.
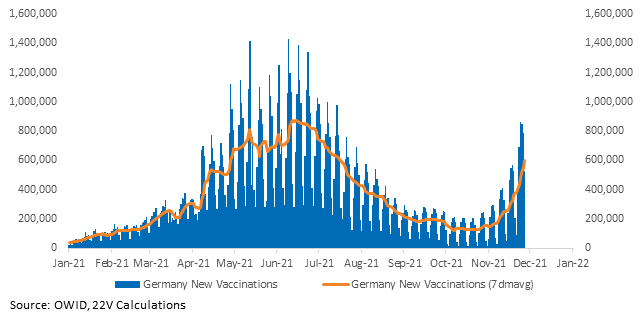
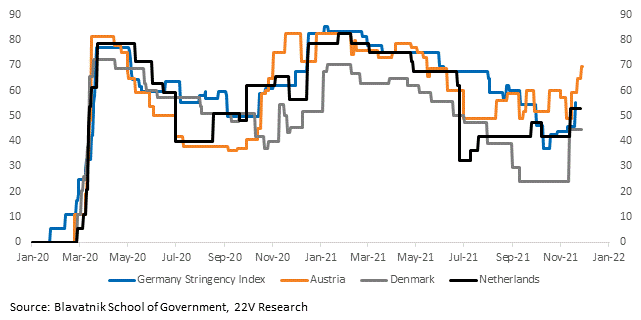
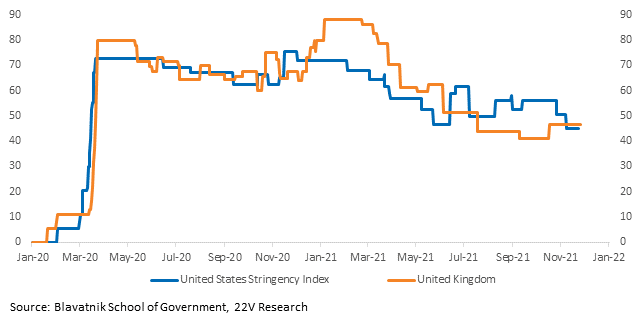
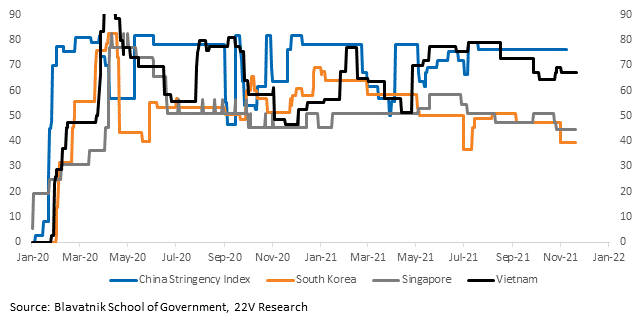
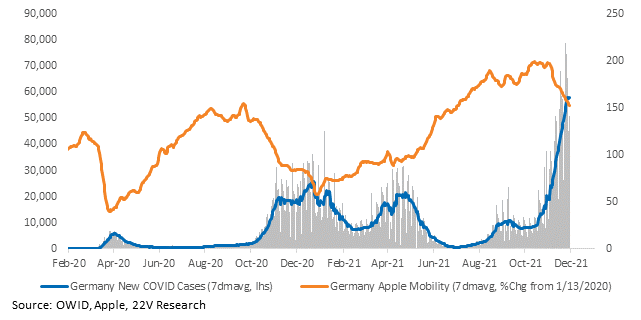
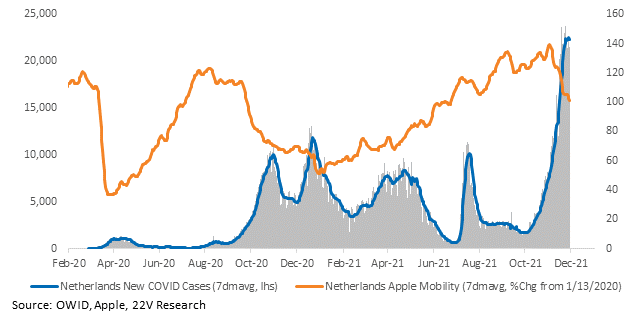
Investors have to contend with policy responses to Omicron. Travel restrictions are being imposed globally. The Netherlands tightened its partial lockdown – now most venues have to close at 5 pm. German officials are meeting Tuesday to discuss toughening restrictions. The list goes on in but with varying degrees of severity. Oxford’s stringency indices will help objectively score how intense restrictions are. Restrictions are rising in Europe but are still below early 2021 levels, but are stable in the U.S. and Asia.
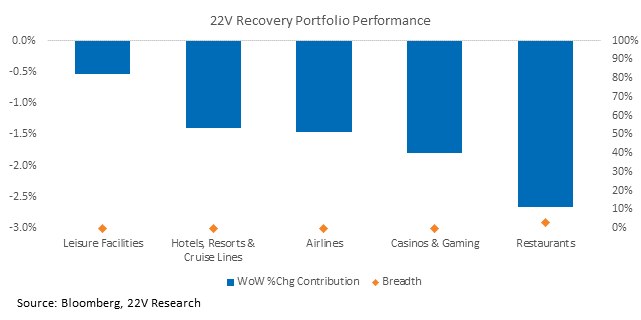
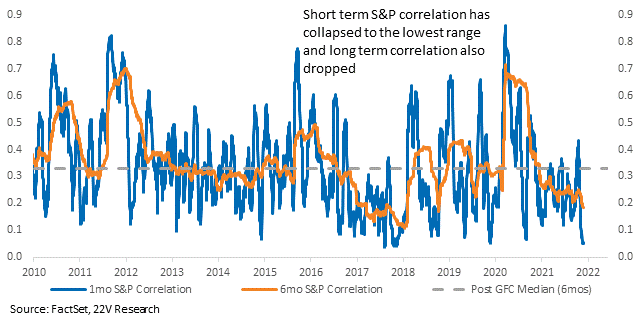
While severity is low, the longer-term outlook for equities is constructive. Credit widening out is a headwind near-term, but we will still have high, but not too high inflation and strong economic growth. Crushing the recovery would prevent the Fed from reaching their goal of price stability with full employment. That will temper the FOMC’s rate hikes when they start. Omicron will continue to impact on market internals, though, especially considering new government restrictions. Our Recovery Portfolio is significantly underperforming again today. Only 1% of the portfolio’s constituents have increased WoW. Even with the selloff, short-term correlations have dropped further leaving stock picking a more important source of alpha.
Mobility metrics will help gauge activity.
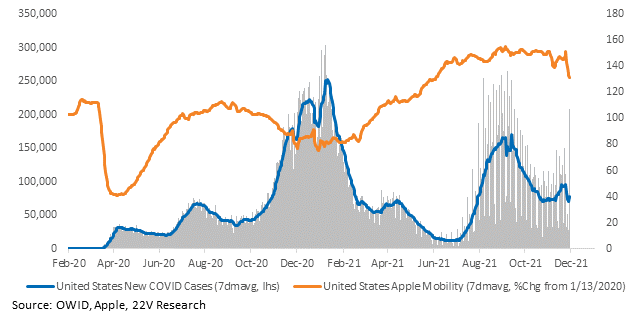
Charts for every state and country we have data for are HERE.

