SUMMARY: 2yr yields are headed higher but we did not expect what felt like an impromptu Fed press conference yesterday along with President Biden’s comments and Treasury secretary Yellen talking about inflation problems. What investors are starting to internalize though is something that Jason Furman, former chairman of the White House Council of Economic Advisors and influential democratic thinker, has laid out (hat tip to Gerard for highlighting this last week). It is in the Democrats interest for the Fed to nip inflation in the bud and if they do so, people will HOPEFULLY look at the positives from build back better, not just worry about inflation. Daily news mentions of inflation are at their highest level in years and inflation sentiment is near its lowest level in recent history. That is prompting the shift in inflation comments from all levels of government. See the SPR release announcement today.

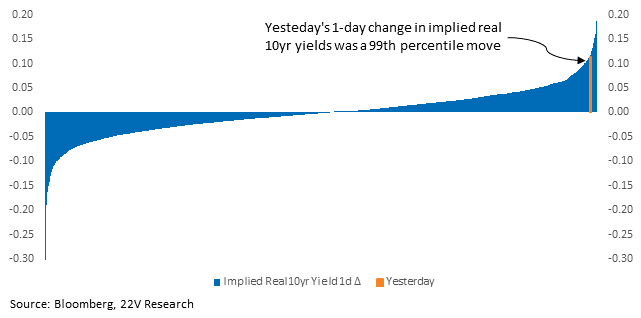
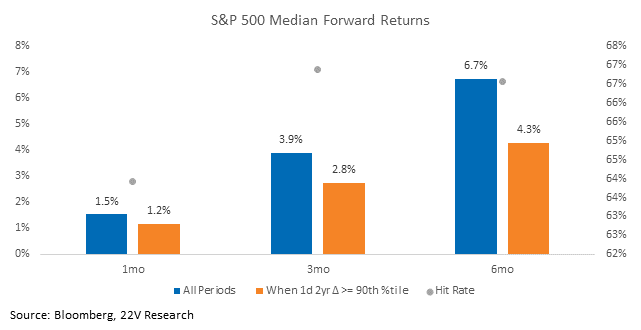
The tone shift on inflation is how get a 99th %tile one day move higher in 2yr and 10yr yields. Forward market returns when 2yr yields have a move like yesterday are generally lower than normal on a 1/3/6 month basis. They are not negative though.
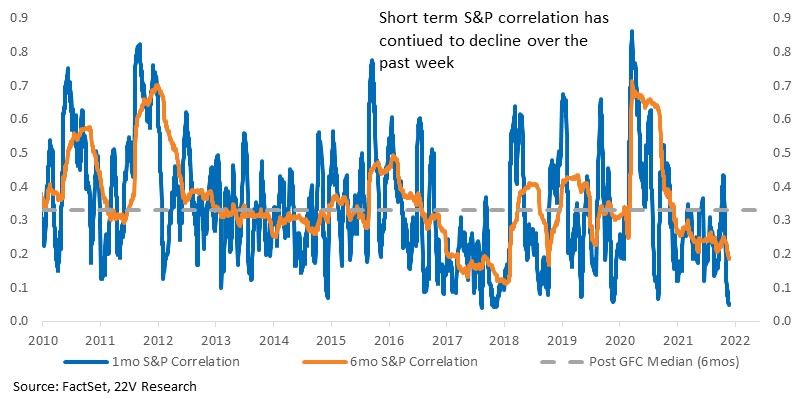
That fits with a theme of ours. The subtle shift in Fed stance (from pursuing to tolerating higher inflation, a case Gerard has made an excellent call on) is incrementally negative for risk assets but is more likely to cause shifting internals than a decline in broad based indices (Spec tech as an example). Over the past week, S&P intra-portfolio correlation (IPC) has fallen into its 0th %tile (2010-fwd). There are no signs of systemic market declines. The absolute level of correlations will remain low barring an economic shock.
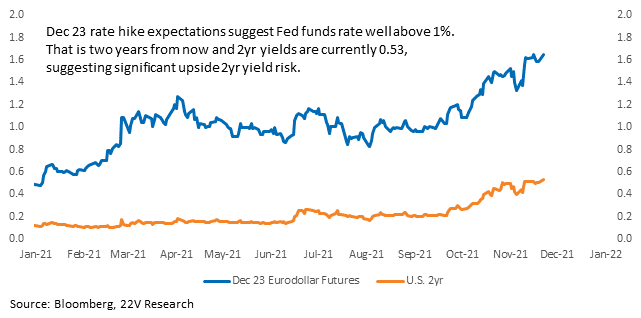
The upward pressure on core inflation along with a strong US demand backdrop (see housing yesterday), solid Europe activity (see stronger than expected flash PMIs overnight), and stable China suggests 2yr yields have PLENTY of room to increase from here. China is the biggest risk. We had an unusually large number of conversations on what the neutral fed funds rate will end up being. This is all guess work, but most think the funds rate will end up around 2%-2.5%. That implies significantly higher 2yr yields from here.
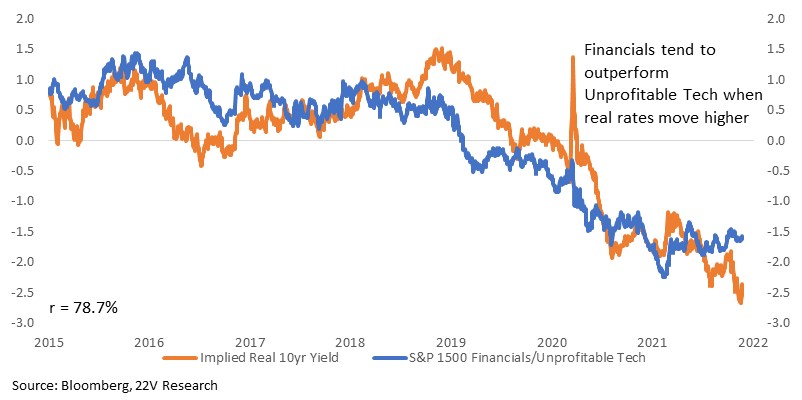
We like the pair of being long Financials and short unprofitable Tech. If long rates are not going significantly higher (we don’t think they are), large cap Tech will be fine. We will be wrong if 1) goods deflation is more intense than estimated or 2) participation rates increase much more quickly than they have been.
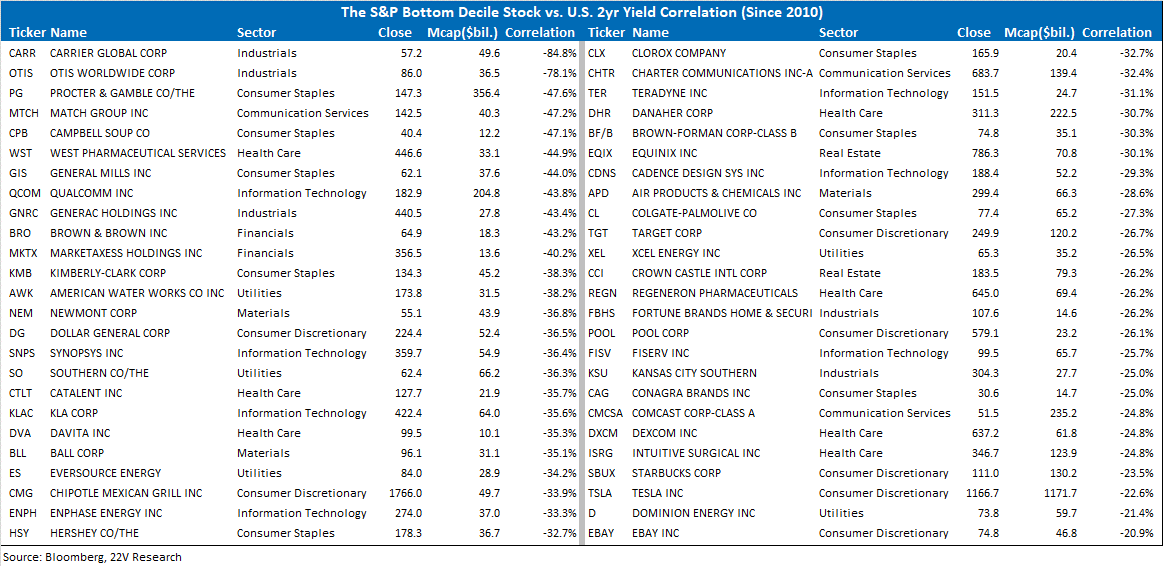
Stay long companies that benefit from strong US demand, improving supply chains, and/or are housing related. We also highlight a list of companies with the highest and lowest correlations to 2yr yields. Those companies are interesting to look at from a risk management point of view.
Full report below…
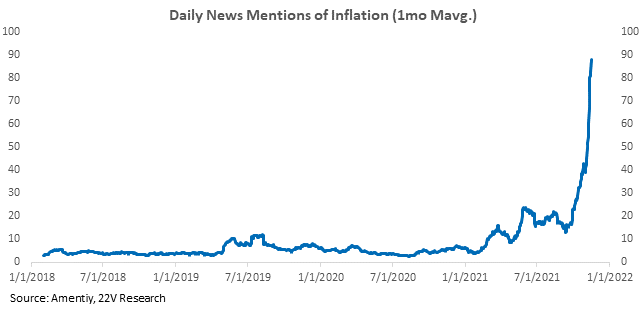
MARKET VIEWS: The likely trend in Core PCE justifies higher 2yr yields. We have been noting that for a few weeks. We certainly did not expect what felt like an impromptu Fed press conference, with the addition of President Biden, and comments from Treasury secretary Yellen. All of them mentioned that inflation was a potential problem and needed to be contained. We of course did not get an official policy shift. What investors are starting to internalize though is something that Jason Furman, former chairman of the White House Council of Economic Advisors and influential democratic thinker, has laid out. It is in the Democrats interest for the Fed to nip inflation in bud and if they do so, people will HOPEFULLY look at the positive from build back better, not just worry about inflation. The daily mentions of inflation are near an extreme…
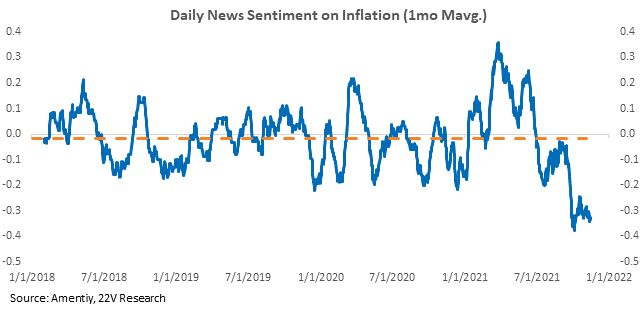
…and inflation sentiment is near lowest level in recent history.
Bottom line, we basically saw an across the board, near term, tone shift on inflation from everyone. That is why we had a 99th %tile one day move higher in 2yr yields…
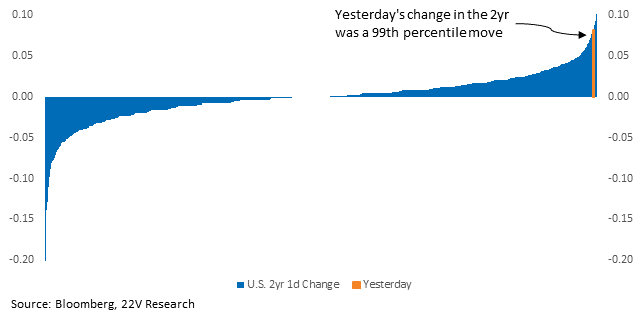
…and a 99th% tile one day move higher in 10yr yields.
FYI…the forward returns for equities when 2yr yields have extreme moves is lower than normal. The returns are not negative though. We think lower than normal returns are perfectly reasonable. Especially since real yields will remain very low under most reasonable 10yr yield forecast.
Given the upward pressure on OER and wage growth, it appears participation will not come back as quickly as the Fed needs it to. The upward pressure on Core inflation should be put into the context of very a strong US demand backdrop (see housing yesterday), strong Europe (see stronger than expected flash PMIs overnight) and stable China. China is biggest risk to the demand outlook. All of the above suggest 2yr yields have PLENTY of room to increase from here. They are well below what the estimate of the Fed funds rate is two years from now.
Also, we had an unusually large number of conversations on what people think the neutral rate Fed funds rate will be yesterday. Most think it is +2% and as high as 2.5%. If the Fed funds rate is going to be 2% to 2.5% by some time in 2024, 2yr yields have significant upside. We really like the pair of being long Financials and short unprofitable Tech going forward. As long as long rates are not going significantly higher (we don’t think they are), large cap Tech will be fine. We will be wrong if 1) goods deflation is more intense than estimated and 2) participation rates increase much more quickly than they have been.
The Rapid declines in small cap and speculative tech/finance names does increase worries about a broader, equity market selloff/re-risking event. We have argued that while the subtle shift in Fed stance (from pursuing to tolerating higher inflation, a case Gerard has made an excellent call on) is incrementally negative for risk assets, it is more likely to cause shifting internals than a decline in broad based indices. Market internals indicate that view is unfolding. Over the past week, S&P intra-portfolio correlation (IPC) has fallen into its 0th %tile (2010-fwd). There are no signs of systemic market declines. Now, correlations are likely to move higher from their current level, but the absolute level of correlations will remain low barring an economic shock.
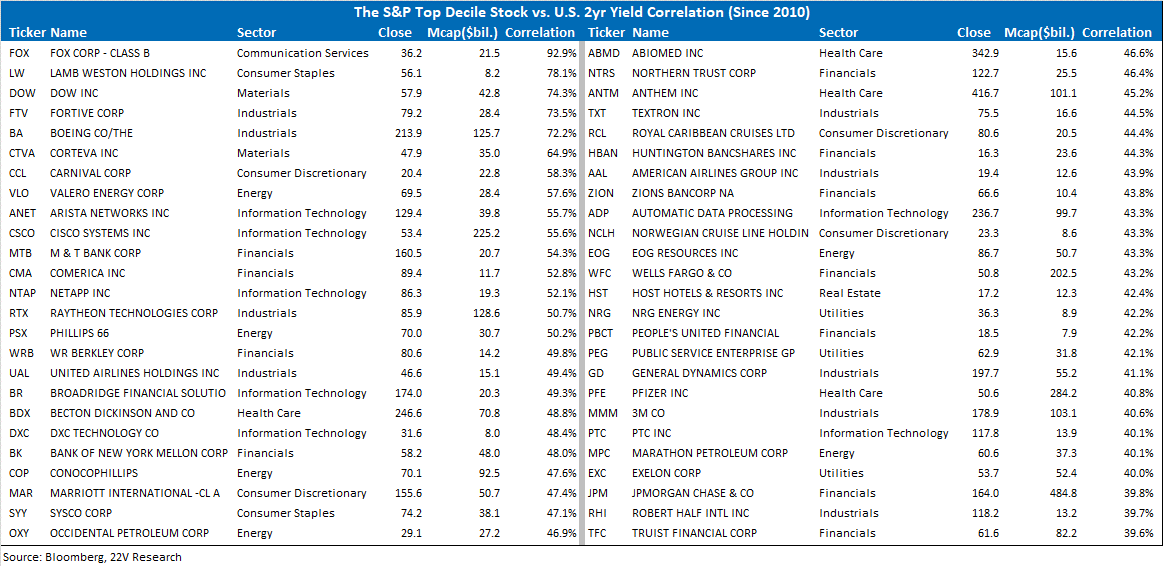
Below we lay out two baskets of stocks. The First is those with positive correlation to 2yr yields. The basket has an R of 92%
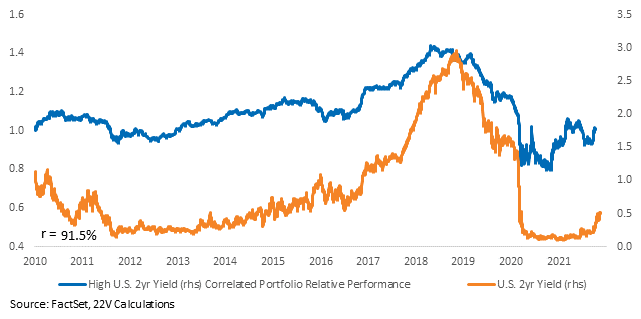
The positive correlation to 2yr yield basket of stocks.
The basket of stocks with a negative correlation to 2yr yields has an R of 90%.
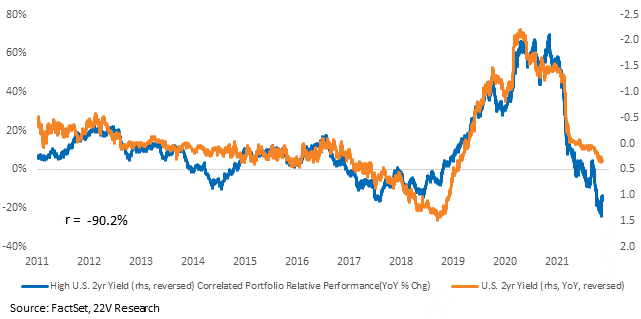
Below is the basket of stocks with highest negative correlation to 2yr yields since 2010.
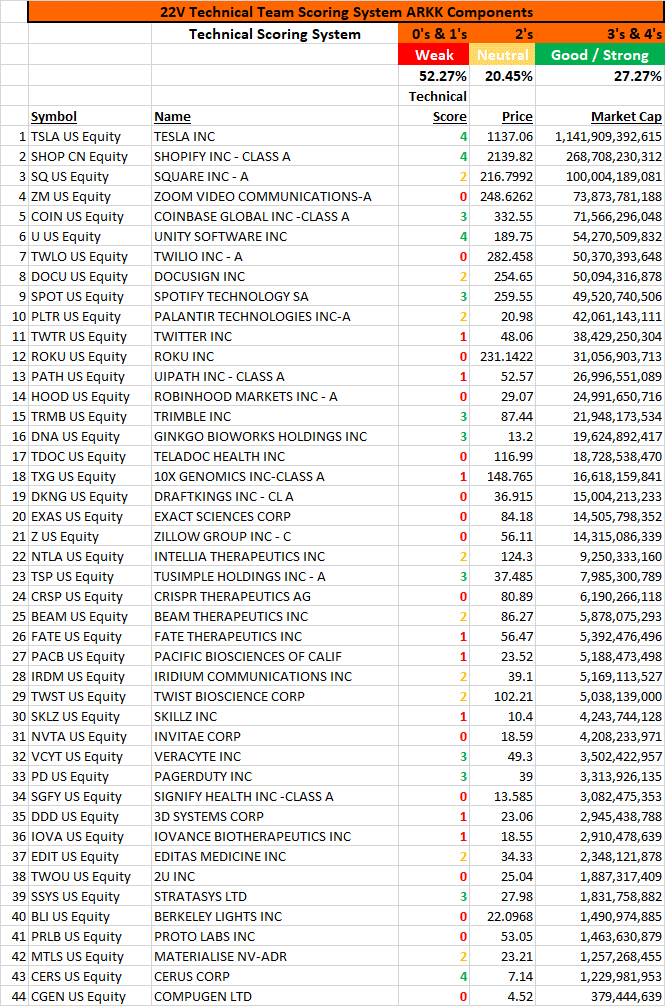
List of ARKK stocks and technical scores from John Roque. The red numbers are the shorts.