
Our entire repository of COVID charts is HERE.
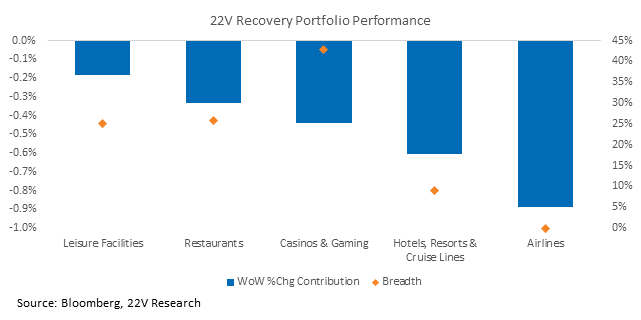
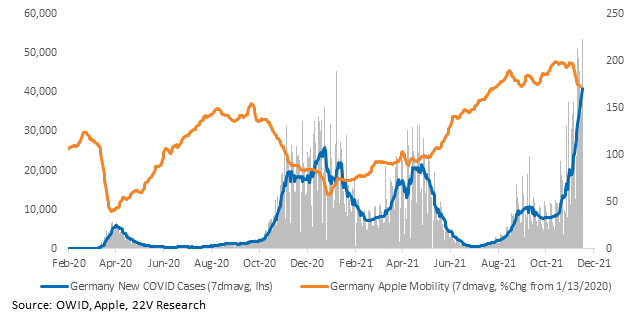
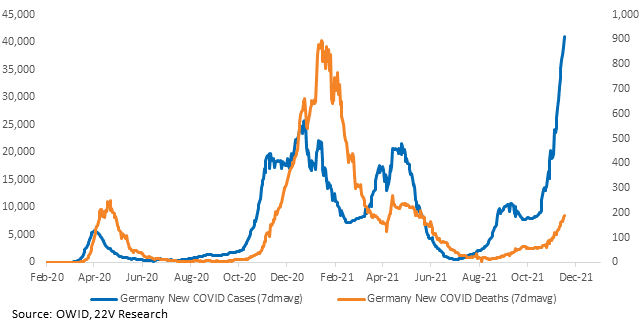
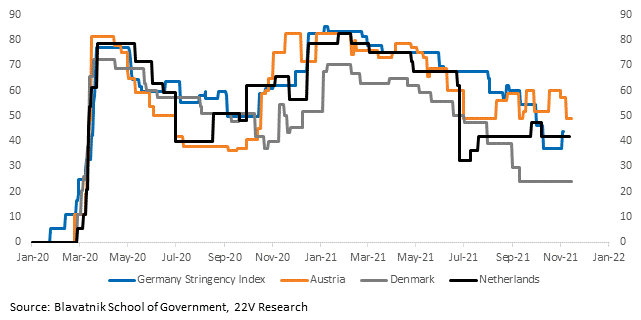
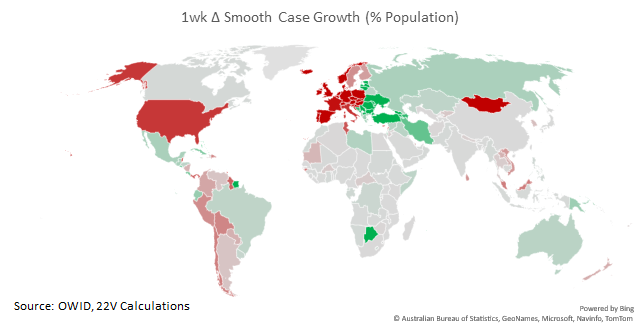
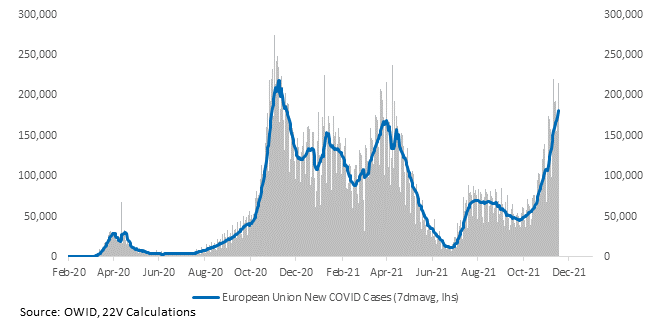
Case growth hit a new record in Germany yesterday. New restrictions are being imposed, mostly focused on the unvaccinated. Booster shots are also being rolled out. Stringency indices in the hardest hit countries are well below early 2021 levels. Restrictions this time around will not be as intense, thanks to vaccines. Stoxx 600 travel and leisure stocks underperformed by -1.8% today. Performance has followed case growth since the summer as periodic waves have disrupted reopening plans and cast doubt on travel demand and restrictions. Left-tail economic risk has been diminished but COVID still matters for internals. Our recovery portfolio has been whacked again this week. Airlines are particularly poor.

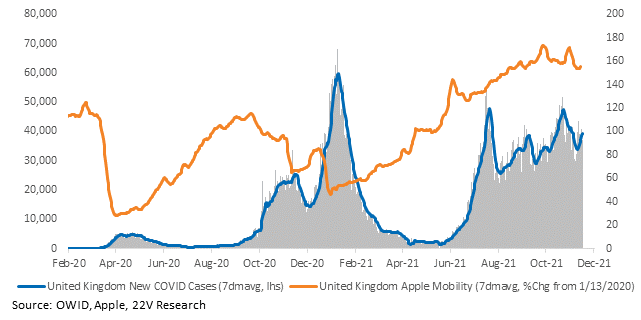
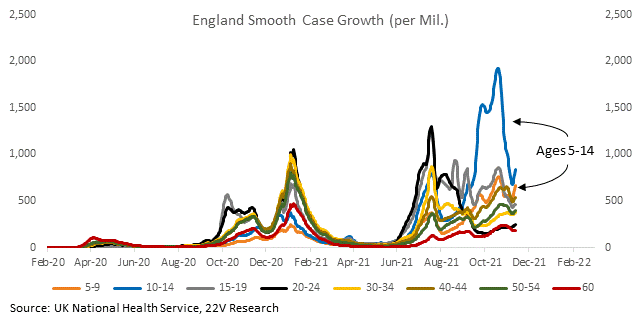
Case growth is higher in the UK. New cases are concentrated in younger cohorts again, though 40–44-year old’s have the 3rd worst rate (behind 10-14 and 5-9). More importantly, case growth rates remain low in the oldest cohorts, for which COVID is the most dangerous. There is no sign that this wave is breaking through vaccinations at an unusual rate. That helps.
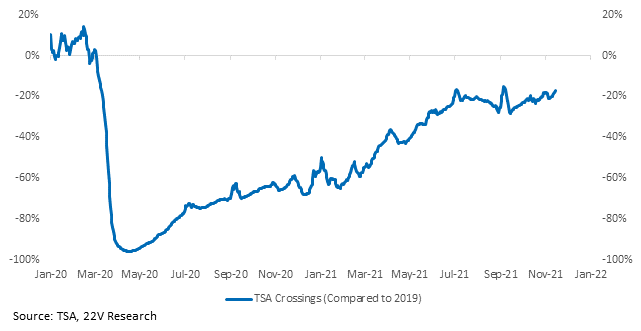
Travel demand is still increasing in the US; TSA crossings are near a post-pandemic high compared to 2019 (-17%).
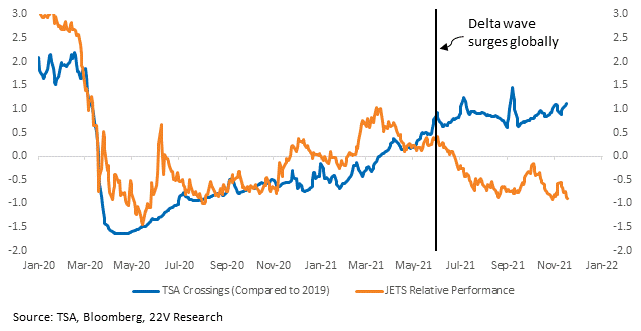
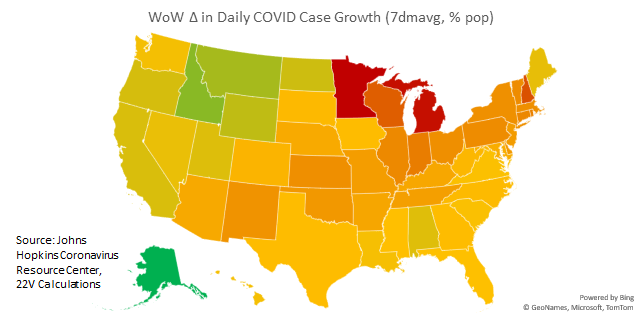
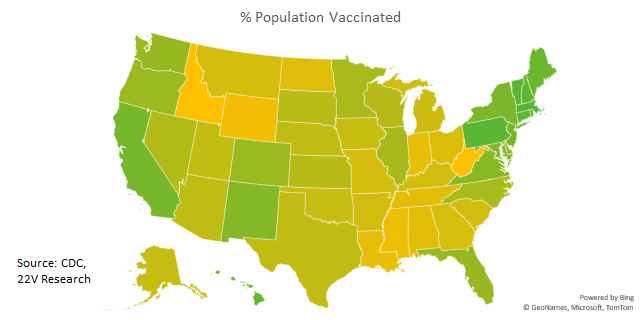
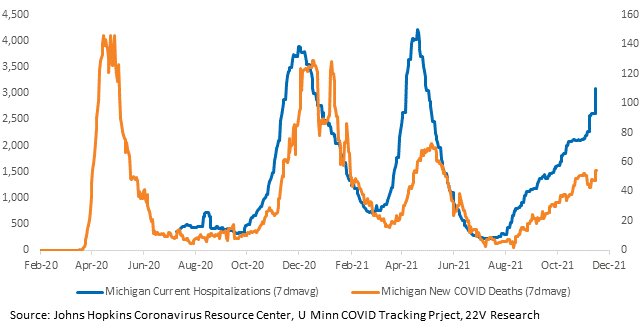
Case growth is higher in the US, worst in areas with low vaccine uptake. Hospitalizations are increasing in low vax areas as well. New antiviral pills may be particularly useful reducing severe infections in the most at-risk, which would help ease concern about hospitalizations and deaths in regions with poor vaccination rates. Pfizer submitted its COVID-19 pill (paxlovid), which reduces the risk of hospitalization or death by 89%, for FDA authorization today. The U.S. government is also already locked into purchasing 3.1 million courses of Merck’s pill, molnupiravir, pending its FDA approval.
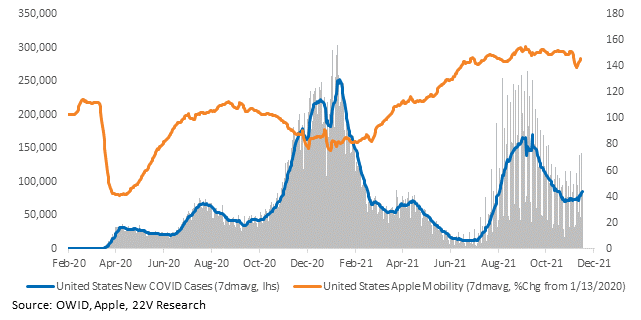
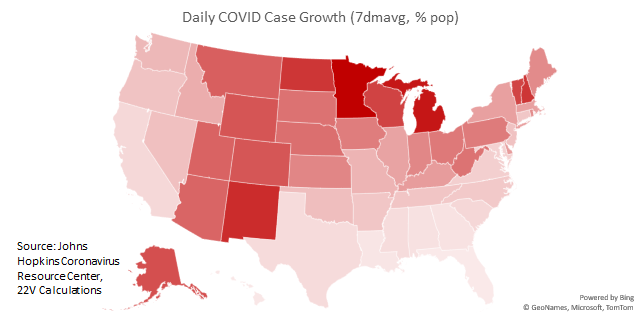
Charts for every state and country we have data for are HERE.

