
Our entire repository of COVID charts is  HERE.
Over the last week, 10yr yields climbed while COVID sentiment dropped. Yields are less correlated with COVID sentiment changes now, suggesting other impulses are more important as COVID risk fades from the forefront. That’s despite case growth, which, as we’ve been writing, has less of an effect on overall economic activity. COVID left-tail risk has diminished because of more treatments and vaccinations. New antiviral pills may be particularly useful reducing severe infections in the most at-risk, which helps ease concern about hospitalizations and deaths in regions with poor vaccination rates. Pfizer submitted its COVID-19 pill (paxlovid), which reduces the risk of hospitalization or death by 89%, for FDA authorization today. The U.S. government is also already locked into purchasing 3.1 million courses of Merck’s pill, molnupiravir, pending its FDA approval.

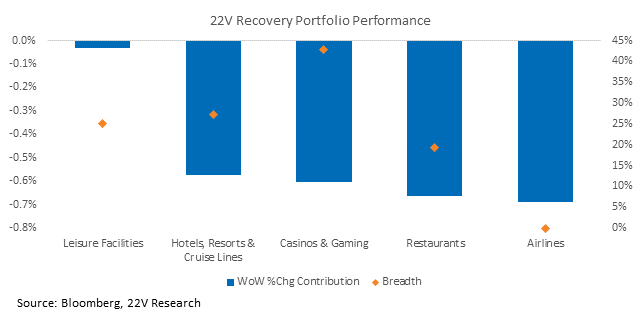
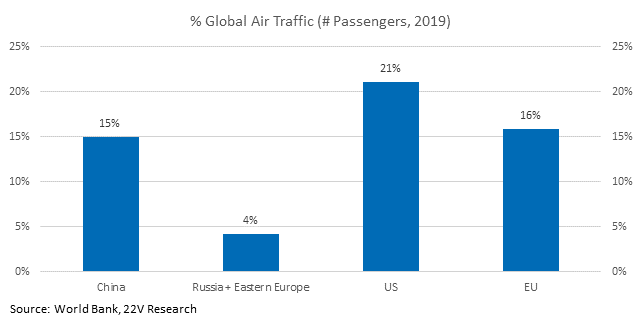
COVID still has an impact on internals though. Our Recovery Portfolio continues to struggle, underperforming again this week as COVID sentiment dropped. Airlines were the largest drag on performance as case growth casts some doubt on travel, even as reopening progresses in the United States and Asia, and jet fuel prices rise, cutting into profits. The EU accounted for 16% of global air traffic in 2019.
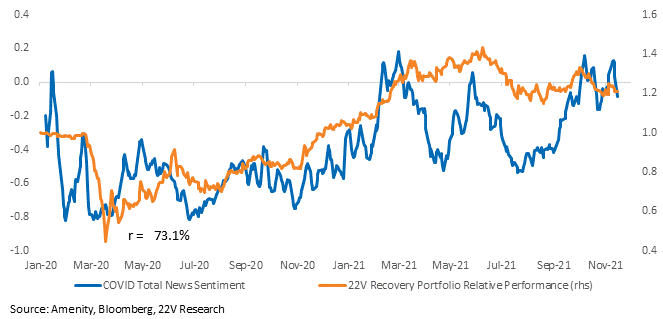
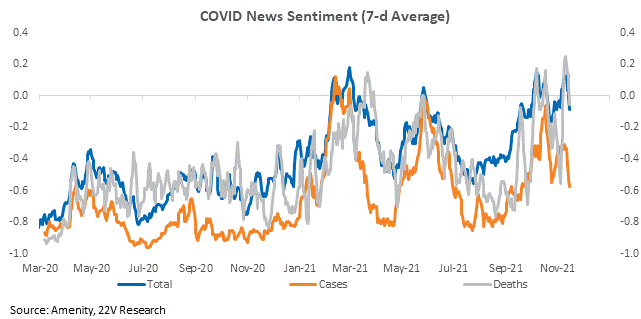
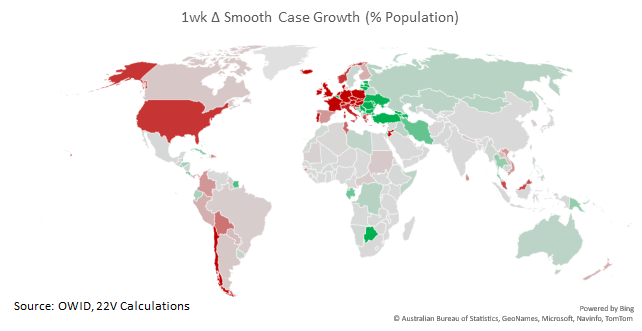
Overall COVID sentiment, case growth sentiment, and death sentiment all declined this week. Case growth is increasing across Europe and sentiment fell in response.
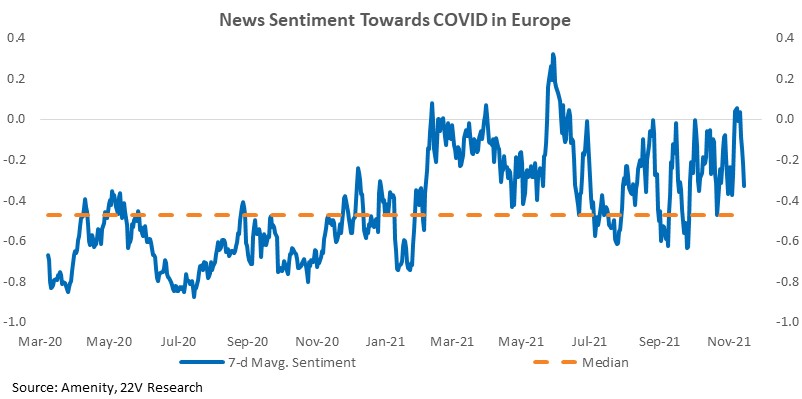
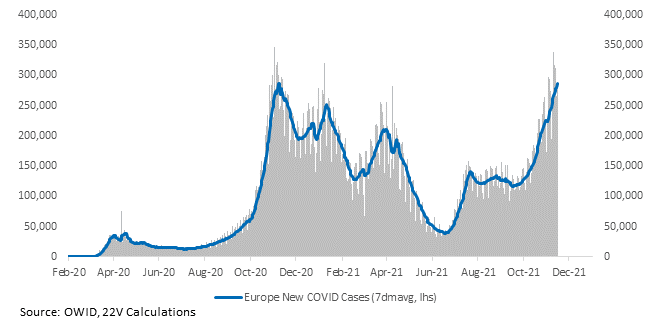
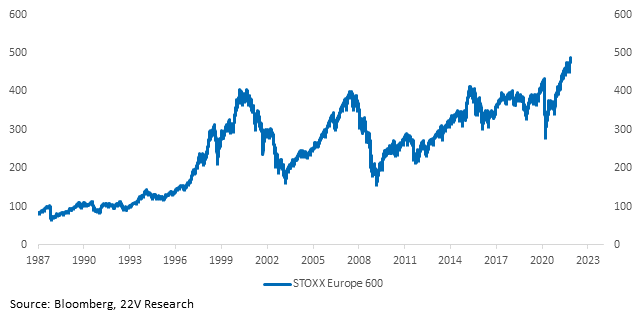
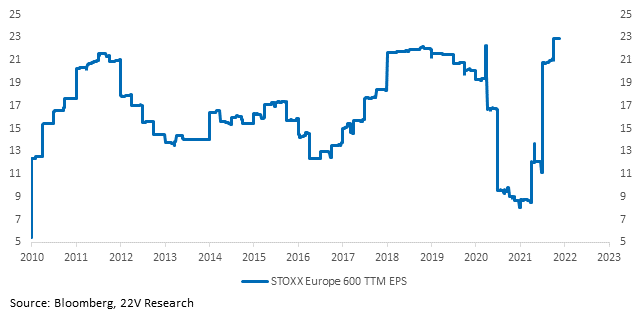
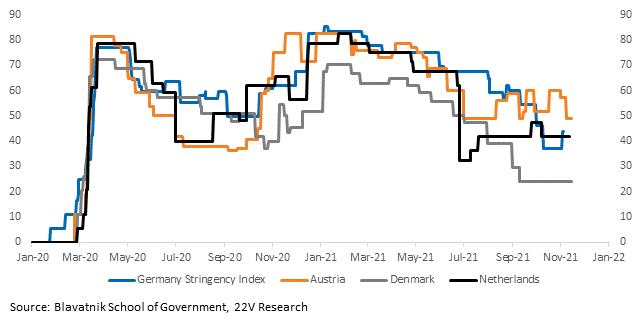
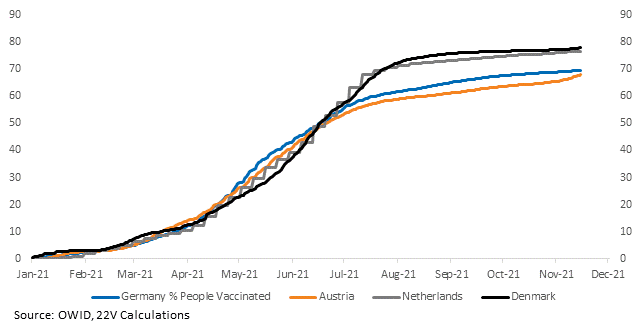
European stocks are at all-time highs despite case growth. And TTM earnings have recovered and reached a post-GFC high. High vaccination rates across the region help. Governments are reinstating partial lockdowns, but stringency indices illustrate the restrictions are much easier than earlier this year. We expect this trend to prevail.
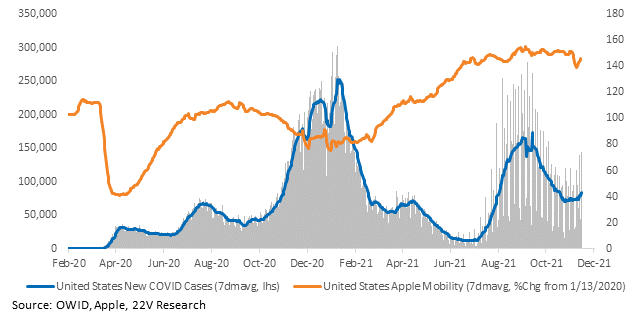
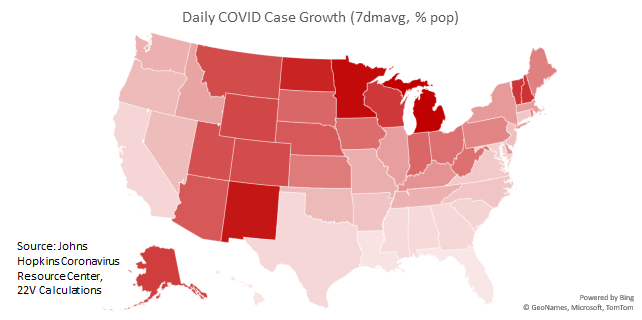
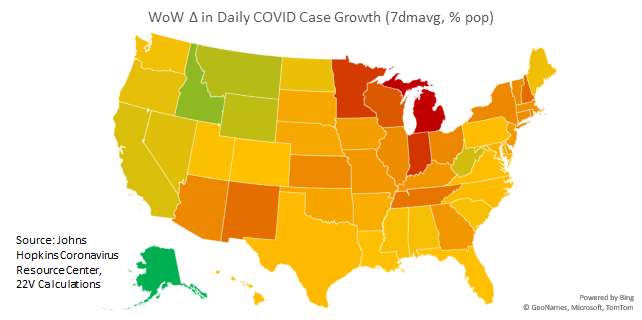
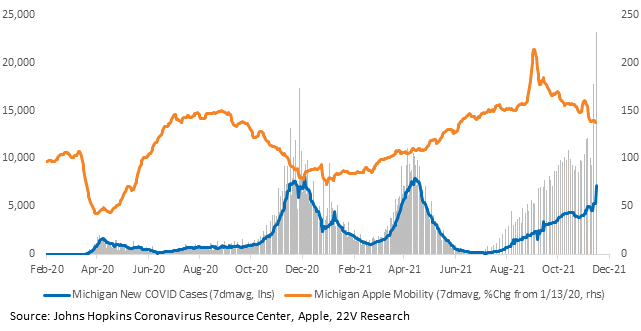
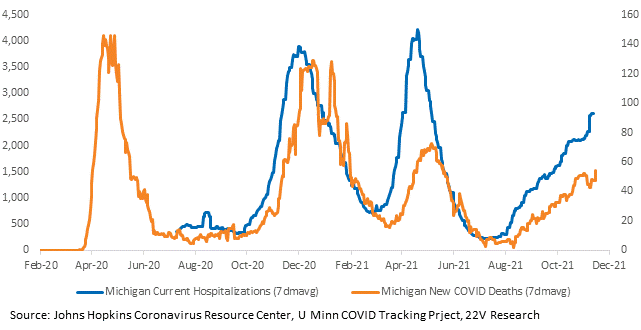
Case growth is higher again in the United States. Case growth is increasing across lower vaccination states. Use of antiviral pills may help, especially among the unvaccinated. So too will vaccinating children. There are more tools to fight the virus, which is helping keep activity (and growth) elevated. Today’s strong retail sales report reinforces our theory on the strong demand backdrop.
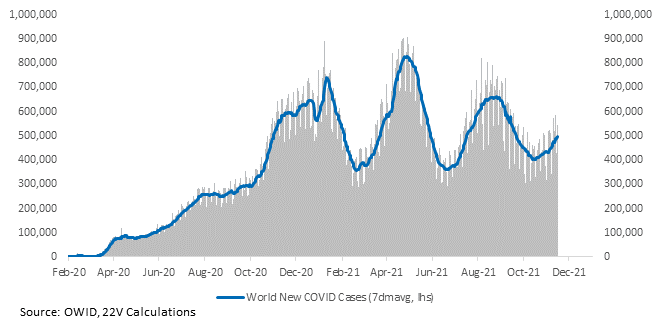
Global case growth is also higher, still mostly concentrated in Europe.
Charts for every state and country we have data for are  HERE.

