SUMMARY: China continues to be an overhang on UST Yields, but downside risk FROM HERE is limited. Supply chains are easing and although that does create some short-term inflation headwinds, the longer-term economic growth outlook will improve as bottle necks ease. That should bias yields higher given the tHhe firm demand backdrop. UST yields moving back toward their recent highs (1.69 on 10/21), bond volatility will remain elevated buoying stock volatility near term. The S&P would consolidate and internal rotations would become more important.
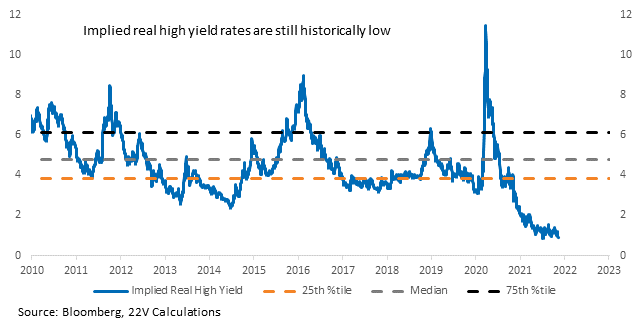
Keep in mind that the VIX moving higher, if it does happen, is unlikely to lead to a correction (defined as -10%). Implied real high yield rates remain at historically low levels. While that is true, don’t expect a sharp move lower in equity prices. It would take a dramatic shift in Fed signaling or an economic shock to change the low real implied yield backdrop near term.
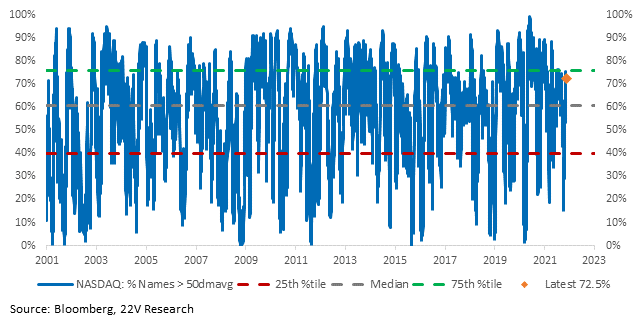
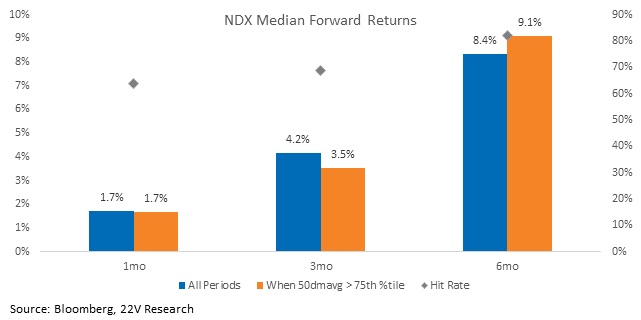
If 10yr yields do start backing up, they would be a headwind for Tech stocks. Tech is currently overbought with 75% of Nasdaq names trading above their 50-day moving average. Tech consolidation would spur reallocation into domestically focused Cyclicals like Banks, Retail, and Small Caps. Energy and Materials would continue to benefit from the strong developed world demand backdrop as well. Overbought conditions would be consistent with market like returns for Tech rather than shorting Tech (details below). Also, even at a 2.5% 10yr yield, the cash return yield of the Tech group is attractive.
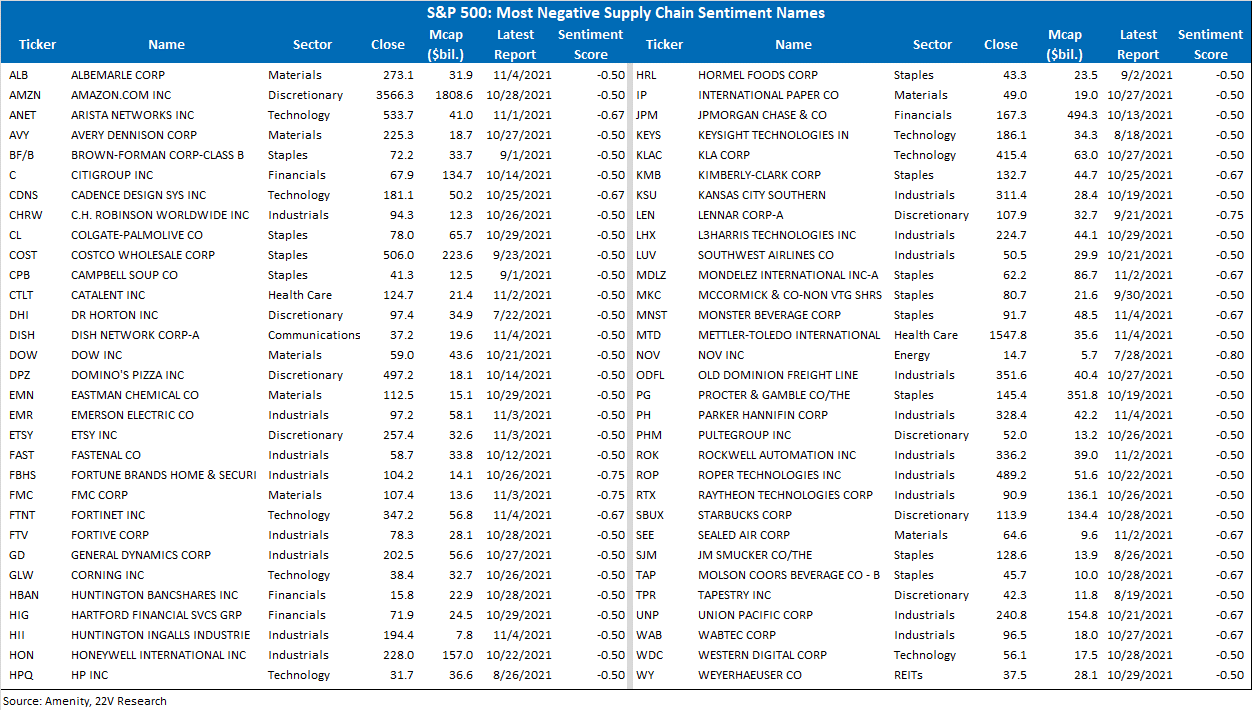
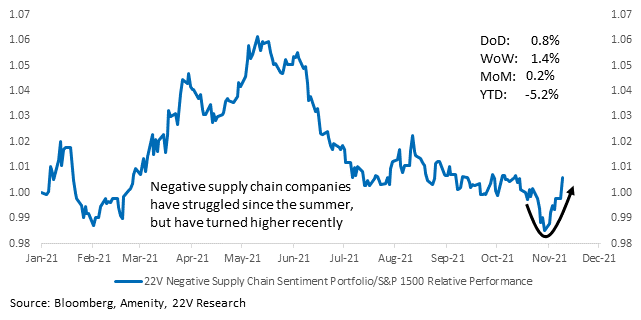
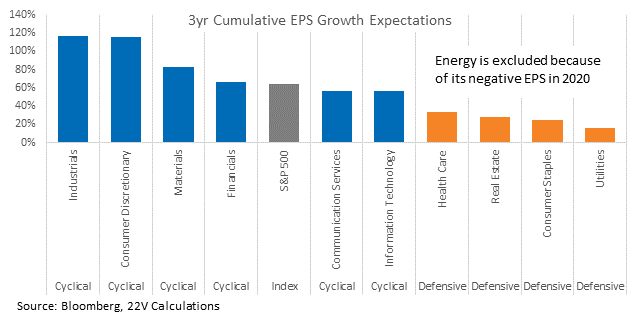
In addition to some domestically focused cyclicals, we are interested in being long companies that have been hurt the most from supply chain constraints. As we noted in a Quant report this morning, a basket of stocks with the most negative supply chain sentiment readings has bounced significantly over the past few weeks. The basket has been under intense pressure since August and assuming the improvement in supply chains continues, this basket will continue to outperform (basket of stocks at the end of the report). Also, Cyclical PE remain depressed relative to Defensives and Cyclical’s continue to have much stronger expected earnings growth.

Full report below…
MARKET VIEWS: It was a relatively quiet night, but UST yield volatility remains high. Two days ago, UST yields gapped up, then they moved down significantly yesterday, and now they are basically back to where they were two days ago. China continues to be an overhang on UST Yields, but downside risk yields, FROM HERE, is limited. Supply chains are easing and although that create some downside risk to short term inflation, the strong demand backdrop biases long rates higher. Strong income growth, the unprecedented wealth effect, high Capex expectations and a positive Auto impulse are supporting the strong demand backdrop. If UST yields do move back toward their recent high (1.69 on 10/21), bond volatility will likely remain elevated and stock volatility would have some short term upward bias. The S&P would consolidate and internal rotations would become more important.
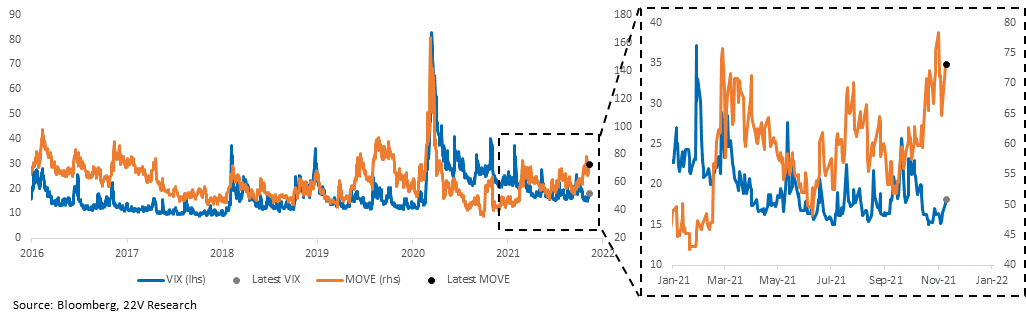
Keep in mind that the VIX moving somewhat higher would not lead to a sharp correction in the S&P (defined as -7 to -10%). Implied real high yield rates remain at historically low levels. While that remains the case, don’t expect a sharp move lower in equity prices. It would take a dramatic shift in Fed signaling or a shock to change the low real implied yield backdrop.
If 10yr yields do backup they would be a headwind for Tech stocks. Tech stocks are currently overbought with 75% of Nasdaq names trading above their 50-day moving average. To the extent that Tech consolidates, look for some reallocation into other domestically focused Cyclicals like Banks, Retail, and Small Caps. Energy and Materials continue to benefit from the strong developed world demand backdrop as well.
Tech’s relative performance after an overbought condition is slightly worse than normal through 3 months, but slightly stronger than normal through 6 months. In short, don’t use an overbought condition to short Tech. As we have noted many times, even at as high as 2.5% on 10yr, Tech stocks will still look unusually attractive on cash return yield basis relative to 10yr.
In addition to some of the domestically focused cyclicals, we are interested in being long companies that have been hurt the most from supply chain constraints. As we noted in a Quant report this morning, a basket of stocks we the most negative supply chain sentiment readings has bounced back significantly over the past few weeks. The basket has been under intense pressure since August and assuming the improvement in supply chains continues, this basket will continue to outperform (basket of stocks at the end of the report).
CYCLICAL RELATIVE TO DEFENSIVE UPDATE: Cyclicals have significantly outperformed Defensives this year and although that has led to some catch up in the PE spread between the two groups, Cyclicals are still unusually inexpensive relative to Defensives.
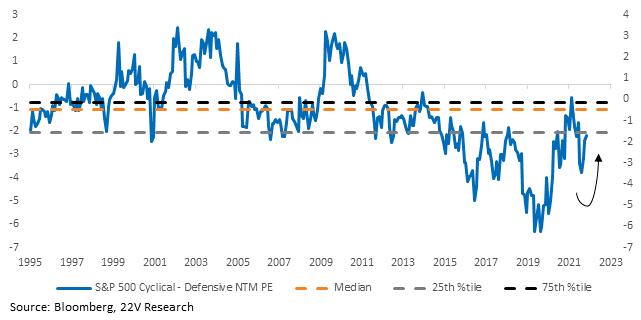
Cyclical PEs are still depressed relative to Defensive PEs and Cyclicals are expected to lead earnings growth through 2023.
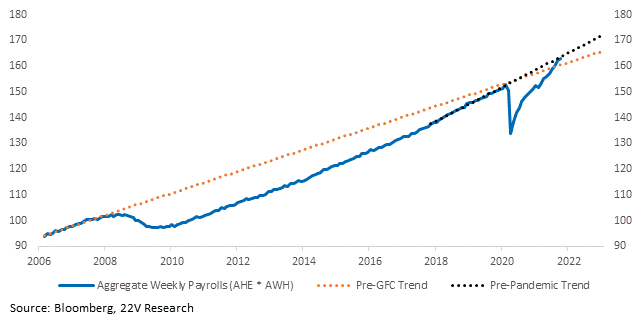
TWEET HIGHLIGHT OF THE DAY: From Luke Kawa @LJKawa. “It took 13 years to get back to the pre-recession trend for aggregate labor income after the GFC. Probably going to take less than two years from the onset of the COVID recession.” This is why demand growth is very strong and focusing on real AHE growth, which will look bad today because of YoY CPI comps, but will look really good 3/4 months from now, is misleading.
Negative supply chain sentiment stocks here.