SUMMARY: Despite strong US demand growth and upside inflation risk, until investors get comfortable with China risk dissipating, the inflation outlook (inflation uncertainty = economic uncertainty) and what the winter will bring for COVID 10yr yields will be pinned. The China credit impulse remains near its lows and seem unlikely to move much higher near term, China stringency measures are moving back toward last summer’s high as COVID cases increase and reopening stocks have significantly underperformed over the past month (-8.6% relative MoM). To be clear, even if economic activity remains firm, and it likely will (see continued Cyclical outperformance), COVID uncertainty helps anchor 10yr yields and is impacting reopening.
The consequence of range bound 10yr yield and strong demand growth in the US is being long Homebuilders, Retail and strong USD beneficiaries. Small caps should continue to move higher.
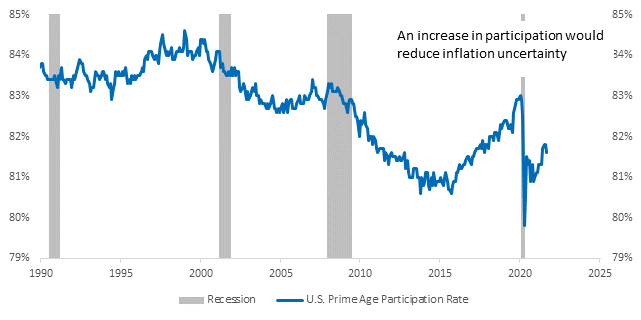
On inflation uncertainty, which is also impacting rates markets, we should get some new information today. In short, strong job growth with increasing participation would LOWER inflation uncertainty (labor supply is responding, so we can have job growth without too much inflation) and should help 10yr yields rebound on the day. If participation declines, which the Fed has made clear it doesn’t expect, inflation uncertainty will remain elevated and 10yr yields anchored. A lower participation rate means downside risk to unemployment rate and upside wage growth. Inflation uncertainty = economic uncertainty = anchored long rates. Short rates would likely reverse higher as fed rate hike expectations increase.
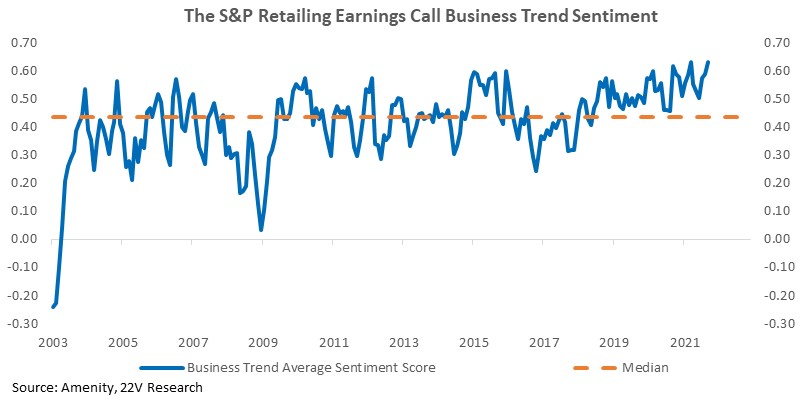
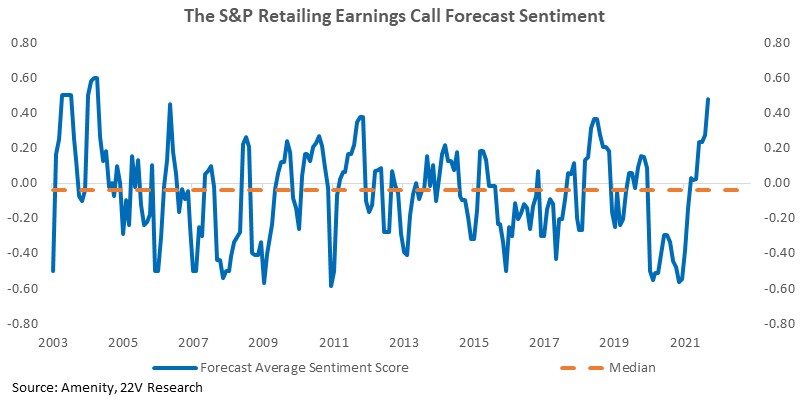
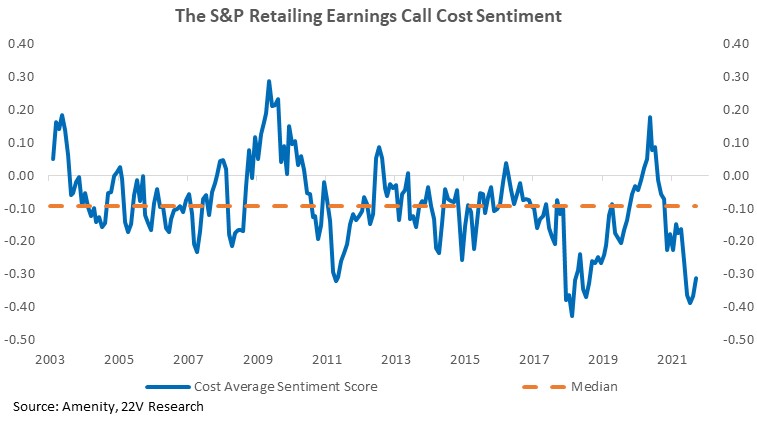
We finish up on our long retail idea today and the charts should be looked at. Using the Amenity natural language processing (NLP) tool we find that retail business trend sentiment is unusually strong and forecast sentiment is strong (For reference Forecast sentiment => Reporting of guidance revision around EPS, revenue, sales, liabilities, expense, etc. or changing expectation). On costs, which are the major worry. Retailer Cost sentiment, which is still negative, has turned up a bit. With Vietnam factories coming back online and supply chains appearing to generally improve, cost sentiment should improve going forward. Our sentiment indicator on supply chains has improved meaningfully. Bottom line, costs in the retail space are likely to become less bad and the demand side should remain strong given the outlook for jobs.

Full report below…
MARKET VIEWS: Global 10yr yields remain pinned and its tough to expect a sharp increase in 10yr yields until investors get comfortable with China risk (slowing growth/ COVID wave), inflation outlook (inflation uncertainty = economic uncertainty) and what the winter will bring for COVID. Although the economic impact of COVID is diminishing, as we pointed out in our COVID update yesterday, China stringency levels are moving back toward levels reached last summer and global case growth is increasing. The China credit impulse remains pinned at low levels as well. Bottom line, it tough to expect a sharp increase in global 10yr yields if China economic uncertainty remains high.
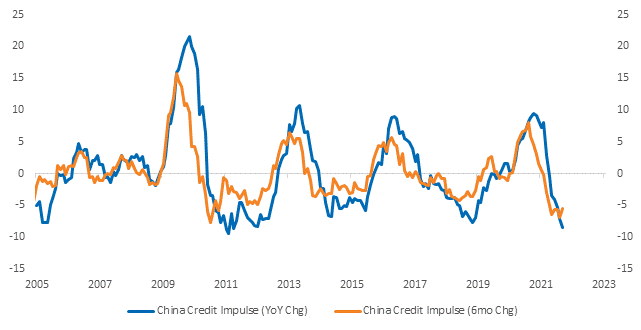
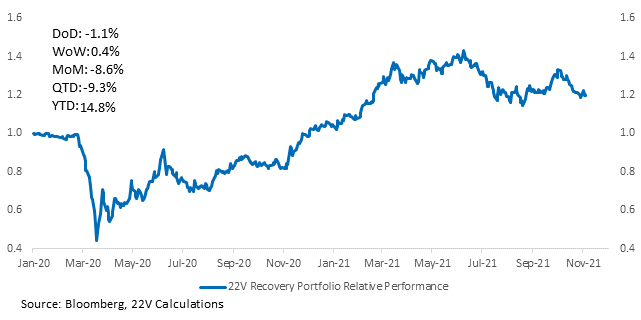
COVID uncertainty is impacting reopening stocks which have lagged meaningfully over the last month despite a much stronger than expected demand backdrop and broad outperformance of Cyclicals. Reopening names are -8.6% relative MoM and were -1.1% relative yesterday. Cyclicals were +1.3% yesterday relative to Defensives. To be clear, even if economic activity remains firm, and it likely will, COVID uncertainty helps anchor 10yr yields.
Today we are hoping to learn something on inflation uncertainty. In short, strong job growth with increasing participation would LOWER inflation uncertainty and should help 10yr yields bounce back on the day. If participation declines, which the Fed has made clear it doesn’t expect to happen, inflation uncertainty will remain elevated and 10yr yields pinned. Short rates would likely reverse higher.
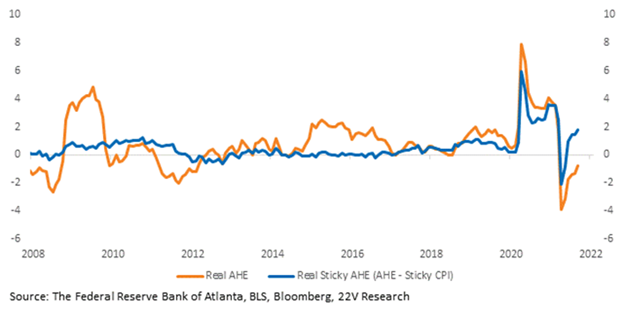
We are focused on wage growth and how real wage growth breaks from here. Real wage growth was negative, very short term, because of the extremely tough inflation comps. As wages continue to grind higher and inflation fade, real wages are headed higher. When we adjust nominal wage growth to the Atlanta Fed’s STICKY inflation measure, it shows strong real wage growth. Sticky inflation is 72% of CPI, so we feel comfortable making this adjustment. The consumer demand backdrop remains firm.
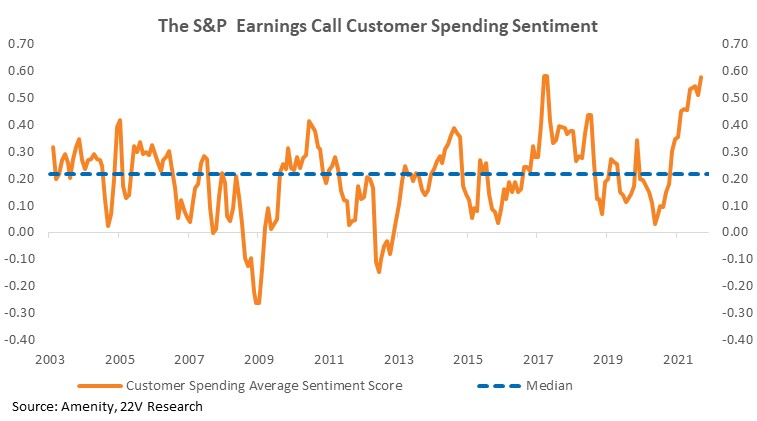
LONG RETAIL: The consumer backdrop is firm and likely to remain so as 1) the flow of savings remains positive, 2) the unprecedented wealth increase from housing / stock prices 3) strong labor markets. That helps explain why customer spending sentiment reached one of the highest levels on record this earnings season. This fits with the unusually high level of retail sales over the past few months and strong personal spending data ex-auto.
For the retail names in particular, business trend sentiment is very strong.
The forecast sentiment for the retail space was very strong. For reference Forecast sentiment => Reporting of guidance revision around EPS, revenue, sales, liabilities, expense, etc. or changing expectation; Can also be an analyst or independent company revising estimate.
Here is the very interesting part, Retailer Cost sentiment, which is still DEEPLY negative, has turned up a bit. With Vietnam factories coming back online and supply chains appearing to generally improve, cost sentiment should improve going forward.
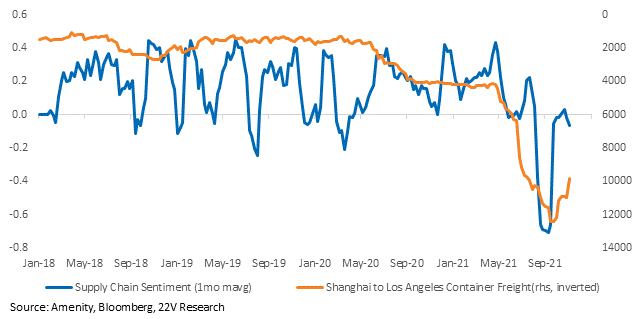
We follow supply chain sentiment closely and it has improved dramatically from the lows this past summer. It has stopped improving recently, but the improvement over the last few months suggests lower freight rates. We like being long retail on a relative basis.