SUMMARY: We are hosting the first iteration of our weekly macro summary webinars this Friday at 10:30 AM ET. We will provide a brief overview of the most important developments in Strategy, Quant, Washington Policy, and Technical Analysis. Registration link here.
MARKETS: We hosted our first macro dinner in almost two years last night with our economist, Gerard MacDonell, and a group of clients It was a fun night and we can’t wait to do more. Let us know if you would like to be involved in one. Gerard made a good case for why demand growth will remain above trend for the next 6 months. After that, expect real GDP to slow back down to the post-GFC trend of roughly 2%. Above 2% or a new higher trend is possible though and the elements are in place for that to happen. And, as one client pointed out, why not a credit boom? Just about everyone agreed with the strong demand backdrop for the next few quarters and added that energy prices are biased higher. A few clients pointed to the strength in commodity currencies (see below) which are close to breaking out vs the USD. That points to 1) a strong demand backdrop and Energy outlook and 2) China outlook likely improving. Lower China coal prices and tighter high yield spreads are likely helping commodity currencies.

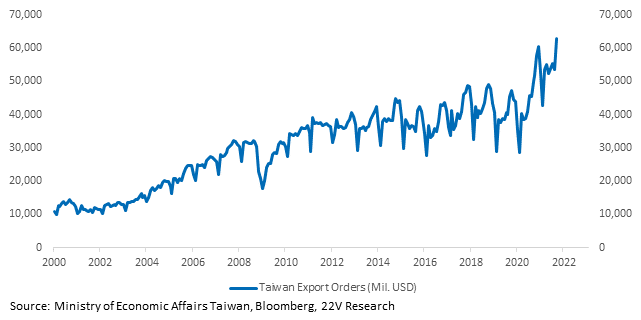
Although nobody pitched emerging markets, almost everyone agreed they are a buy given strong global demand and likely improvements in supply chains over time. FYI, Taiwan export orders surged more than expected to an all-time high in September, almost a third of which were from US companies. Export figures from South Korea showed similarly strong growth in the first 20 days of October, with shipments to the US up 37.1%. Maybe that is all double ordering, but given rising wage growth and the positive flow of savings, US demand growth is likely to remain firm.
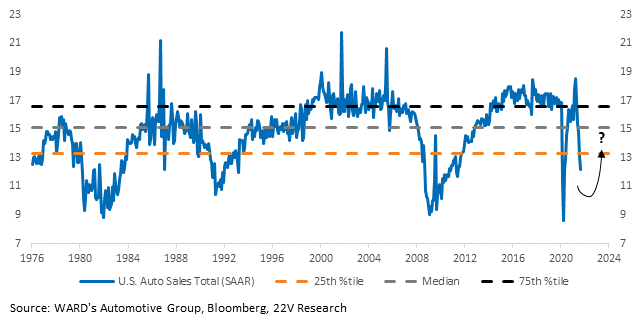
Autos are likely to add to GDP. As Gerard pointed out, “if auto production gets back to normal within a couple quarters, then the increment to GDP growth from that source alone would be about 2 percentage points each quarter on average for both quarters. Moreover, the drag from this sector over the past couple quarters would dissipate. So, the swing in the swing could be closer to 3 or 4 percentage points on the GDP growth rate.”
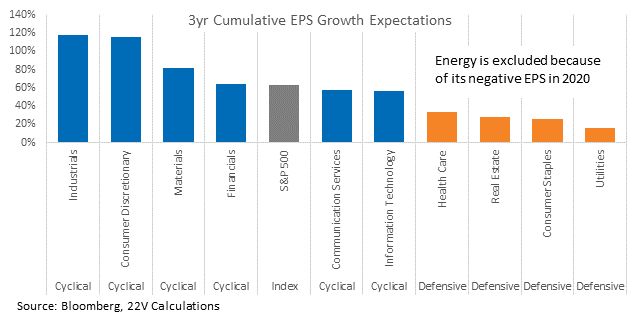
An intense debate centered around how high 10yr yields could go. Most assumed significantly above 2% is VERY HARD (structural reasons for pension funds to own bonds + yield spreads vs the rest of the world) unless there is a significant change in the long-term inflation/neutral fed funds rate outlook. Two things to think about here. If demand growth is above trend for the next 6 months, which we have high conviction in, 10yr yields will be biased higher and Cyclicals will outperform. Large cap Tech will be fine. After that ~6 months (or a few months before, tough to tell now), narratives are likely to shift toward a toping of growth/yields, reducing support for Cyclicals as economic activity moves back toward its post-GFC trend. Unless the Cyclical PE remains depressed relative to Defensives’
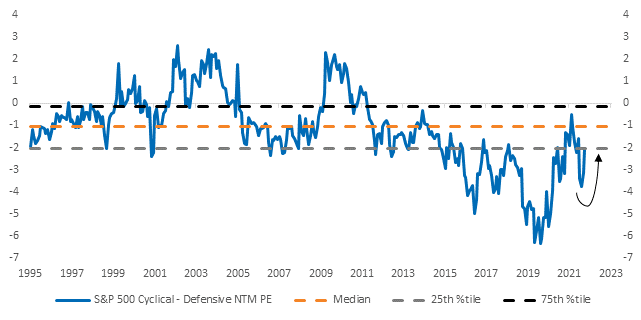
It will be tough to be negative on Cyclicals relative to Defensives, even if economic growth moves down to trend given medium term (3yr) expected earnings growth of Cyclicals relative to Defensives.
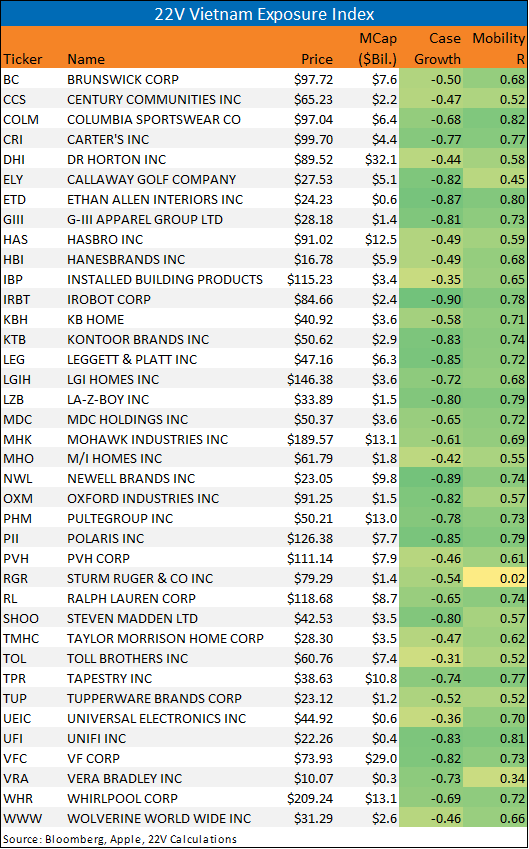
Side note…there were a bunch of fun ideas around ‘what if’ scenarios. As an example, what to own if supply constraints to turn into supply gluts next year and demand stays firm (discount retailers are the winners). It was a fun night and we can’t wait to do more. Let us know if you would like to be involved in one. If supply chains clear up, our Vietnam levered index is likely to move significantly higher on a relative basis. It has lagged and everyone seems to hate these names near term.
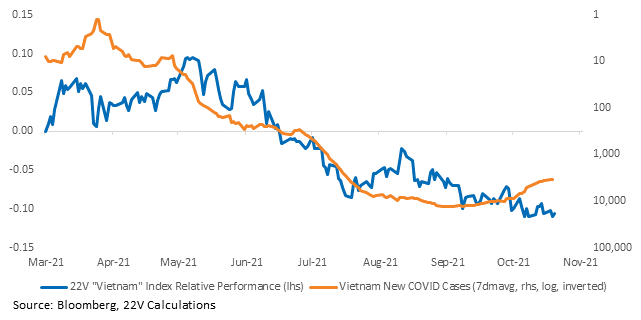
Constituents here. There are caveats to our methodology: it is a short history, many of the stocks have moved around for reasons well beyond supply chain issues, some might not have ANY Vietnam exposure at all. That being said, it is a broad list of stocks and we think it should be used as place to look for ideas.