Back Shoot Around

22V Afternoon Shoot Around: Hedges for Higher Treasury Yields and AI Infrastructure

Published on September 28, 2026

∙ Download the PDF Report

By

Dennis DeBusschere

Bottom Line: Our Call

The Fed and/or 10yr yields will keep pushing rates to a place that accomplishes the goal of slowing economic growth and inflation. Our call is 10yr yields around current levels WILL deliver a mild slowdown. The RISK is the current level of 10yr yields doesn’t slow economic growth enough to respect the economic speed limit (~2% real GDP growth).

Relevant News: Risk if Growth More Resilient

IF growth proves more resilient than we expect, 10yr yields will move higher as the Fed shifts to “doing what it takes” to lower inflation, accepting the higher recession probabilities that come with that stance. We don’t think this is the modal path, but the risk is emerging. A lower unemployment rate (below 4%) with still well above 2% Real GDP growth and above 3% core PCE inflation would increase those odds.

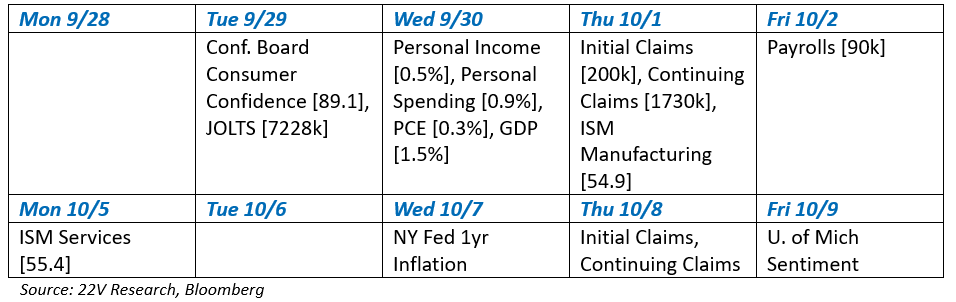
Things to Watch [Consensus, Results]:
Strategy:

Options Strategies to Risk Manage Higher Treasury Yields – (HERE)

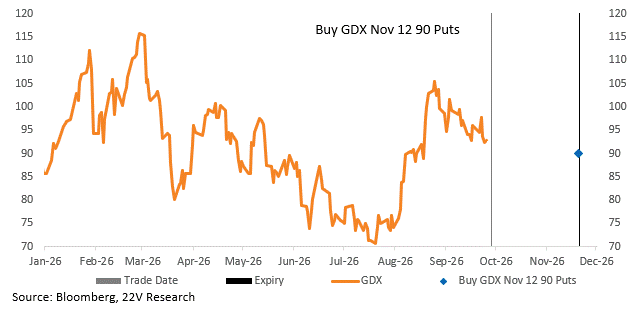
One of our preferred methods for positioning for lower probability outcomes is through options where the vol setup is favorable. Jeff Jacobson, 22V Derivatives specialist, thinks that the options on the S&P 500 or NASDQ are not the best vehicle to hedge against higher rates because of Tech’s resilience to higher rates and large index weight. We agree given AI activity will NOT be the source of weakness. Financials (XLF) puts have worked well, but now Jeff thinks the risk reward in the options has deteriorated. The vol setup is better for short EFA (Europe) and short GDX (Gold), both of which come under pressure from a stronger Dollar (a likely outcome from higher US yields).
Data Infrastructure / Commodities:

AI Infrastructure and Commodities Monitor – (HERE)

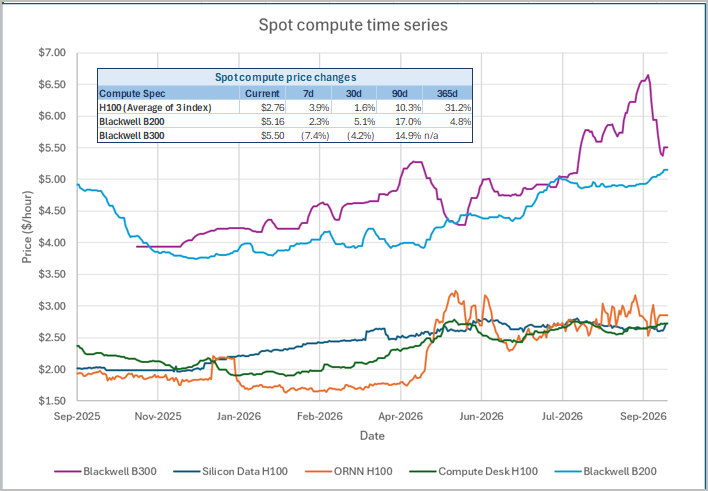
Meta’s viral Muse launch provided an early example of how consumer agentic AI can quickly translate into greater compute demand, while Anthropic’s expected IPO should bring increased disclosure and greater clarity around frontier lab economics. At the same time, catalysts are building across the Space Economy, with SpaceX’s Flight 14 and Google’s upcoming orbital TPU test highlighting growing interest in orbital data centers as launch and terrestrial infrastructure cost curves converge. Powered shell pricing also remains strong, with CIFR’s revised Barber Lake contract setting what appears to be a new high, while Maryland and Virginia are providing early examples of regulators favoring clearer development processes over outright data center moratoriums. Compute fundamentals remain supportive as B200 and B300 spot prices continue to rise, and improving revenue-per-MW economics suggest potential upside to longer-term neocloud estimates as AI demand continues to outpace the buildout of new capacity.
DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.