

I Recent quarters of euro area economic performance have been characterized by a shift in activity towards the Southern periphery and especially Spain. At the same time, especially Germany’s economy has stagnated since 2019 and has recently been joined by slowing activity in a France weighed down by persistent political instability and concerns about the fiscal outlook. The euro area center and periphery have to a degree switched places. The latest PMI survey data, however, suggests that the German economic outlook is increasingly being shaped by a combination of improved prospects from the coming fiscal stimulus and a cyclical manufacturing sector rebound aided also by a more benign Transatlantic trade environment. Growth prospects in the euro area are hence broadening, leaving France as the main near-term source of concern.
Eurozone September composite output PMI rose to a 16-month high of 51.2 and business activity a 9-month high 51.4. German composite output PMI similarly rose to a 16-month high of 52.4, pushed up by a strong reading in the services sector PMI, swing to expansionary territory at 52.5, reaching levels comparable to the cyclically rebounding German manufacturing sector. German economic expansion in other words looks both broad and solid right now, compared to the last 5 years. It is difficult to attribute this to anything other than the dramatic fiscal shift initiated in the spring.
The near-term situation in France is in many ways as indicated by September PMIs the mirror opposite of Germany – composite, services and manufacturing PMIs all point to contraction at 48.4, 48.9 and 45.9 respectively. The persistent political uncertainty in France clearly appears to be taking a toll on French businesses and consumers. Lastly, peripheral (excluding France and Germany) euro area PMIs continue to point to economic expansion also here, as composite, services and manufacturing at 51.8, 52.1 and 50.9 remained above 50.
While the euro area’s growth prospects are hence broadening to increasingly include Germany, it however important to keep in mind that material aggregate growth constraints remain going into 2026. French political clouds will not dissipate, and while NGEU spending will continue to boost investments in especially Italy and Spain next year, too, domestic fiscal policy here is likely to turn modestly contractionary in 2026. As increases in European defense expenditures disproportionally include non-euro area members, Germany will in other words be the euro area’s principal fiscal agent in 2026. This will help boost German growth to around 1.5 percent for the year, well above potential growth. Germany has the fiscal capacity and government intent to maintain a material stimulus level for a number of years, though non-defense and non-public investment categories of spending, not excluded from the national debt brake (especially social spending), will soon require material partly offsetting fiscal consolidation and reform. A major question hence remains whether German fiscal stimulus can ignite a more general cyclical rebound in the economy, driven by a mix of business investment and household consumption? This, however, remains doubtful, as German exports will continue to face headwinds from Chinese competitions, US tariffs, and stubbornly high domestic energy prices, in all probability dampening business investments in Germany. Household consumption levels have been increasing recently, but will, as the labor market and wages will remain rangebound, require a broad-based rebound in consumer confidence (figure 1) to rise much faster than GDP and help power the economy upwards. Such a development is not, however, likely at least until the war in Ukraine ends.
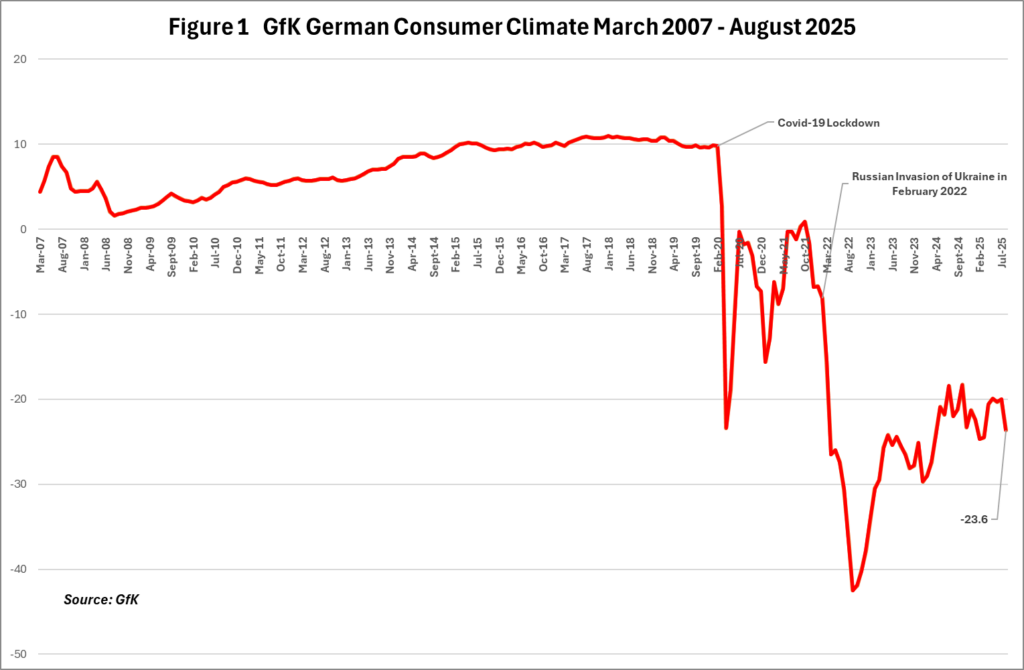
Figure 1 shows clearly how the Russian invasion of Ukraine and the associated increase in energy prices and overall inflation in early 2022 onwards caused German consumer confidence to crater to unprecedentedly low levels. The return of German inflation levels to the ECB mandate of 2 percent (and real wage levels to trend) have evidently not caused consumer confidence to fully recover, suggesting that this requires an end to fighting in Ukraine. This outcome though, as discussed in earlier notes, are not likely in 2026.
Improving German growth prospects from fiscal policy hence solidifies the overall euro area economic outlook and that the ECB will remain on the sidelines well into 2026. The war in Ukraine must end though before a general consumption driven cyclical upswing in Germany or the euro area is likely.
II The implications for the global security situation of the war in Ukraine is certainly profound at the political level. Yet the speech of Ukrainian president Zelensky at the UN General Assembly this week underlines that the perhaps most far-reaching implications of the war is the rapid deterioration in general physical security that the development of drones and AI triggered by the war will unleash. Zelensky, whose country is uniquely at risk in the world right now from all drone and AI related developments, warned global leaders that these trends will affect everyone whether at war or not. Zelensky bleakly warned how “weapons are evolving faster than our ability to defend ourselves“, and went on to say (my emphasis);
“Now, there are tens of thousands of people who know how to professionally kill using drones. Stopping that kind of attack is harder than stopping any gun, knife, or bomb. This is what Russia has brought with its war.
It used to be that only the strongest countries could use drones – because they were expensive and complex. Now, even simple drones can fly thousands of kilometers. War tech doesn’t care about geography anymore – it’s now reshaping it.
Just recently, airports in Europe had to shut down because of drones. Authorities couldn’t even say what kind of drones they were, who sent them, or from where.
Last week, North Korea announced the test of a tactical strike drone. That means – even countries with limited resources can now build weapons that are dangerous to their neighbors.
Ukraine – and nations like Saudi Arabia – know all too well how dangerous Iranian attack drones are. But what happens when all the types of drones become available even to small terrorist groups or cartels? The world moves too slowly to protect itself. And weapons move fast.
Now, companies are already working on drones that can shoot down other drones. And it’s only a matter of time – not much – before drones are fighting drones, attacking critical infrastructure, and targeting people – all by themselves, fully autonomous, and no human involved – except the few who control AI systems.
We are now living through the most destructive arms race in human history – because this time, it includes artificial intelligence. And if there are no real security guarantees – except friends and weapons, and if the world can’t respond even to old threats, and if there’s no strong platform for international security – will there be any place left on Earth that’s still safe for people?
We need global rules – now – for how AI can be used in weapons. And this is just as urgent as preventing the spread of nuclear weapons.
We need to restore international cooperation – real, working cooperation – for peace and for security. A few years from now might already be too late.
10 years ago, war looked different. No one imagined that cheap drones could create “dead zones”, areas stretching for dozens of kilometers where nothing moves, no vehicles, no life. People used to imagine that only after a nuclear strike – now it’s drone reality. Mass-produced, simple drones, and without AI – yet.
Ukraine doesn’t have the “big, fat” missiles dictators love to show off in parades. But we do have drones that can fly up to 2,000–3,000 kilometers. We had no choice but to build them – to protect our right to life.
Control over the sea used to depend on having a big navy. Ukraine doesn’t have a big fleet. But we succeeded in the Black Sea – we pushed what’s left of the Russian navy into remote bays. And we did it with sea drones. That’s how we protect our ports and maritime trade routes – because Russia has left us no other choice.
And our “Spiderweb” operation, when cheap drones destroyed or damaged dozens of expensive Russian strategic bombers, became a real example for special forces around the world of what new weapons can do to old systems. These very Russian bombers attacked our cities.
And none of this would have happened if Putin had not started this full-scale aggression, full-scale war.
And every year that this war goes on, weapons become even more deadly. And only Russia deserves to be blamed for this.
To protect lives, Ukraine builds underground schools and underground hospitals. To protect lives, we have to spend more on protecting power stations from drone and missile attacks than on building sports facilities or cultural infrastructure. Ukrainian farmers are learning how to protect their equipment from Russia’s FPV drone strikes, and for them, that challenge is far greater than climate change. Russia’s war has put us in this situation. But do you have protection against similar threats?“
Obviously, Zelensky has a political incentive and intent to blame Russia for these developments at the UN in order to secure increased global support in Ukraine’s struggle against Putin’s aggression. But this does not change the seriousness of his warning to the world. The spread of low-cost drone weapons soon enhanced by AI will have profound implications for physical security everywhere. High priority buildings anywhere can no longer be protected by a few concrete blocks in front of them to protect against truck bombs, but must be equipped with drone denial technology; Ukraine and soon the EU may be building a “drone-wall” on their Eastern border to deter future Russian aggression, but the ability to constantly detect and destroy drones coming across national borders will soon be a prerequisite for any nation; it must be assumed – once hostilities end – that highly qualified personnel equipped with knowhow and 3D printers will seek employment with criminal gangs or terrorist groups around the world, granting non-state actors drone capabilities similar to Russian and Ukrainian armed forces today. Recalling that Afghanistan was invaded by a US-led force because the Taleban has hosted Al-Qaeda when it struck on 9/11, it is clear that Western and other military alliances must increase their ability to strike against such drone-equipped non-state actors anywhere in the world; and finally drone-based combat will increasingly dominate previously “labor intensive battlefields” and replace some soldiers enabling countries with smaller populations (like Ukraine relatively to Russia) to sustain military campaigns against larger adversaries – this may reduce the threshold for political leaders in some countries to go to war.
The political implications of the drone future Zelensky warns about will be hard to predict, yet at least some market implications ought to be relatively clear. Drone defenses and related equipment is not going forward just a military or law enforcement thing, but will be an integrated part of all critical and most regular urban infrastructure. The investment scope for this future market will be immense. Cultural or sporting events involving large crowds must in the future entail significant drone defenses, posing material challenges for events like marathons, iron men races, or say the Tour de France cycling race. Cost-efficient drone defenses of this required scale have not yet been developed, and will require a significant investment of risk capital.
In sum, Zelensky has warned everyone that what is being developed on the battlefields in Ukraine will very soon affect all of us. It may not be a future we will recognize.
Jacob

