

July FOMC: It’s About the Supply-Side
- The meeting saw the first double dissent by Fed Governors since 1993, with both Waller (seemingly a lock) and Bowman (probable) dissenting dovishly.
- Powell’s press conference made clear that for most of the FOMC, the economy is being dominated by a set of supply-side shocks. Due to tariffs’ supply shock, the mandates, especially their risks, will be in tension for some time. Labor supply growth is very rapidly slowing so focus on the unemployment rate (and claims), not NFP. Powell also noted easy financial conditions.
- This supply-side focus combined with the quip that naively following the data would actually be pulling them hawkish, suggests that Waller’s dovish case is not succeeding in persuading the rest of them. Only the data, particularly inflation data more dovish than the 3.1% q4/q4 core PCE forecast in June, will do that.
- 3x roughly 50% priced meetings over the rest of the year seems a good place for markets and suggest Powell accomplished his data dependence goals for the day.
- The odds of 0x, 1x, and 2x cuts in 2025 are each roughly 1/3, given the uncertainties associated with the inflation outlook over the next few months. Another solid employment report might tip that further, if we see enough stability to merit urate forecast downgrades.
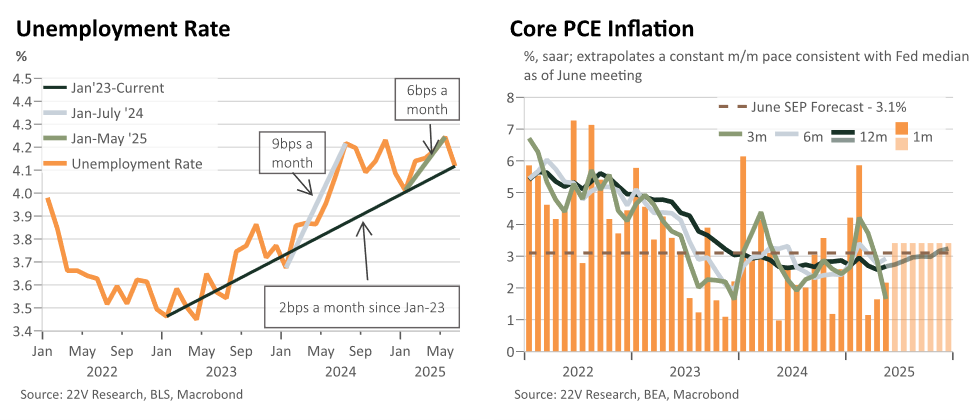
“In the labor market, conditions have remained solid.” During the press conference, Chair Powell’s description of the labor market focused intently on the stability of most measures of slack’s over the past 6-12 months, despite the slowdown, with further negative benchmark revisions to come, seen in the NFP data. This strongly refuted Gov. Waller’s logic that the slowdown in NFP was a demand-led phenomenon and was meaningfully concerning enough to warrant a preemptive dovish response. “The main number you have to look at now’s the unemployment rate because the demand for workers has come down but so has the breakeven number in tandem.” This is not new[1], but it is important in a world of especially supply shocks and deteriorating data quality (a secular and especially post-covid phenomenon). This aligns with our own work which suggests that the breakeven unemployment rate has fallen from ~300k in late-2022 to at most 100k now, probably somewhat less, and is headed to 25-50k within a year (see more here and here).
The line from Powell on the labor market I struggled most with was a caution that, “the fact that it’s [the labor market] getting into balance due to declines in both supply and demand is suggestive of downside risks.” I suppose if one allows for the possibility of a very rapid rebound in labor supply, highly unlikely given demographics, or supposes that negative growth might be more likely to generate nonlinearities even if slack is only mildly impacted but that seems an idea the experiences of demographically challenged economies don’t necessarily agree with but are minimally tested in history.
“We will through our tools make sure this does not move from being a one-time price increase to serious inflation.” Powell’s descriptions of the underlying inflation dynamics noted that while the return to the 2% target, or something approximately close enough to it, is not yet complete, with inflation “a bit above 2%… even excluding tariff effects,” they have made substantial progress.
It is a “reasonable base case” that tariffs are a one-off shock to the price level and inflation. Average effective tariff rate estimates “are not moving around much at this point, at the same time there are many uncertainties left to resolve.” The tariff shock is likely though to take a substantial amount of time to radiate through directly impacted prices; “I think we have learned that the process will probably be slower than expected at the beginning. But we never expected it to be fast.” There is a risk “to be assessed and managed” that the impact of the tariffs on inflation is not as a short-lived and simple in its impacts as they hope for. The post-covid inflationary experience also showed that even narrow core goods price shocks can radiate out into related goods and eventually core services over a number of years. Powell noted that their estimates suggest that of the 2.7% core PCE inflation they see 0.3-0.4% of that currently due to tariffs, consistent with the view that inflation remains a bit too high on a current underlying basis.
“We are always going to be dealing with the whole, all of inflation.” This was one of the more hawkish lines in the inflation discussion, above and beyond those calling for patience in assessing the gradual inflow of the data, because it implies that after being burned by sectoral rotations in inflation before they hesitant to (my words here) assume the good continues and the bad resolves away. The medium-term inflation forecast still matters but they can’t afford to ignore unhelpful data. Over the past year, services inflation has come “down nicely” while core goods inflation is “going up.” That’s partly “partially because of tariffs. It’s also partially because we have restrictive policy in place” which is weighing on services inflation.
“We will through our tools make sure this does not move from being a one-time price increase to serious inflation. We want to do that efficiently, though, efficiently, and that means we want to do it, if you move too soon, you wind up maybe not getting inflation all the way fixed and you have to come back… But in the end, there should be no doubt that we will do what we need to do to keep inflation under control. Ideally, we do it efficiently.” The ghosts of ‘transitory’ loom large in the current debate.
“You could argue we are a bit looking through goods inflation by not raising rates. We haven’t reacted to new inflation. But, I mean, I wouldn’t insist upon that.” While there were plenty of arguments from Powell which attenuated the case for dovishness, this line struck me as the most subtly hawkish because he noted that the choice to look-through the supply shock inflation by not moving to a more restrictive stance is itself an active policy choice informed by a set of views on inflation’s medium-term outlook and the risks to both sides of the mandate.
“We have made no decisions about September.” The data continues to be in the driver’s seat for September. But Powell’s hesitancy to fully endorse the June SEP as the appropriate current baseline felt hawkish. 2x cuts remain live but over the “Coming months we will receive a good amount of data” that will inform what the appropriate course of policy is.
Powell described the stance of policy as “modestly restrictive,” and that it appears that the “economy is not performing as though restrictive policy were holding it back inappropriately.” Similar to the recent outturns of the labor market data and the discussions of the unemployment rate again anti-dovish rather than outright hawkish in implication but it does suggest that the long-run dot is likely to be pressured higher over the fall and that most on the Committee, especially in real inflation-adjusted terms, see only a modest pull back towards neutral over the medium-term.
“Policy should be a little bit restrictive, somewhat restrictive because we want inflation to move all the way back to its target.” It’s worth remembering too that the median forecast saw a 2026 core PCE forecast of 2.4% in June, implying that real policy should remain a bit restrictive on that horizon, even with a 4.5% unemployment rate.
“If you saw that the risks are fully in balance that should imply you should move to a more neutral” stance of policy. We are not there yet and neutral may be a shifting goalpost too. But as the risks eventually, presumably, resymmetrize that will be the signal for easing.
While Powell may be been unusually definitive today, the emphasis on the unemployment rate has a long history with Fed leadership. Of course, it isn’t perfect but most of the criticisms focus on the now less en vogue inclusive peripheries of the labor market and cyclical labor supply dynamics (but these forces are usually highly correlated with the unemployment rate and somewhat separate from NFP). “The unemployment rate is probably the best single indicator of current labor market conditions,” Yellen in 2013. “I also would agree with you that the unemployment rate, while perhaps the best single indicator of the state of labor market, is not by itself a fully representative indicator,” Bernanke in 2013 during a wide ranging discussion on the impacts of labor market hysteresis, the importance of looking at broader slack measures, and of understanding underlying demographic reality. The experience with the Evans Rule as unemployment rate driven is also illustrative. Greenspan echoed a similar sentiment in 1996, noting the unemployment rate’s importance while putting NFP in the context of the supply-side; “tight labor markets are reflected in unemployment rates that remain low by historical standards… The average net increase in payroll employment, which was 240,000 per month over the first eight months of the year, slowed to 113,000 over the three months through November. That average increase is close to the sustainable growth in the labor force.” Greenspan has stuck to this view, noting in 2018 that “the unemployment rate, per se, is the best measure of finding out how successful the labor markets are.” ↑

