SUMMARY: If employment growth runs at a pace consistent with the recent trend of demand growth, the labor market would tighten (HERE). As a result, there are limits to how much more bond vol and 10yr yields will fall FROM HERE.
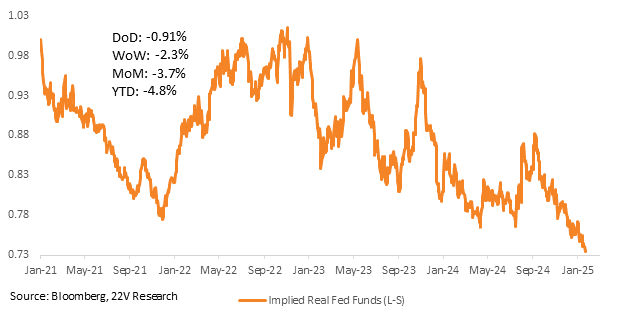
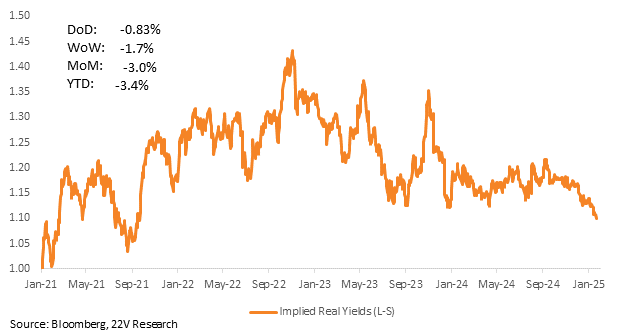
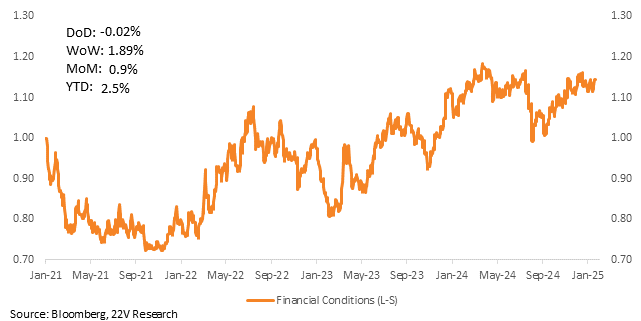
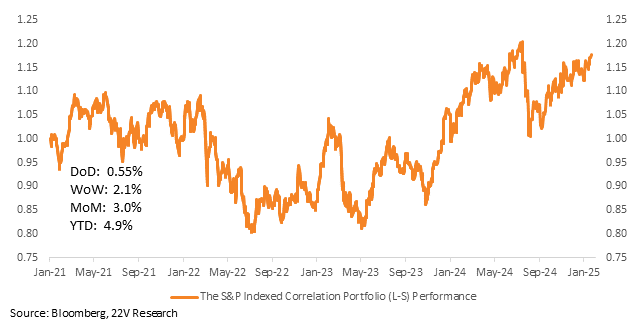
That doesn’t mean financial conditions will tighten, though. If bond yield/vol do not decline more. Stocks that benefit from a decline in the implied real fed funds rate, lower implied real yields (10yr – expected inflation), easier financial conditions, and lower correlations are all up significantly MoM. Relative to the stocks that benefit from the opposite conditions (higher real yields, tighter FCI, etc), MoM. The point being, 10yr yields around current levels just reflect stronger demand growth and higher r*.
Bottom Line – Rates are not in restrictive territory. The normal economic expansion should be expected to continue. Equity returns broaden out (happening). Unless a shock from Tariff policy comes to fruition.
Longer Term – There is downside risk to bond vol/10yr from lower population growth/immigration reversal. Put simply. Fewer people = lower GDP. Demand growth would be biased lower over time as potential GDP moves lower. 10yr yields and bond vol would have more downside risk in that scenario. That is a discussion for another time, though.
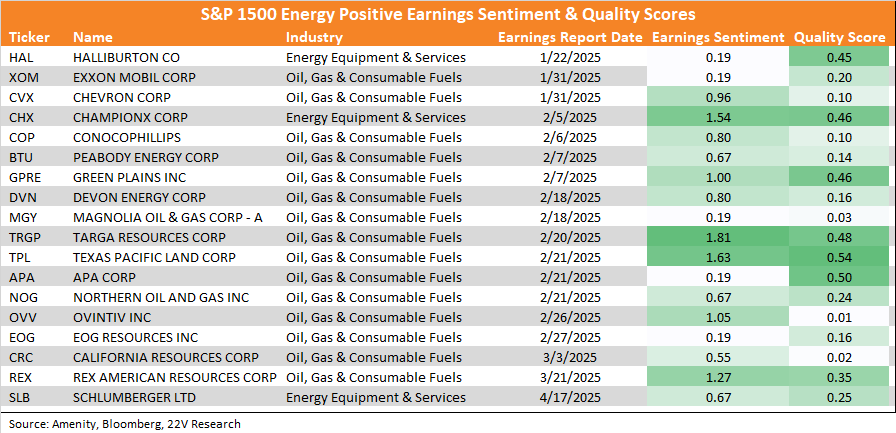
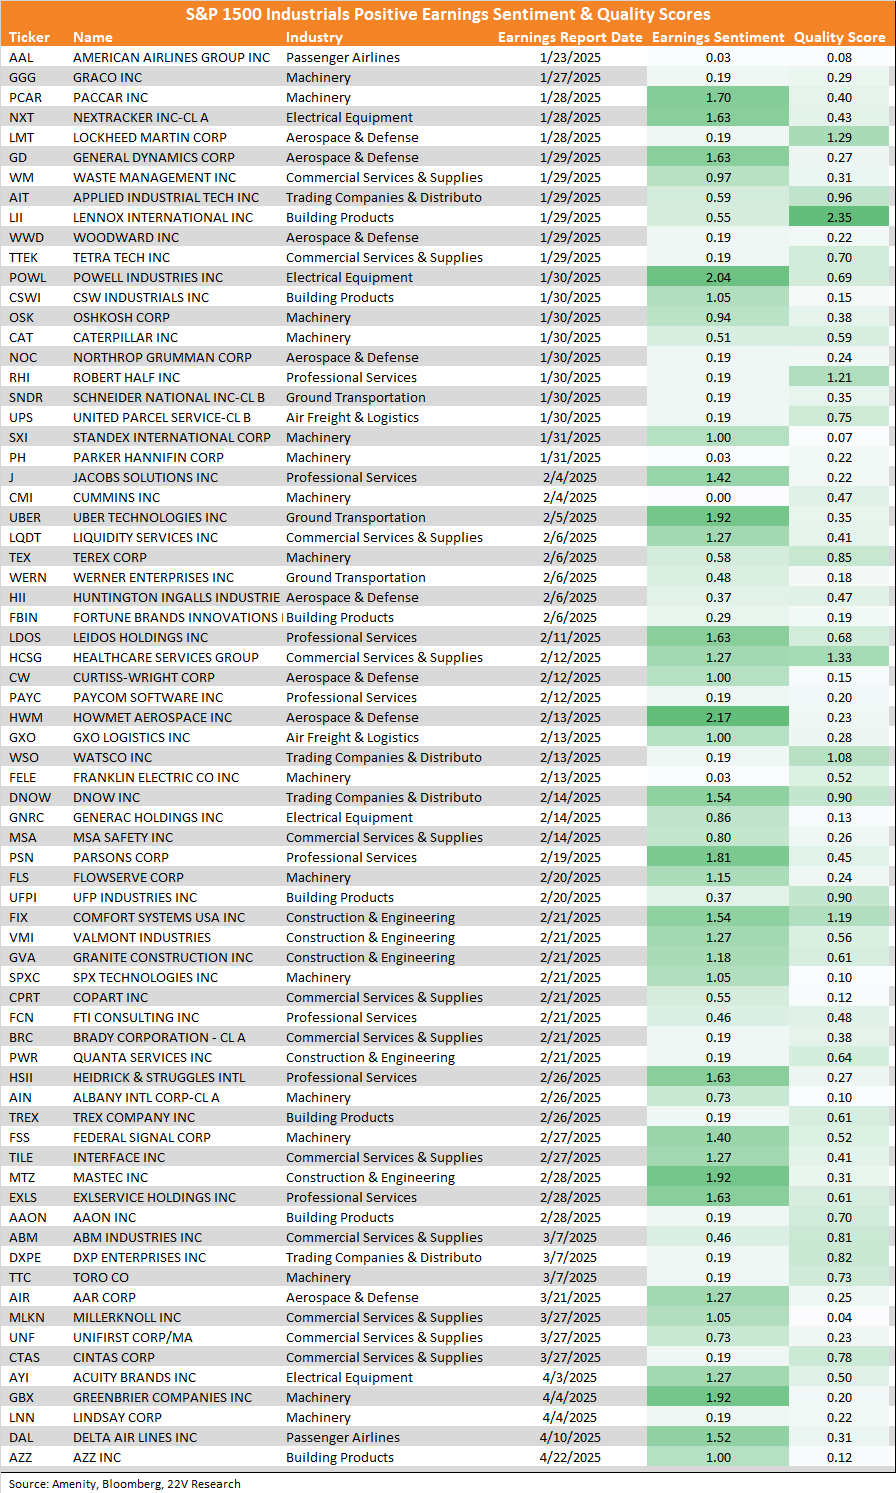
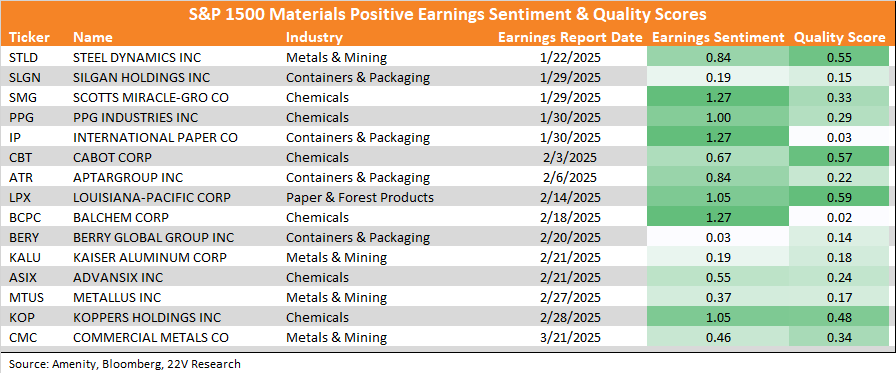
Looking for Alpha In Deep Cyclicals (Energy, Industrials, and Materials). Our view is that lower correlations will leave earnings beats/misses as the driver of returns. That is our focus now. Combining the high Quality Earnings with positive earnings sentiment scores (using an NLP tool we have used for many years) historically has generated better than index beat rates. We filter the Industrials, Energy, and Materials names to screen for the high quality/positive earnings names that could beat earnings this quarter. The list and more info are below. We can send a list for other sectors as well.
Full report below…
MARKET VIEWS: Stocks that benefit from a decline in the implied real fed funds rate, lower implied real yields (10yr – expected inflation), easier financial conditions, and lower correlations are all significantly higher MoM. Relative to the short side of the baskets (stocks that benefit from higher implied real fed funds, higher implied real yields, tighter FCI, etc.,). Exactly what should happen in a 3%ish demand growth and disinflationary backdrop is happening.
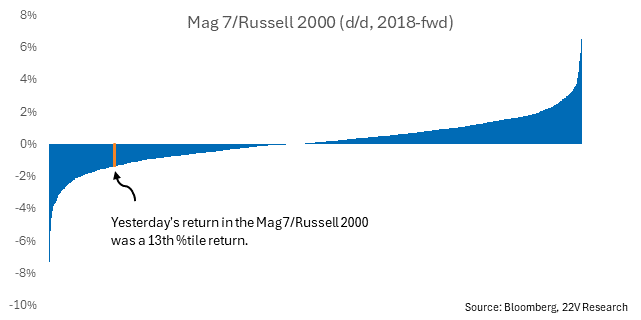
Mega caps had a 13th percentile underperformance relative to small caps. Broadening out of returns, as long as high earnings expectations are realized, is one of our 2025 themes (HERE). The firm demand growth backdrop suggests the expected 2025 improvement in earnings for small caps, Value, and Deeper Cyclicals will be realized.
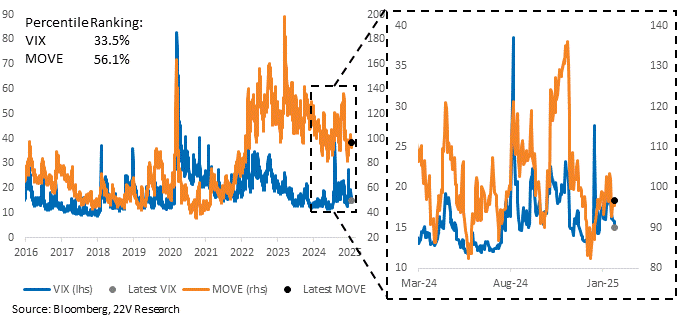
Bond volatility has declined along with the VIX. That is not surprising. There is a limit to the decline in bond vol from here, though. As Gerard pointed out in a note yesterday (HERE), if employment growth were to run at a pace consistent with the most recent trend of demand growth, then the labor market would tighten. For now, there are likely limits to how much more bond vol and 10yr yields will fall. The downside risk to bond vol/10yr comes from lower population growth/the immigration reversal. Put simply. Fewer people = lower GDP. Demand growth would be biased lower over time as potential GDP moves lower. 10yr yields and bond vol would have more downside risk in that scenario. That is a discussion for another time, though.

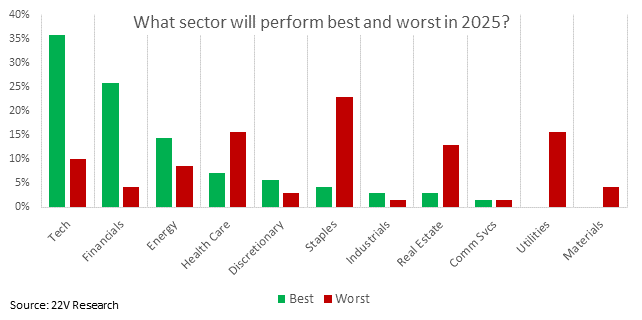
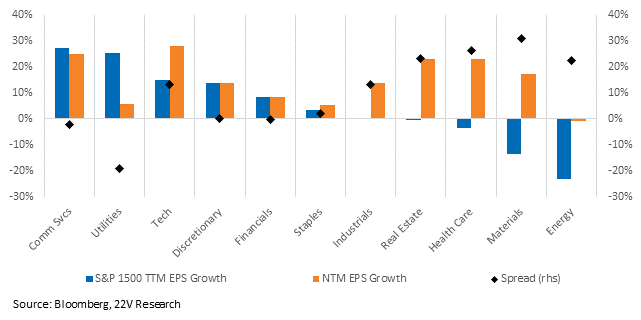
Investors were not enthused about Deep Cyclicals headings into the year (first chart). They have started off as the best performers of 2025. And Deep Cyclicals are expected to see significant improvement in earnings growth in 2025 (second chart). Leaving aside how the Deep Cyclical sectors will perform for the rest of 1Q, we are more focused on potential earnings beats. Consistent with our view that lower correlations will leave earnings beats/misses as the driver of returns.
To create lists to start looking for longs, we filter for both positive earnings sentiment and positive Quality factor scores. Historically, this process has generated better beat rates. Background info, the tables below use a sector-neutral version that does not work as well in the aggregate as our typical unconstrained version but it is interesting for a list to start looking for longs within sectors. We can send the opposite lists as well. Here are Industrials…
Materials…
And energy…