Back Economic Research

December Employment Report Brings the Heat

Published on January 10, 2025

Download the PDF Report

By

Peter Williams

December Employment Report Brings the Heat

  • The December employment report was hotter than expected nearly across the broad. NFP came in notably above expectations (+256k vs 165k survey, with minimal negative revisions) and the unemployment rate unexpectedly dropped 14bps, when consensus had been flat and the whisper (self-included) towards 4.3%.
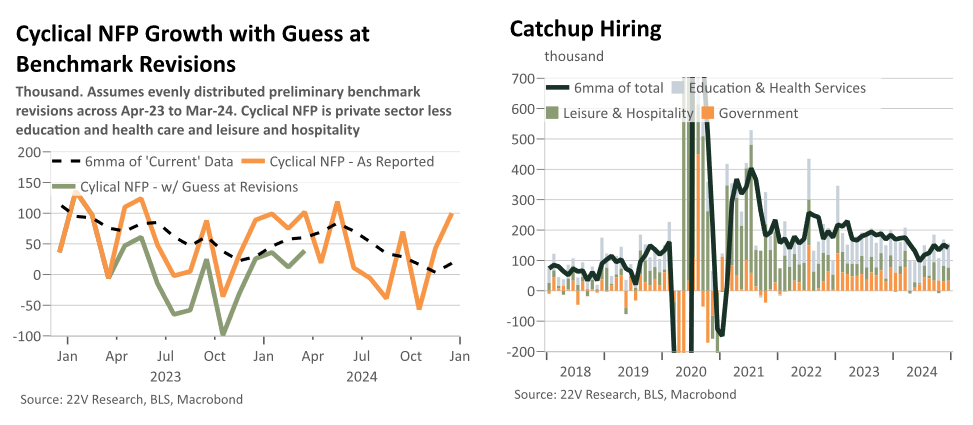
  • NFP saw another continued month of strength in catchup hiring sectors (gov’t, education and health care, and leisure and hospitality) while other, more cyclical, hiring had its strongest month of gains since May ’24.
  • The household survey was broadly strong across the board, with most measures of slack looking slightly firmer on the month.
  • There is a chance that the some of the strength in Dec’s data is due to seasonal adjustment noise (the bounce in retail trade seems most suspicious), as we have seen in the jobless claims data, but the broader context is still solid if not spectacular. It is also worth remembering that next month will see substantial downward revisions to the level of NFP in March ’24 and likely some carryforward into the rest of 2024, as well as population estimate updates to the household survey.
  • Wage growth was not soft enough to offset the overheating concerns, and general evidence that higher for longer rates may be necessary, which this data highlights. The burden of disproving overheating concerns will have to come from the inflation data as growth remains strong and, at least for this month, the labor market seems to be retightening a bit.
  • In recent months, the dovish labor-market driven pull towards cuts has been fading and today certainly attenuates that further. Having taken care of the first 100bps of insurance cuts additional easing, if it happens, will be a result of underlying inflation still gradually moving down and a continued, if less urgent, pull towards neutral. That of course assumes the labor market remains healthy enough.

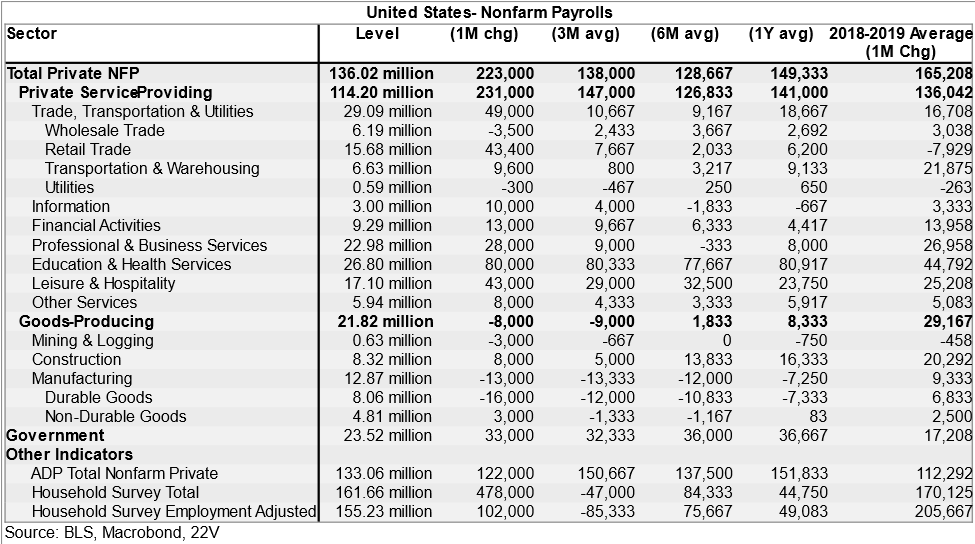
Non-farm payrolls growth came in well above expectations. This was a result of continued strong catchup hiring in government, education and health care, and leisure and hospitality. The strength of this catchup hiring over the past few years is one of the key forces which prevented the US from entering a recession when so many indicators suggest, and forecasters expected that outcome. Other hiring (‘cyclical hiring’) had its strongest month since May. This included an slightly suspiciously strong retail trade number (+43k) as well as the best white collar hiring print since May.

Perhaps the only really weaker bit of a data in the employment side was the soft manufacturing employment number. The sector has been in the doldrums for 2y so the gradual job shedding over recent months, taking into account the symmetric noise from Boeing and the port strikes, is not particularly surprising. This could become a larger risk if rates stay high and global manufacturing activity weak, but it seems questionable if manufacturing weakness alone could derail the overall outlook more than just change its composition, although the manufacturing cycle does matter for markets.

Wage growth and take home income both look solid and seem consistent with inflation running moderately above target but not so hot that the Fed is forced to really lurch hawkish again.
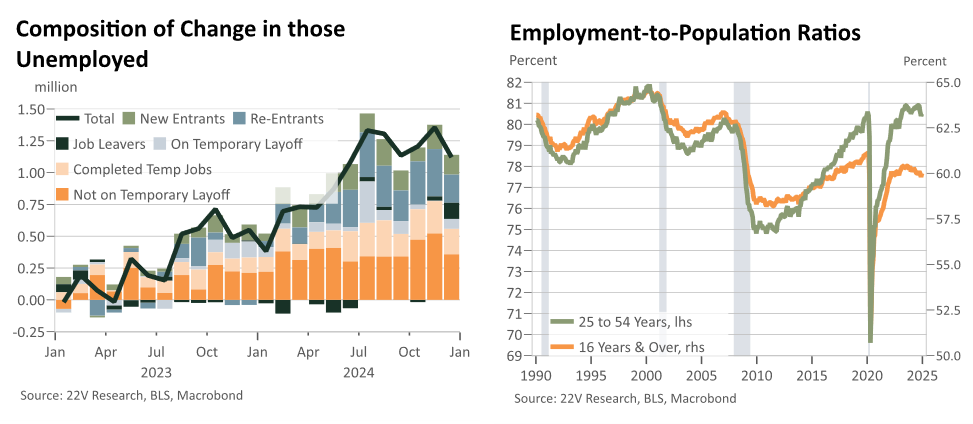
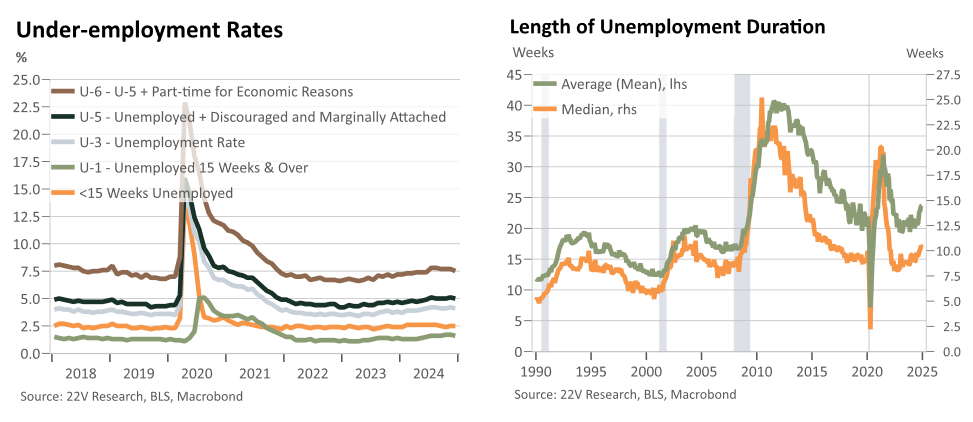
In the household survey, most measures of slack were a bit tighter, or at least not weaker, in December. This includes the drop in the unemployment rate and the U6 under-employment rate, the increase in the prime-age employment to population ratio, and a slight decline in the median duration of unemployment. The composition of those unemployed was also somewhat helpful with the number of worked on layoff, most importantly those on permanent layoff, dropping a bit and suggesting that relatively flat range that series has been in since the start of the year continues to hold (broadly consistent with continuing claims low single digit y/y growth in recent months).

The broad trends across data series have been towards gradual but linear and well-behaved easing of labor market slack. It will be interesting to see if the JOLTS data validate the message from the employment report or if they have a more ADP- and claims-like continuation of recent solid-but-not-spectacular trends.

In my base case, hiring levels will remain broadly steady in 2025 but the composition of demand will get somewhat better as catchup hiring fades and white collar hiring gradually starts to rebound. At the same time, immigration inflows slowing notably will reduce labor supply growth and eventually see slack start to stabilize and retighten some over the course of 2025. The key endogenous risks stem from the housing and manufacturing sectors, as well as the possibility than white collar employment growth, after an anemic few years, doesn’t start to reaccelerate as it very tentatively and sluggishly appears to be doing.
DISCLOSURES AND DISCLAIMERS

Analyst Certification

The analyst, 22V Research Group, primarily responsible for the preparation of this research report attests to the following: (1) that the views and opinions rendered in this research report reflect his or her personal views about the subject companies or issuers; and (2) that no part of the research analyst’s compensation was, is, or will be directly related to the specific recommendations or views in this research report.

Analyst Certifications and Independence of Research.

Each of the 22V Research analysts whose names appear on the front page of this report hereby certify that all the views expressed in this Report accurately reflect our personal views about any and all of the subject securities or issuers and that no part of our compensation was, is, or will be, directly or indirectly, related to the specific recommendations or views of in this Report.

22V Research (the “Company”) is an independent research provider. The Company is not a member of the FINRA or the SIPC and is not a registered broker dealer or investment adviser. 22V Research has no other regulated or unregulated business activities which conflict with its provision of independent research.

22V Research, LLC is a professional services and independent publication organization. 22V Research, LLC is not a securities broker-dealer, not a member of the Financial Industry Regulatory Authority (FINRA), not a registered investment advisor (RIA) and not a member of SIPC.

Securities transactions, when offered, are offered by 22V Securities, LLC through LPS Capital, LLC. Certain employees of 22V Securities, LLC are dually registered as securities representatives of LPS Capital, LLC or Analyst Hub Securities, LLC. 22V Securities, LPS Capital and Analyst Hub Securities are members FINRA, SIPC.

https://brokercheck.finra.org/

Current Ratings Definition.

SECTOR OUTPERFORM: An “outperform” rating anticipates the company will outperform the S&P Regional Banking Index (peer group).

SECTOR PERFORM: A “market perform” rating anticipates the company will perform in line with the S&P Regional Banking Index (peer group).

SECTOR UNDERPERFORM: An “underperform” rating anticipates the company will underperform the S&P Regional Banking Index (peer group).

Limitation Of Research And Information.

This Report has been prepared for distribution to only qualified institutional or professional clients of 22V Research Group. The contents of this Report represent the views, opinions, and analyses of its authors. The information contained herein does not constitute financial, legal, tax or any other advice. All third-party data presented herein were obtained from publicly available sources which are believed to be reliable; however, the Company makes no warranty, express or implied, concerning the accuracy or completeness of such information. In no event shall the Company be responsible or liable for the correctness of, or update to, any such material or for any damage or lost opportunities resulting from use of this data. Nothing contained in this Report or any distribution by the Company should be construed as any offer to sell, or any solicitation of an offer to buy, any security or investment. Any research or other material received should not be construed as individualized investment advice. Investment decisions should be made as part of an overall portfolio strategy and you should consult with a professional financial advisor, legal and tax advisor prior to making any investment decision. 22V Research Group shall not be liable for any direct or indirect, incidental or consequential loss or damage (including loss of profits, revenue or goodwill) arising from any investment decisions based on information or research obtained from 22V Research Group.

Reproduction And Distribution Strictly Prohibited.

No user of this Report may reproduce, modify, copy, distribute, sell, resell, transmit, transfer, license, assign or publish the Report itself or any information contained therein. Notwithstanding the foregoing, clients with access to working models are permitted to alter or modify the information contained therein, provided that it is solely for such client’s own use. This Report is not intended to be available or distributed for any purpose that would be deemed unlawful or otherwise prohibited by any local, state, national or international laws or regulations or would otherwise subject the Company to registration or regulation of any kind within such jurisdiction.

Copyrights, Trademarks, Intellectual Property.

22V Research Group, and any logos or marks included in this Report are proprietary materials. The use of such terms and logos and marks without the express written consent of 22V Research Group is strictly prohibited. The copyright in the pages or in the screens of the Report, and in the information and material therein, is proprietary material owned by 22V Research Group unless otherwise indicated. The unauthorized use of any material on this Report may violate numerous statutes, regulations and laws, including, but not limited to, copyright, trademark, trade secret or patent laws.